MUDRA Loan Statistics 2025-26: Sanctions, Shishu/Kishor/Tarun Split and NPA Rates
By ClauseAudit Research · 7 sources ·
What do the latest MUDRA loan statistics for India show?
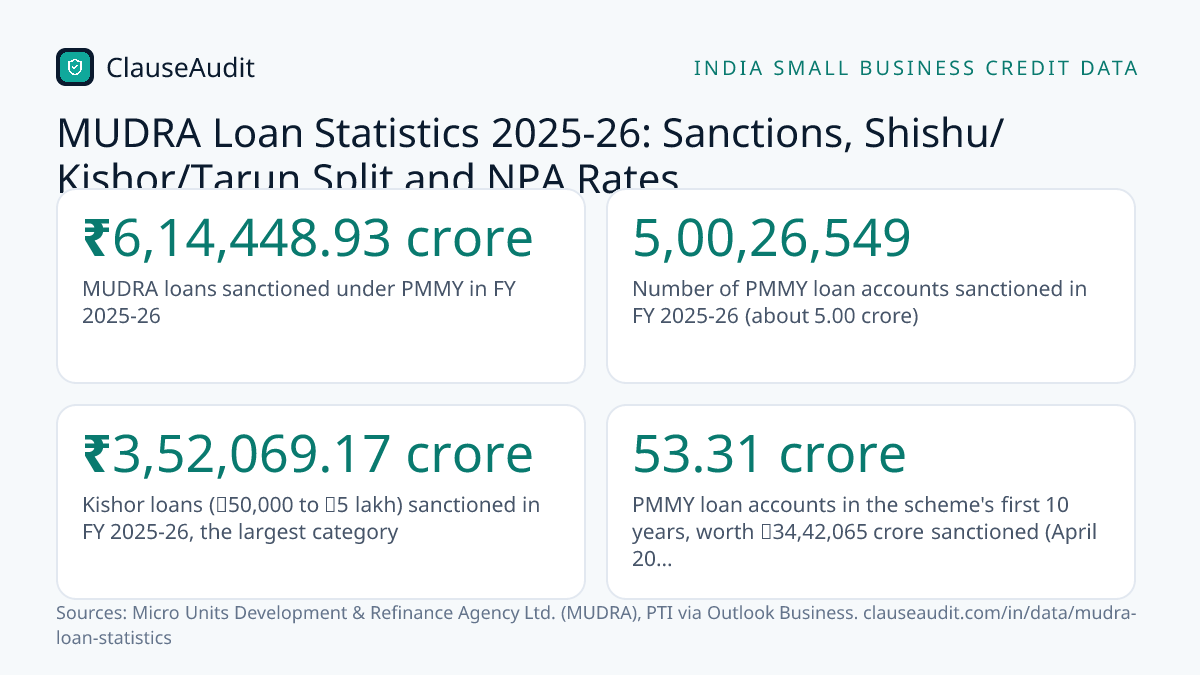
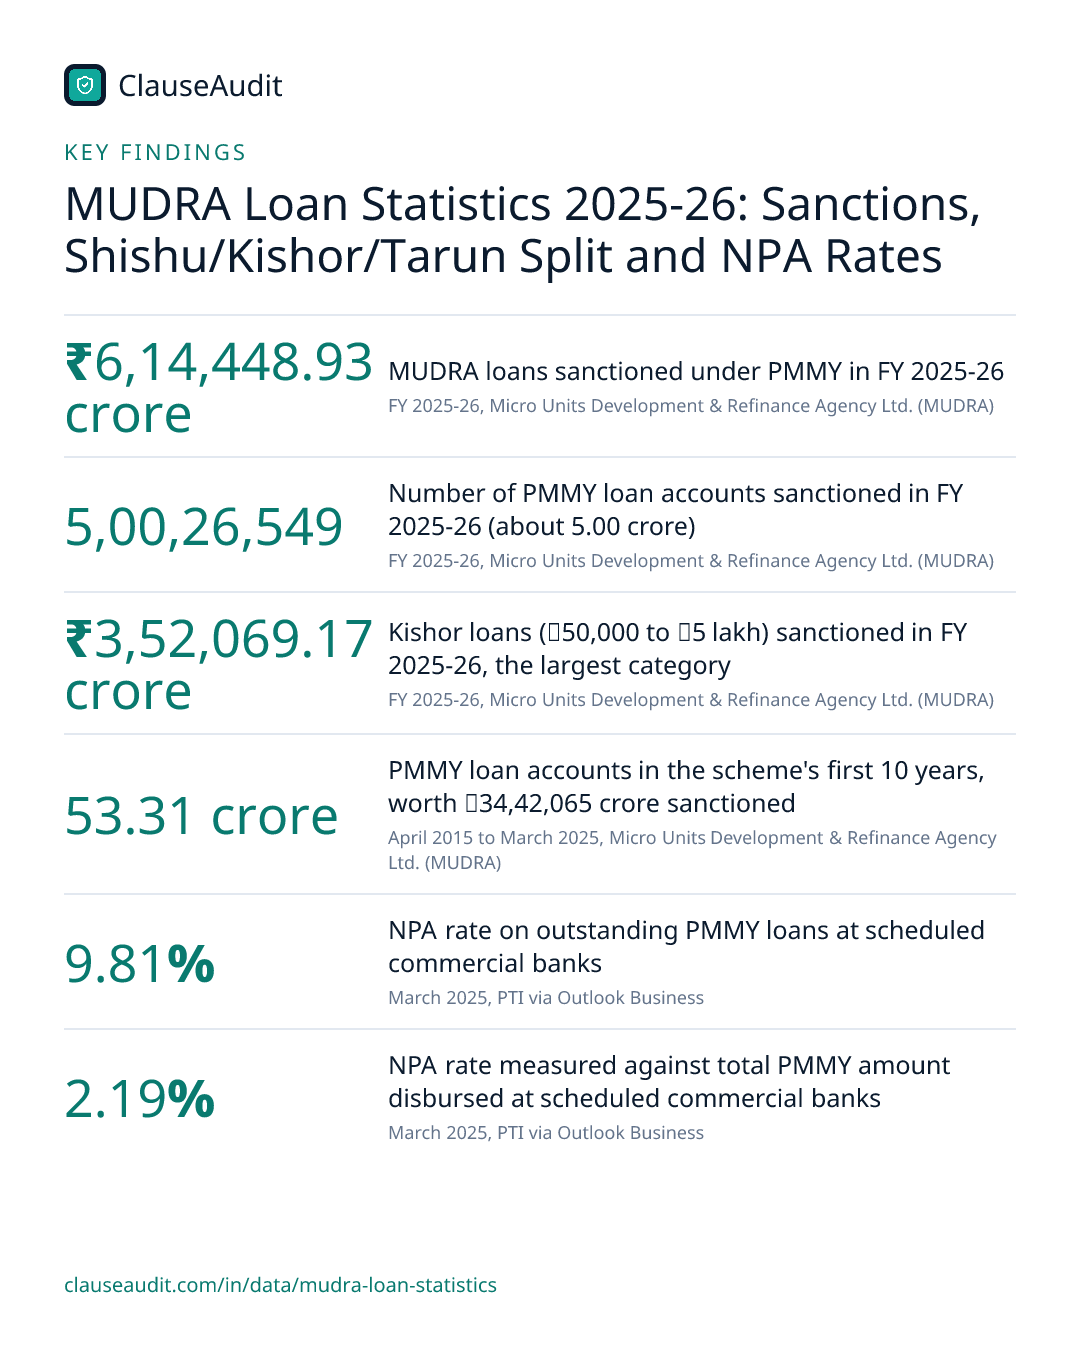
MUDRA lending keeps growing in value while reaching fewer accounts. Lenders sanctioned ₹6,14,448.93 crore under PMMY in FY 2025-26 across 5,00,26,549 loan accounts, down from 5,46,61,648 accounts the year before. Kishor loans of ₹50,000 to ₹5 lakh took the largest share, and NPAs at scheduled commercial banks hit 9.81% of outstanding PMMY loans in March 2025.
- MUDRA loans sanctioned under PMMY in FY 2025-26 (FY 2025-26, Micro Units Development & Refinance Agency Ltd. (MUDRA))
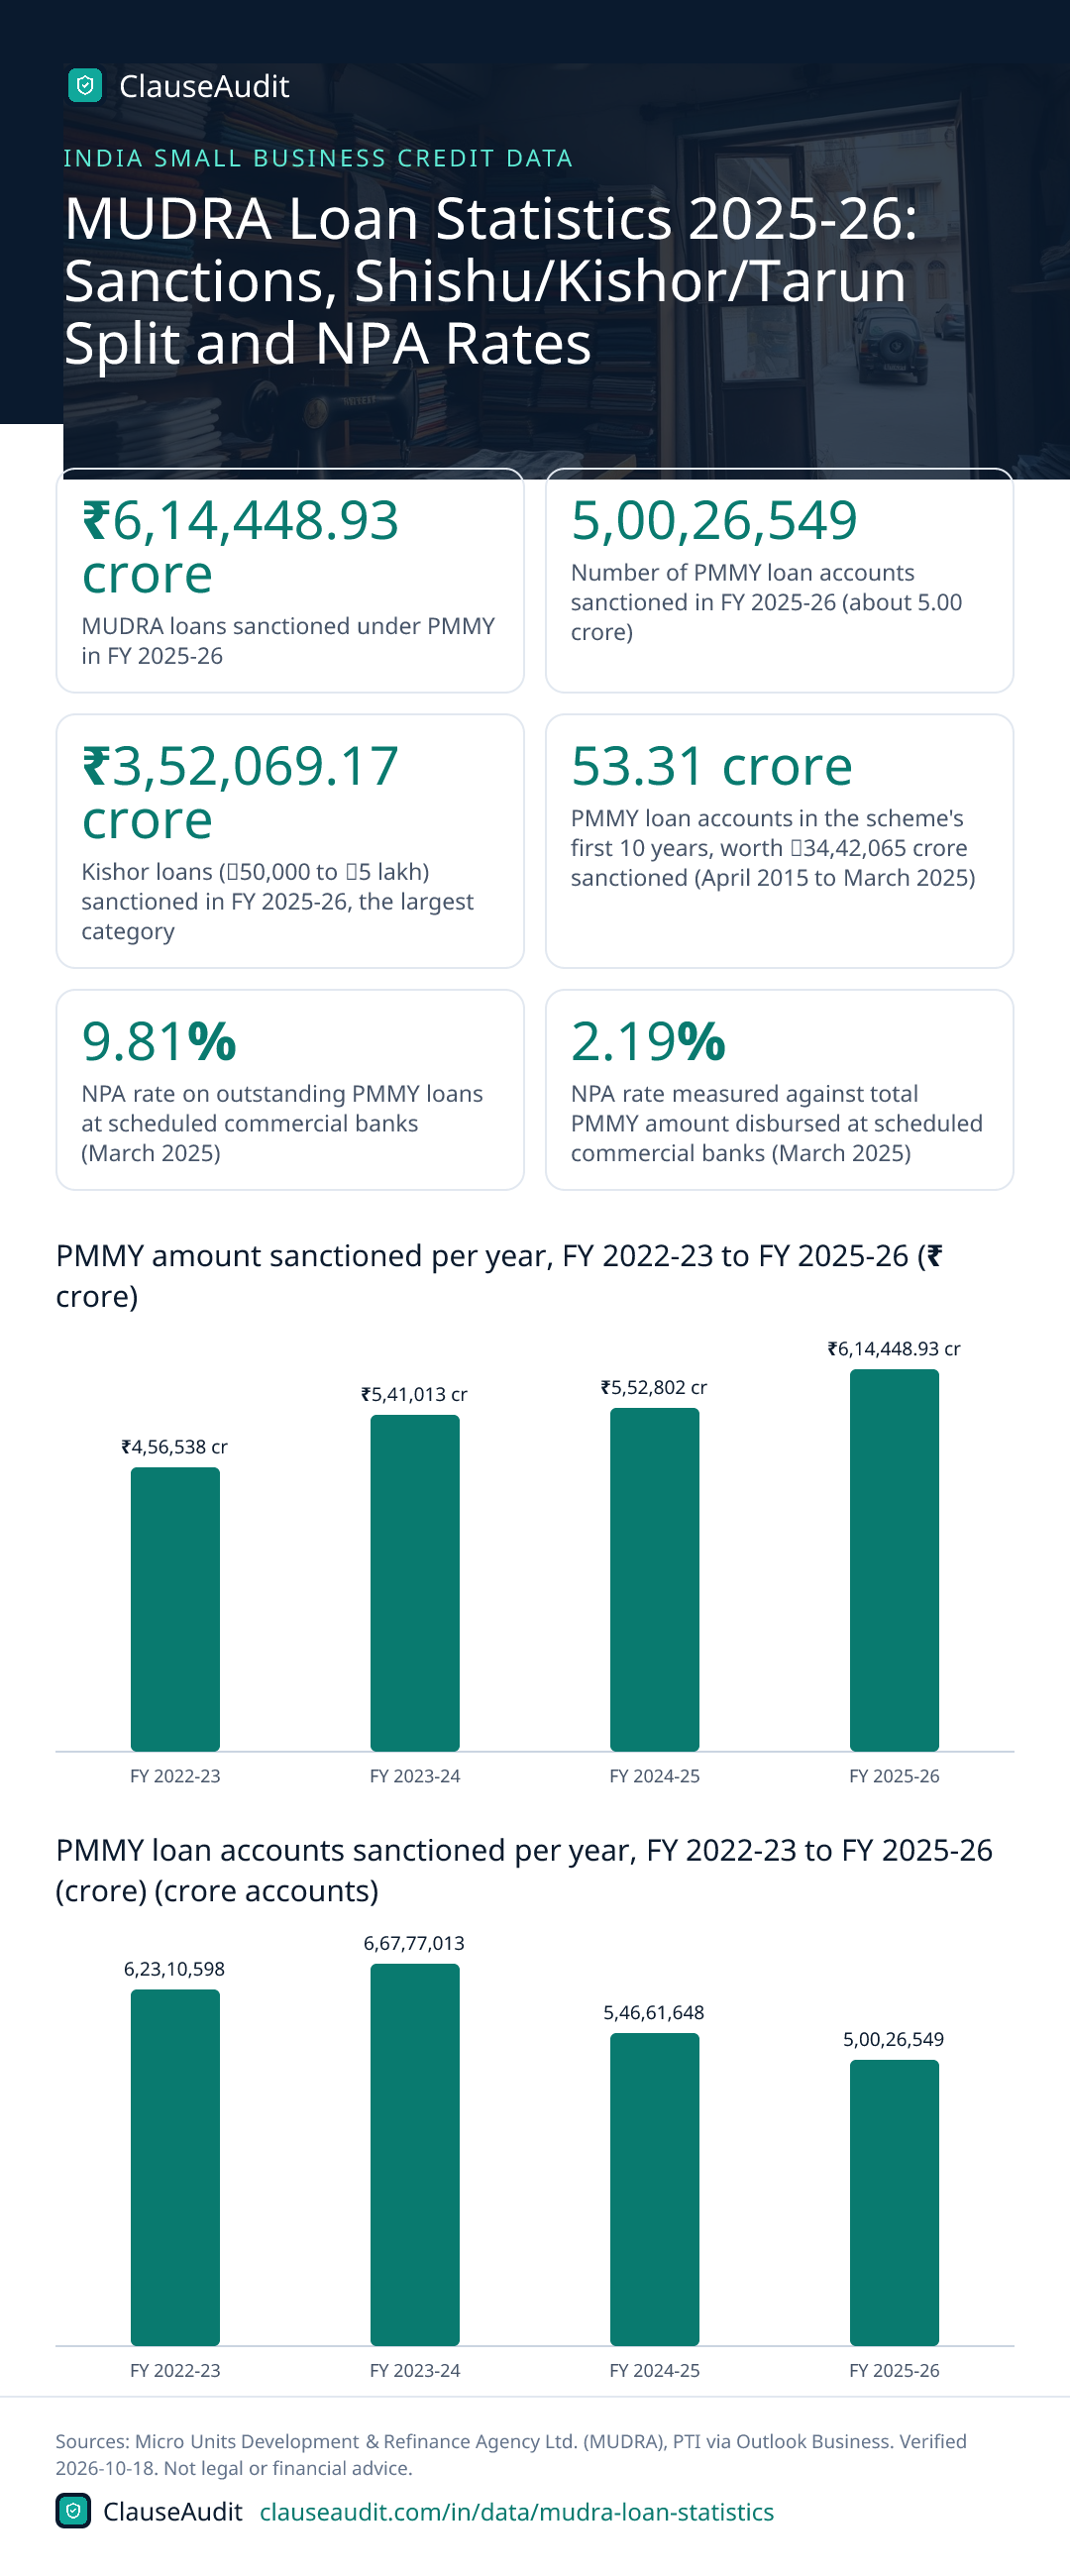
- ₹6,14,448.93 crore
- Number of PMMY loan accounts sanctioned in FY 2025-26 (about 5.00 crore) (FY 2025-26, Micro Units Development & Refinance Agency Ltd. (MUDRA))
- 5,00,26,549
- Kishor loans (₹50,000 to ₹5 lakh) sanctioned in FY 2025-26, the largest category (FY 2025-26, Micro Units Development & Refinance Agency Ltd. (MUDRA))
- ₹3,52,069.17 crore
- PMMY loan accounts in the scheme's first 10 years, worth ₹34,42,065 crore sanctioned (April 2015 to March 2025, Micro Units Development & Refinance Agency Ltd. (MUDRA))
- 53.31 crore
- NPA rate on outstanding PMMY loans at scheduled commercial banks (March 2025, PTI via Outlook Business)
- 9.81%
- NPA rate measured against total PMMY amount disbursed at scheduled commercial banks (March 2025, PTI via Outlook Business)
- 2.19%
- PMMY loan accounts sanctioned to women entrepreneurs in FY 2025-26 (FY 2025-26, Micro Units Development & Refinance Agency Ltd. (MUDRA))
- 2,88,67,071
- PMMY loans sanctioned in FY 2026-27 so far, across 2,27,91,746 loans (provisional) (FY 2026-27, as of 16 October 2026, Micro Units Development & Refinance Agency Ltd. (MUDRA))
- ₹3,09,480.51 crore
The Pradhan Mantri MUDRA Yojana is the government loan scheme many Indian tailors, kirana owners, repair shops and one-person service businesses hear about first. In FY 2025-26 it sanctioned about ₹6.14 lakh crore. That is more money than any year before it, spread over fewer accounts than the two years before.
This page sets out the official MUDRA numbers on sanctions, the Shishu, Kishor and Tarun split, state totals and NPA rates. Below the charts, you will find what the shift means for a small business owner or freelancer thinking about a MUDRA loan, and the loan terms worth reading before you sign the sanction letter.
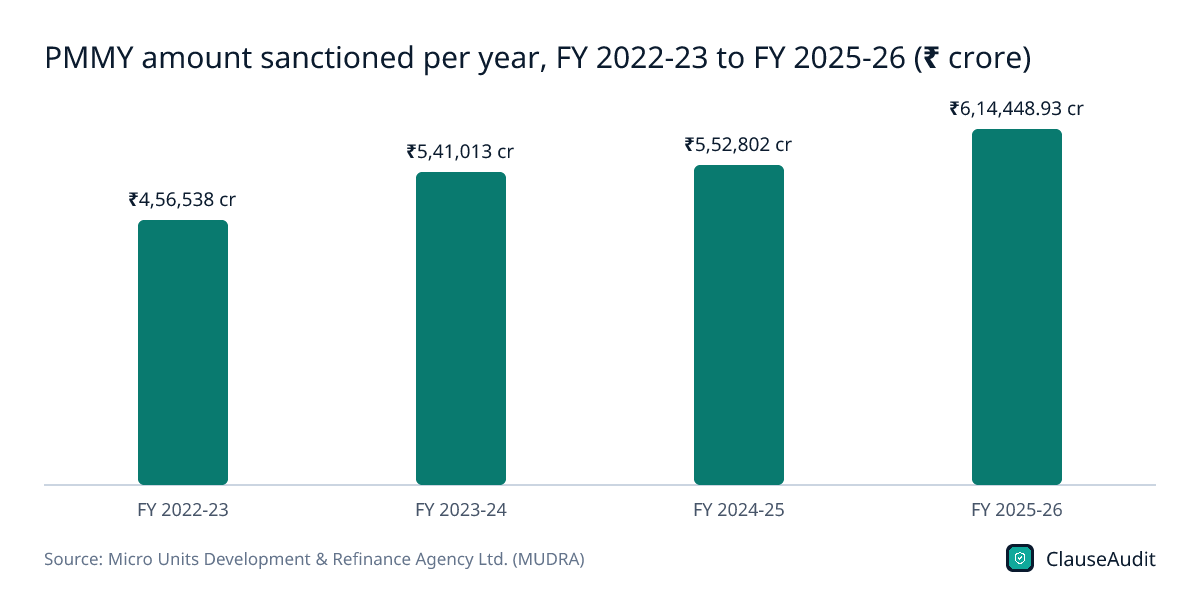
PMMY amount sanctioned per year, FY 2022-23 to FY 2025-26 (₹ crore)
Chart data
| Label | Value |
|---|---|
| FY 2022-23 | ₹4,56,538 cr |
| FY 2023-24 | ₹5,41,013 cr |
| FY 2024-25 | ₹5,52,802 cr |
| FY 2025-26 | ₹6,14,448.93 cr |
The amount sanctioned rose every year in this run, from ₹4,56,538 crore in FY 2022-23 to ₹6,14,448.93 crore in FY 2025-26. FY 2026-27 had already reached ₹3,09,480.51 crore by 16 October 2026, on provisional figures.
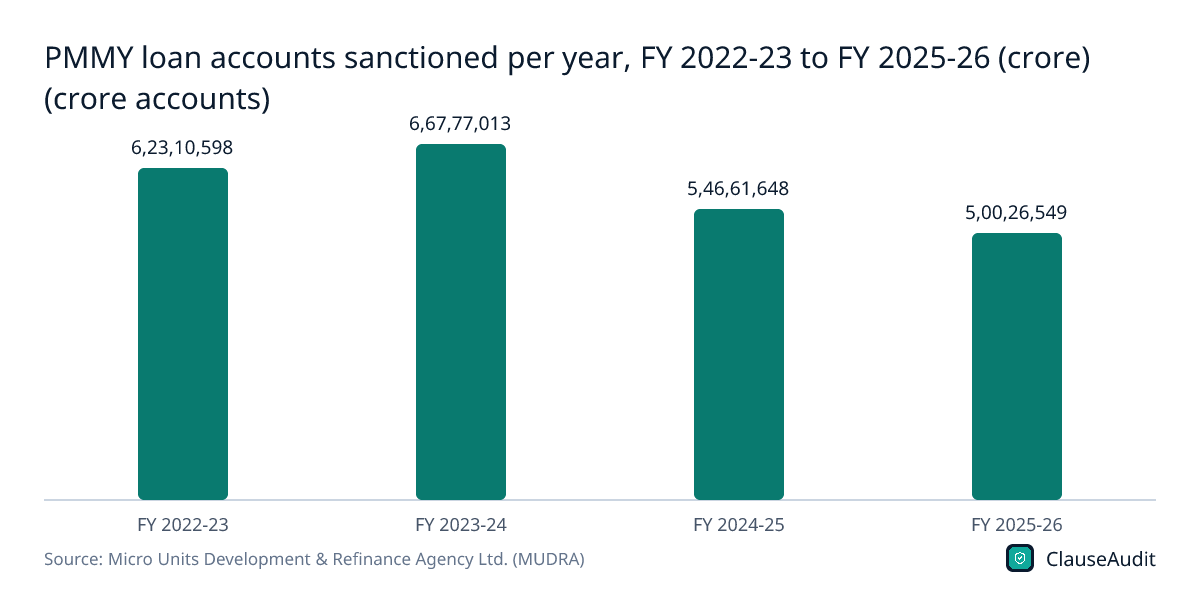
Download this chart (PNG)PMMY loan accounts sanctioned per year, FY 2022-23 to FY 2025-26 (crore) (crore accounts)
Chart data
| Label | Value (crore accounts) |
|---|---|
| FY 2022-23 | 6,23,10,598 |
| FY 2023-24 | 6,67,77,013 |
| FY 2024-25 | 5,46,61,648 |
| FY 2025-26 | 5,00,26,549 |
Accounts peaked at 6,67,77,013 in FY 2023-24 and have fallen since. With the amount still climbing, each loan is getting bigger on average.
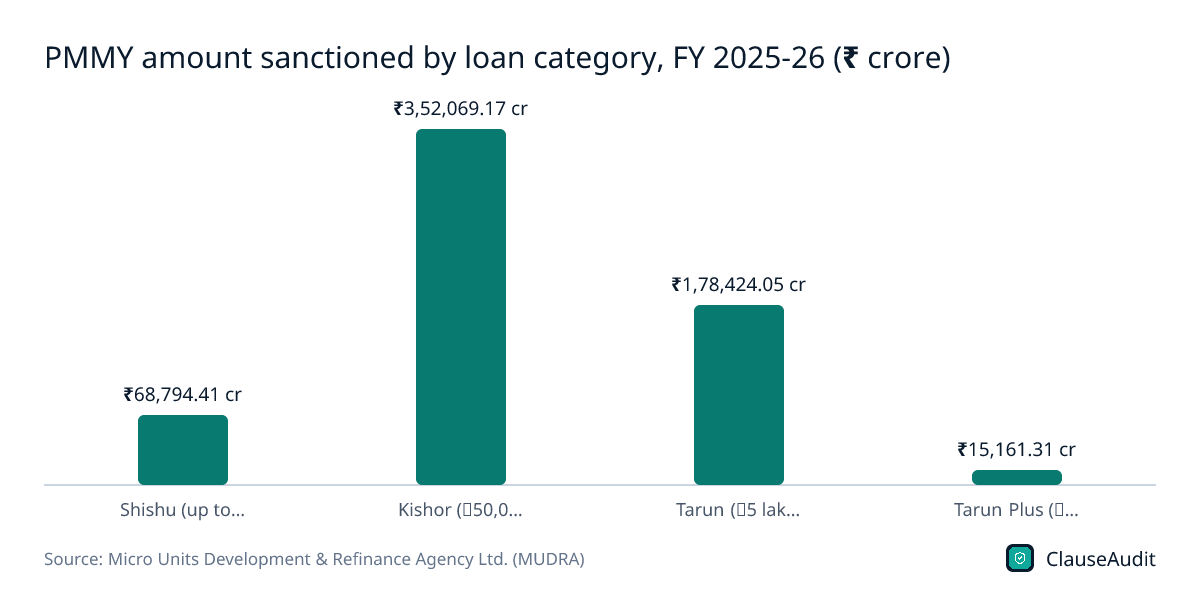
Download this chart (PNG)PMMY amount sanctioned by loan category, FY 2025-26 (₹ crore)
Chart data
| Label | Value |
|---|---|
| Shishu (up to ₹50,000) | ₹68,794.41 cr |
| Kishor (₹50,000 to ₹5 lakh) | ₹3,52,069.17 cr |
| Tarun (₹5 lakh to ₹10 lakh) | ₹1,78,424.05 cr |
| Tarun Plus (₹10 lakh to ₹20 lakh) | ₹15,161.31 cr |
Kishor dominates. At ₹3,52,069.17 crore it is more than five times the Shishu total, and Tarun Plus is still small at ₹15,161.31 crore in its early years.
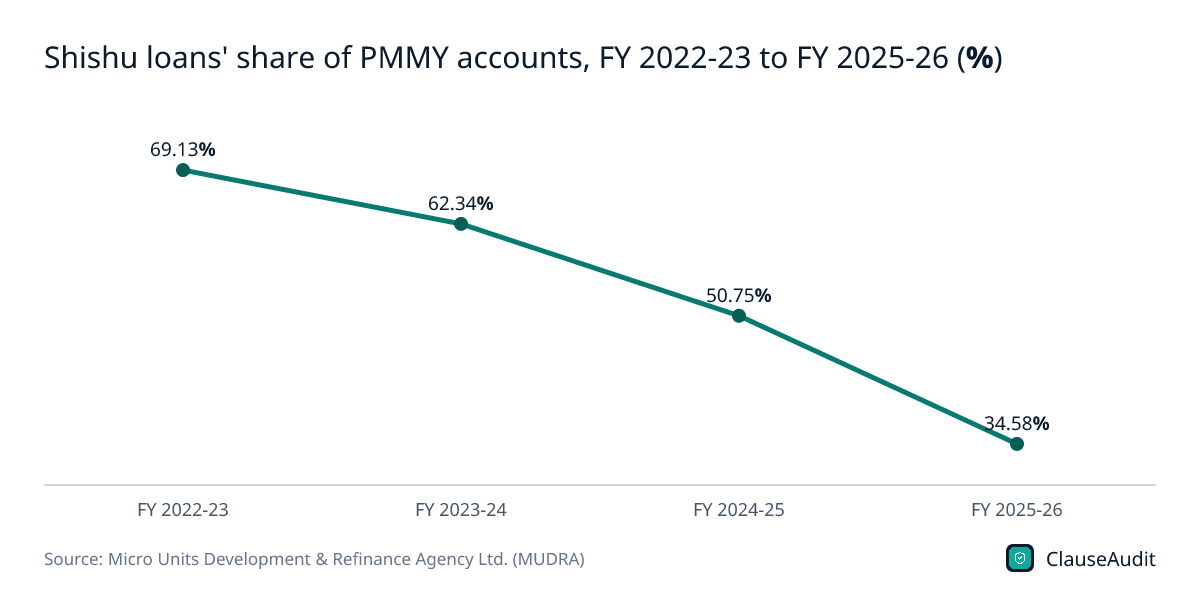
Download this chart (PNG)The smallest loans went from 69.13% of accounts in FY 2022-23 to 34.58% in FY 2025-26. Lenders are now writing mostly mid-sized MUDRA loans.
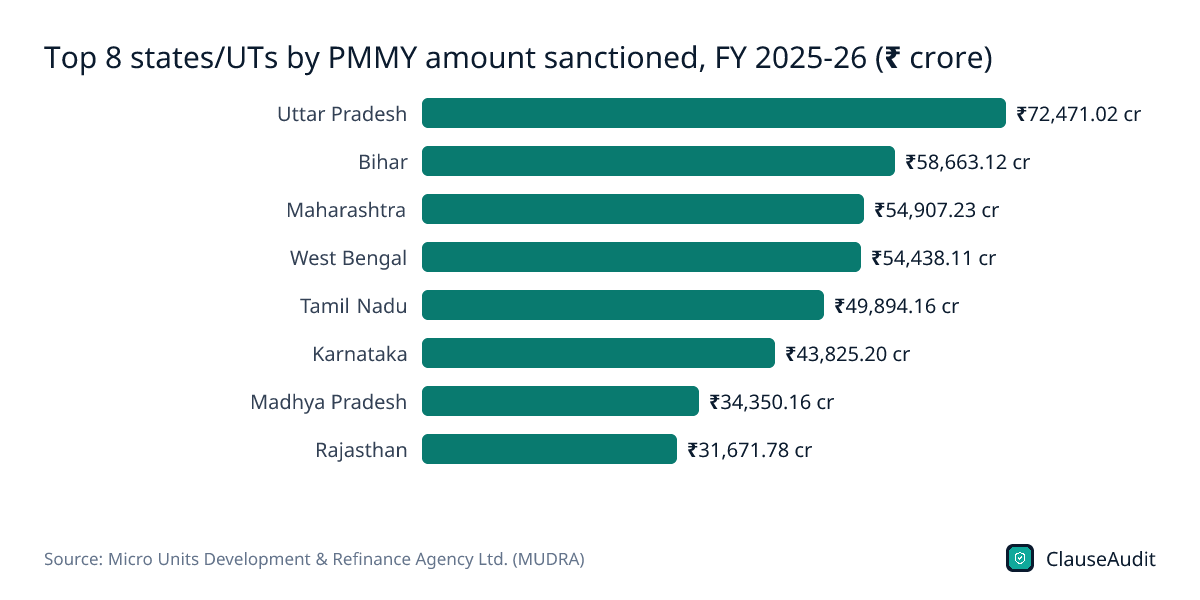
Download this chart (PNG)Top 8 states/UTs by PMMY amount sanctioned, FY 2025-26 (₹ crore)
Chart data
| Label | Value |
|---|---|
| Uttar Pradesh | ₹72,471.02 cr |
| Bihar | ₹58,663.12 cr |
| Maharashtra | ₹54,907.23 cr |
| West Bengal | ₹54,438.11 cr |
| Tamil Nadu | ₹49,894.16 cr |
| Karnataka | ₹43,825.20 cr |
| Madhya Pradesh | ₹34,350.16 cr |
| Rajasthan | ₹31,671.78 cr |
Uttar Pradesh leads on money at ₹72,471.02 crore. Bihar comes second on money but actually had more accounts than Uttar Pradesh, which tells you its loans were smaller.
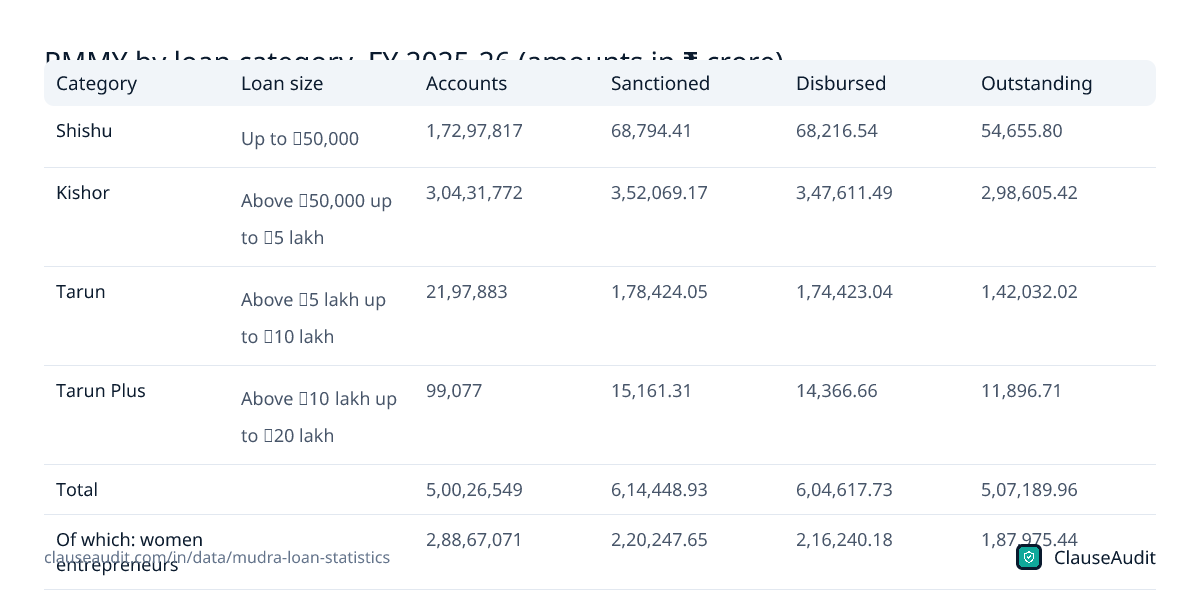
Download this chart (PNG)PMMY by loan category, FY 2025-26 (amounts in ₹ crore)
| Category | Loan size | Accounts | Sanctioned | Disbursed | Outstanding |
|---|---|---|---|---|---|
| Shishu | Up to ₹50,000 | 1,72,97,817 | 68,794.41 | 68,216.54 | 54,655.80 |
| Kishor | Above ₹50,000 up to ₹5 lakh | 3,04,31,772 | 3,52,069.17 | 3,47,611.49 | 2,98,605.42 |
| Tarun | Above ₹5 lakh up to ₹10 lakh | 21,97,883 | 1,78,424.05 | 1,74,423.04 | 1,42,032.02 |
| Tarun Plus | Above ₹10 lakh up to ₹20 lakh | 99,077 | 15,161.31 | 14,366.66 | 11,896.71 |
| Total | 5,00,26,549 | 6,14,448.93 | 6,04,617.73 | 5,07,189.96 | |
| Of which: women entrepreneurs | 2,88,67,071 | 2,20,247.65 | 2,16,240.18 | 1,87,975.44 | |
| Of which: new entrepreneurs / accounts | 1,31,83,459 | 2,01,409.93 | 1,97,582.87 | 1,58,853.54 |
Source: Micro Units Development & Refinance Agency Ltd. (MUDRA), PMMY - Overall Performance Report, Financial Year 2025-26. Download as image
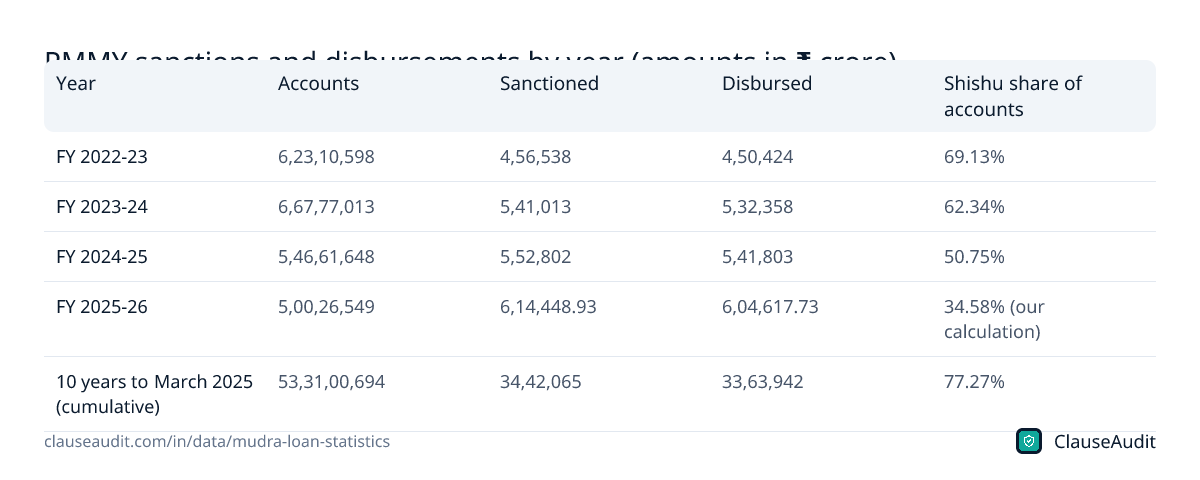
PMMY sanctions and disbursements by year (amounts in ₹ crore)
| Year | Accounts | Sanctioned | Disbursed | Shishu share of accounts |
|---|---|---|---|---|
| FY 2022-23 | 6,23,10,598 | 4,56,538 | 4,50,424 | 69.13% |
| FY 2023-24 | 6,67,77,013 | 5,41,013 | 5,32,358 | 62.34% |
| FY 2024-25 | 5,46,61,648 | 5,52,802 | 5,41,803 | 50.75% |
| FY 2025-26 | 5,00,26,549 | 6,14,448.93 | 6,04,617.73 | 34.58% (our calculation) |
| 10 years to March 2025 (cumulative) | 53,31,00,694 | 34,42,065 | 33,63,942 | 77.27% |
Source: Micro Units Development & Refinance Agency Ltd. (MUDRA), MUDRA Annual Report 2022-23 (Table 2: Categories of MUDRA loans and beneficiaries); Micro Units Development & Refinance Agency Ltd. (MUDRA), MUDRA Annual Report 2023-24 (Table 2: Categories of MUDRA loans and beneficiaries); Micro Units Development & Refinance Agency Ltd. (MUDRA), MUDRA Annual Report 2024-25 (Table 2: Categories of MUDRA loans and beneficiaries); Micro Units Development & Refinance Agency Ltd. (MUDRA), PMMY - Overall Performance Report, Financial Year 2025-26. Download as image
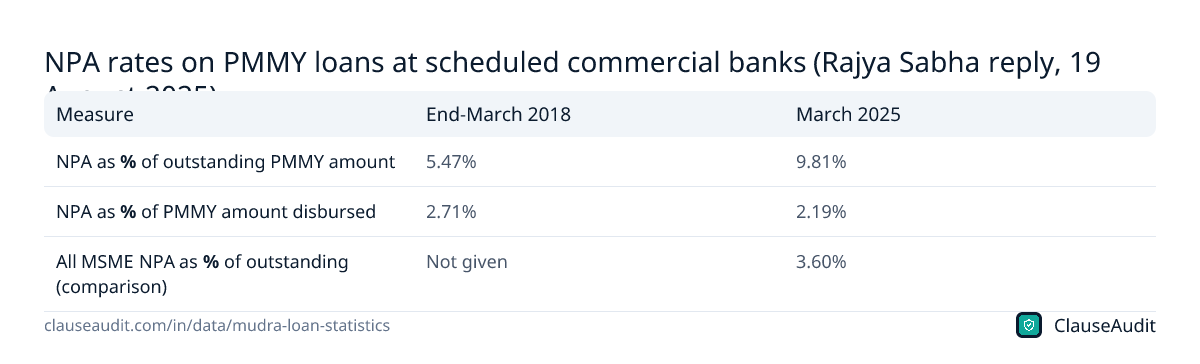
NPA rates on PMMY loans at scheduled commercial banks (Rajya Sabha reply, 19 August 2025)
| Measure | End-March 2018 | March 2025 |
|---|---|---|
| NPA as % of outstanding PMMY amount | 5.47% | 9.81% |
| NPA as % of PMMY amount disbursed | 2.71% | 2.19% |
| All MSME NPA as % of outstanding (comparison) | Not given | 3.60% |
Source: PTI via Outlook Business, NPA Against Outstanding Amount Under Mudra Yojana rises to 9.8% at Mar 2025 (PTI report of a Rajya Sabha written reply). Download as image
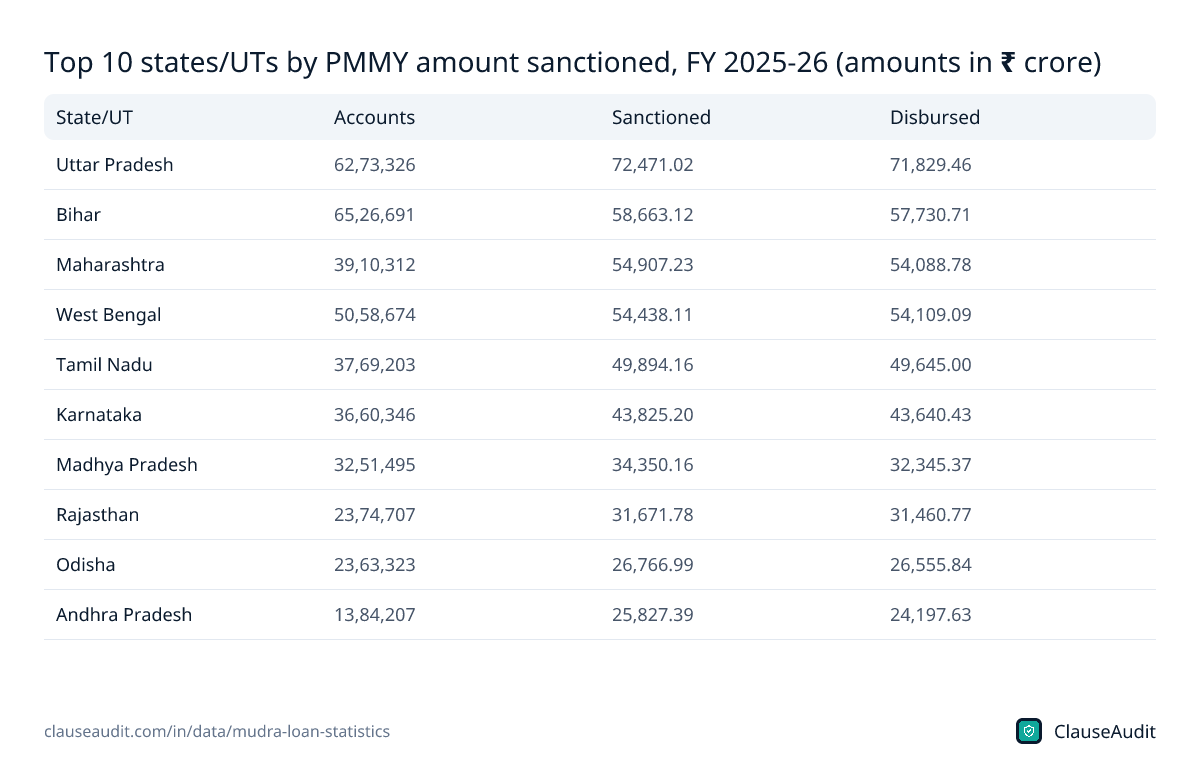
Top 10 states/UTs by PMMY amount sanctioned, FY 2025-26 (amounts in ₹ crore)
| State/UT | Accounts | Sanctioned | Disbursed |
|---|---|---|---|
| Uttar Pradesh | 62,73,326 | 72,471.02 | 71,829.46 |
| Bihar | 65,26,691 | 58,663.12 | 57,730.71 |
| Maharashtra | 39,10,312 | 54,907.23 | 54,088.78 |
| West Bengal | 50,58,674 | 54,438.11 | 54,109.09 |
| Tamil Nadu | 37,69,203 | 49,894.16 | 49,645.00 |
| Karnataka | 36,60,346 | 43,825.20 | 43,640.43 |
| Madhya Pradesh | 32,51,495 | 34,350.16 | 32,345.37 |
| Rajasthan | 23,74,707 | 31,671.78 | 31,460.77 |
| Odisha | 23,63,323 | 26,766.99 | 26,555.84 |
| Andhra Pradesh | 13,84,207 | 25,827.39 | 24,197.63 |
Source: Micro Units Development & Refinance Agency Ltd. (MUDRA), PMMY - State wise Performance, Financial Year 2025-26. Download as image
How much MUDRA loan money was sanctioned in 2025-26?
Lenders sanctioned ₹6,14,448.93 crore under PMMY in FY 2025-26 and disbursed ₹6,04,617.73 crore. The gap between the two is small, so once a loan is approved, the money mostly does reach the borrower.
The headline growth hides a quieter change. The number of accounts dropped to 5,00,26,549, from 5,46,61,648 in FY 2024-25 and 6,67,77,013 in FY 2023-24. Banks are lending more money to fewer people.
What does that mean on the ground? A bigger average loan is good news if you run a growing workshop that needs a second machine. It is less helpful if you are a home baker who wants a modest sum for an oven and finds the branch more interested in larger files.
The current year is moving at a similar pace. By 16 October 2026, MUDRA's provisional running total for FY 2026-27 showed ₹3,09,480.51 crore sanctioned across 2,27,91,746 loans. Treat that as a moving figure, since MUDRA revises it as banks report.
For scale, the scheme's first ten years, from April 2015 to March 2025, added up to 53.31 crore accounts and ₹34,42,065 crore sanctioned. Some people borrow more than once, so the account count is not the same as the number of people helped.
Why are Shishu loans shrinking and Kishor loans growing?
Shishu loans cover up to ₹50,000. Across the scheme's first decade they made up 77.27% of accounts. In FY 2025-26 they were down to 34.58% of accounts and just 11.20% of the money.
Kishor loans, from ₹50,000 to ₹5 lakh, filled the space. They accounted for 3,04,31,772 accounts in FY 2025-26, or 60.83% of all accounts and 57.30% of the amount sanctioned.
Part of this is borrowers graduating. A street food seller who repaid a Shishu loan can come back for a Kishor loan to buy a cart and a fridge. Part of it is probably lender preference: a bigger loan costs a bank about the same to process as a tiny one.
If you are a first-time borrower who only needs a small sum, this matters. You may find the branch nudging you toward a larger amount than you asked for. Borrow what your cash flow can repay, not what the officer finds easier to book.
What is the NPA rate on MUDRA loans?
The government told the Rajya Sabha in a written reply in August 2025 that NPAs on PMMY loans at scheduled commercial banks stood at 9.81% of the outstanding amount in March 2025, up from 5.47% at the end of March 2018. Measured against the total amount ever disbursed, the rate was 2.19%, down from 2.71%.
Both figures are true. They just divide by different things. The outstanding measure compares bad loans with what borrowers still owe today, and it is the better guide to current stress. For comparison, NPAs across all MSME lending were 3.60% of outstanding in March 2025.
For you, a higher NPA rate usually means tighter checks. Expect banks to ask for bank statements, GST returns or proof of steady orders, and to look closely at your credit report. It also means a missed EMI gets noticed fast, and a MUDRA default stays on your credit history when you later want a bigger loan.
Which states get the most MUDRA loans?
Uttar Pradesh led FY 2025-26 with ₹72,471.02 crore sanctioned, followed by Bihar at ₹58,663.12 crore and Maharashtra at ₹54,907.23 crore.
The account counts tell a different story. Bihar had 65,26,691 accounts, more than Uttar Pradesh's 62,73,326. Maharashtra had only 39,10,312 accounts but slightly more money than West Bengal, which had 50,58,674. Loan sizes clearly differ a lot between states, which likely reflects local business costs and how each state's banks use the scheme.
If you live in a state with fewer, larger loans, do not read that as a sign you must borrow big. Branch practice varies from one district to the next. Ask the bank which category your request falls under, what documents it wants for that category, and how long sanction usually takes. Then compare at least two lenders, including a regional rural bank or small finance bank if one operates near you.
How many MUDRA loans go to women and new businesses?
Women entrepreneurs held 2,88,67,071 accounts in FY 2025-26, which is 57.70% of all accounts. Their share of the money was lower, at 35.84%, or ₹2,20,247.65 crore. Women borrowers are getting in the door, but their loans are smaller on average.
New entrepreneurs and new accounts made up 1,31,83,459 accounts and ₹2,01,409.93 crore sanctioned. So the scheme still reaches plenty of first-time borrowers.
If you are a woman running a home business, the gap between account share and money share is worth knowing before you apply. Have your numbers ready to justify the amount you actually need, whether that is stock for a saree business or equipment for a beauty parlour, rather than accepting a smaller sanction by default.
What to do before you take a MUDRA loan
A MUDRA loan is still a bank loan. It carries interest, a repayment schedule and consequences for default, and the paperwork you sign at the branch sets all of that. A little preparation before you apply saves trouble later.
- Work out the EMI against your slowest month, not your best one. If a client pays late, the bank still debits on the due date.
- Line up your client contracts first. A freelancer whose clients pay on vague 'final approval' terms, or with no late fee, will struggle to plan repayments. Fix those terms before you commit to a fixed EMI.
- Ask for the sanction letter and loan agreement in writing before signing, and read the interest reset, penal charge and security clauses.
- Decline add-on insurance or other products you did not ask for, unless you actually want them.
- Keep your Udyam registration and GST records current. They make the next, larger loan easier to get.
- If repayment gets tight, talk to the branch before you miss an EMI. Restructuring is easier to discuss before an account turns into an NPA.
How ClauseAudit helps
A MUDRA loan comes with a sanction letter and a loan agreement, and the terms inside them decide what the loan really costs you. Most borrowers sign them at the branch in a few minutes.
Upload your loan agreement or sanction letter and our automated review flags the clauses that tend to cause trouble later, explained in plain English.
- Interest rate: whether it is floating, which benchmark it tracks and when the bank can reset it
- Penal charges and late payment terms if an EMI bounces
- Security, hypothecation and any personal guarantee or third-party guarantee asked for
- Foreclosure and prepayment charges if you want to close the loan early
- Default, recall and set-off clauses that let the bank debit your other accounts
- Bundled insurance or processing fees added to the loan amount
Frequently asked questions
How much was sanctioned under MUDRA in 2025-26?
MUDRA's Overall Performance Report shows ₹6,14,448.93 crore sanctioned under PMMY in FY 2025-26, across 5,00,26,549 loan accounts. Of that, ₹6,04,617.73 crore was actually disbursed. The amount was higher than FY 2024-25, when ₹5,52,802 crore was sanctioned, even though the number of accounts fell.
What are the Shishu, Kishor, Tarun and Tarun Plus loan limits?
Shishu covers loans up to ₹50,000. Kishor covers loans above ₹50,000 up to ₹5 lakh. Tarun covers loans above ₹5 lakh up to ₹10 lakh, and Tarun Plus covers loans above ₹10 lakh up to ₹20 lakh. Tarun Plus is the newest category and accounted for 99,077 accounts in FY 2025-26.
Which MUDRA category gets the most money?
Kishor, by a wide margin. In FY 2025-26, Kishor loans accounted for ₹3,52,069.17 crore, or 57.30% of all money sanctioned under PMMY. Tarun came next at ₹1,78,424.05 crore. Shishu loans were the most common for years but took only 11.20% of the amount in FY 2025-26.
What is the MUDRA loan NPA rate?
As of March 2025, NPAs on PMMY loans at scheduled commercial banks were 9.81% of the outstanding amount, according to a Rajya Sabha reply reported by PTI. Against the total amount ever disbursed, the figure was 2.19%. The outstanding measure is the better guide to current stress, and it has risen from 5.47% in March 2018.
Why did the number of MUDRA loans fall?
Accounts fell from 6,67,77,013 in FY 2023-24 to 5,00,26,549 in FY 2025-26, while the amount sanctioned kept rising. The drop came mostly from Shishu loans, whose share of accounts fell to 34.58%. Repeat borrowers moving to larger loans and stricter checks after rising NPAs likely both play a part.
Which state has the most MUDRA loans?
By amount, Uttar Pradesh led FY 2025-26 with ₹72,471.02 crore sanctioned. By number of accounts, Bihar was ahead with 65,26,691 accounts against Uttar Pradesh's 62,73,326. Maharashtra, West Bengal and Tamil Nadu followed on amount. The table above shows the top 10 states.
How many MUDRA loans go to women?
Women entrepreneurs received 2,88,67,071 PMMY loan accounts in FY 2025-26, which is 57.70% of all accounts sanctioned that year. The amount sanctioned to them was ₹2,20,247.65 crore, or 35.84% of the total. So women hold most loan accounts, but their loans are smaller on average.
Can a freelancer get a MUDRA loan?
MUDRA is meant for income-generating micro and small businesses in manufacturing, trading, services and activities allied to farming, and many service providers and self-employed professionals apply. Banks will want to see a steady income, so bank statements, GST returns, Udyam registration and signed client contracts with clear payment terms all help. Read the loan agreement as carefully as you read a client contract.
Is FY 2026-27 MUDRA data available yet?
Only as a provisional running total. MUDRA's homepage showed ₹3,09,480.51 crore sanctioned across 2,27,91,746 loans for FY 2026-27 as of 16 October 2026, with ₹2,99,025.19 crore disbursed. The final yearly report usually comes out after the financial year closes, so these numbers will change.
Use this data
Every chart and card below is free to reuse under CC BY 4.0. Download what you need and link back to this page.
 Stat cards
 Key findings card
 Infographic
 PMMY amount sanctioned per year, FY 2022-23 to FY 2025-26 (₹ crore)
 PMMY loan accounts sanctioned per year, FY 2022-23 to FY 2025-26 (crore) (crore accounts)
 PMMY amount sanctioned by loan category, FY 2025-26 (₹ crore)
 Shishu loans' share of PMMY accounts, FY 2022-23 to FY 2025-26 (%)
 Top 8 states/UTs by PMMY amount sanctioned, FY 2025-26 (₹ crore)
 PMMY by loan category, FY 2025-26 (amounts in ₹ crore)
 PMMY sanctions and disbursements by year (amounts in ₹ crore)
 NPA rates on PMMY loans at scheduled commercial banks (Rajya Sabha reply, 19 August 2025)
 Top 10 states/UTs by PMMY amount sanctioned, FY 2025-26 (amounts in ₹ crore)
Embed the infographic
Free to share on your site, blog or slides under CC BY 4.0. Please keep the credit link.
Sources and method
Every number on this page comes from the sources below, each opened and read on or before October 18, 2026. A second, independent review checked every figure against its source and corrected anything that did not match. Figures that could not be confirmed were left out.
- Micro Units Development & Refinance Agency Ltd. (MUDRA), PMMY - Overall Performance Report, Financial Year 2025-26 (Financial Year 2025-26 (PDF dated 4 June 2026))
- Micro Units Development & Refinance Agency Ltd. (MUDRA), PMMY - State wise Performance, Financial Year 2025-26 (Financial Year 2025-26)
- Micro Units Development & Refinance Agency Ltd. (MUDRA), MUDRA homepage: PMMY running totals for Financial Year 2026-2027 (provisional) (Last updated 16/10/2026)
- Micro Units Development & Refinance Agency Ltd. (MUDRA), MUDRA Annual Report 2024-25 (Table 2: Categories of MUDRA loans and beneficiaries) (Annual Report 2024-25)
- Micro Units Development & Refinance Agency Ltd. (MUDRA), MUDRA Annual Report 2023-24 (Table 2: Categories of MUDRA loans and beneficiaries) (Annual Report 2023-24)
- Micro Units Development & Refinance Agency Ltd. (MUDRA), MUDRA Annual Report 2022-23 (Table 2: Categories of MUDRA loans and beneficiaries) (Annual Report 2022-23)
- PTI via Outlook Business, NPA Against Outstanding Amount Under Mudra Yojana rises to 9.8% at Mar 2025 (PTI report of a Rajya Sabha written reply) (19 August 2025)
Cite this page
ClauseAudit, “MUDRA Loan Statistics 2025-26: Sanctions, Shishu/Kishor/Tarun Split and NPA Rates”, updated October 18, 2026, https://clauseaudit.com/in/data/mudra-loan-statistics. Free to reuse with a link back (CC BY 4.0).
This page summarises published data and law as checked on October 18, 2026. Figures are updated as new editions are released, and your own situation may differ. It is general information, not legal, tax or financial advice.