Small Business Loan and Financing Statistics 2026: 170 Numbers on Approvals, SBA Loans, Rates and Debt
By ClauseAudit Research · 170 statistics · 81 sources ·
What are the key small business loan statistics for 2026?
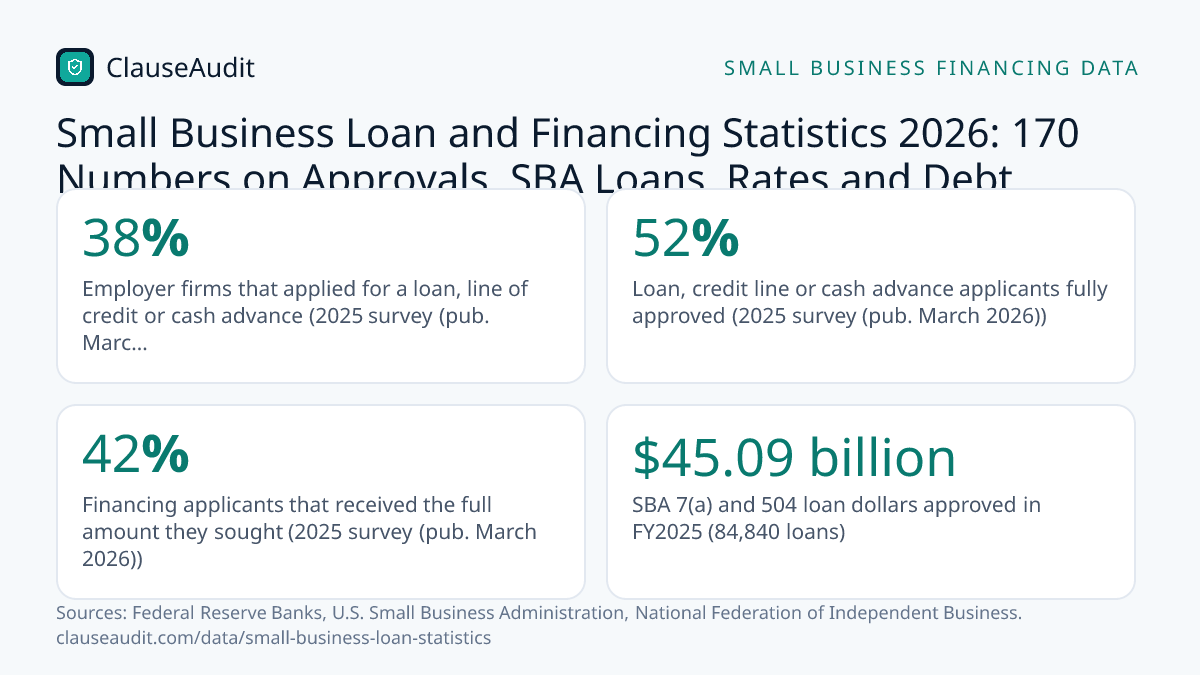
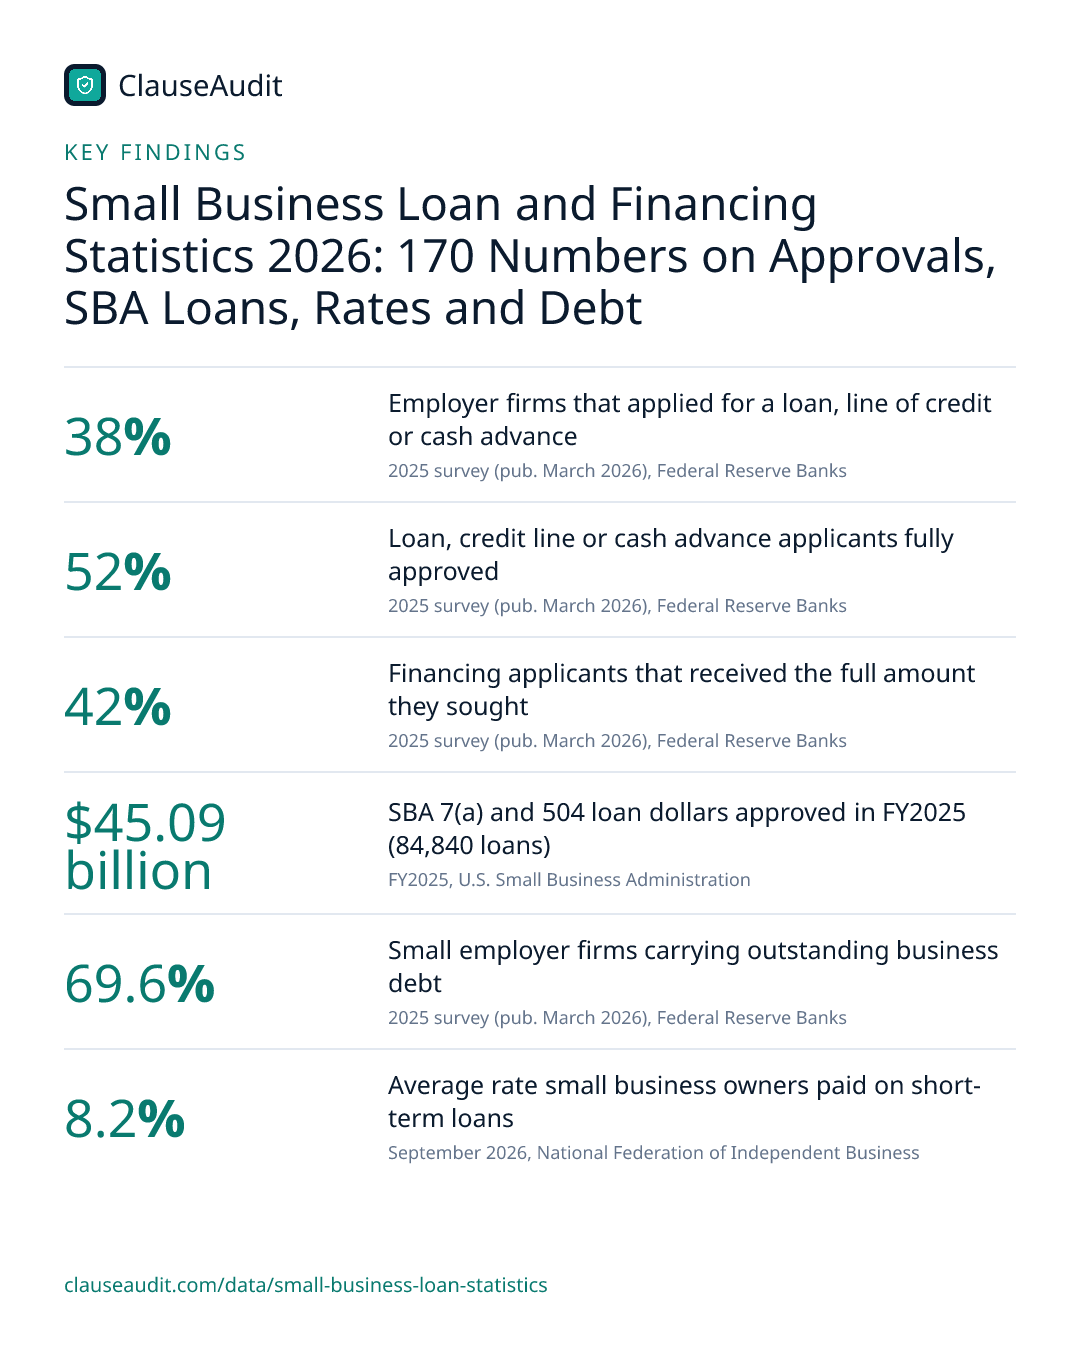
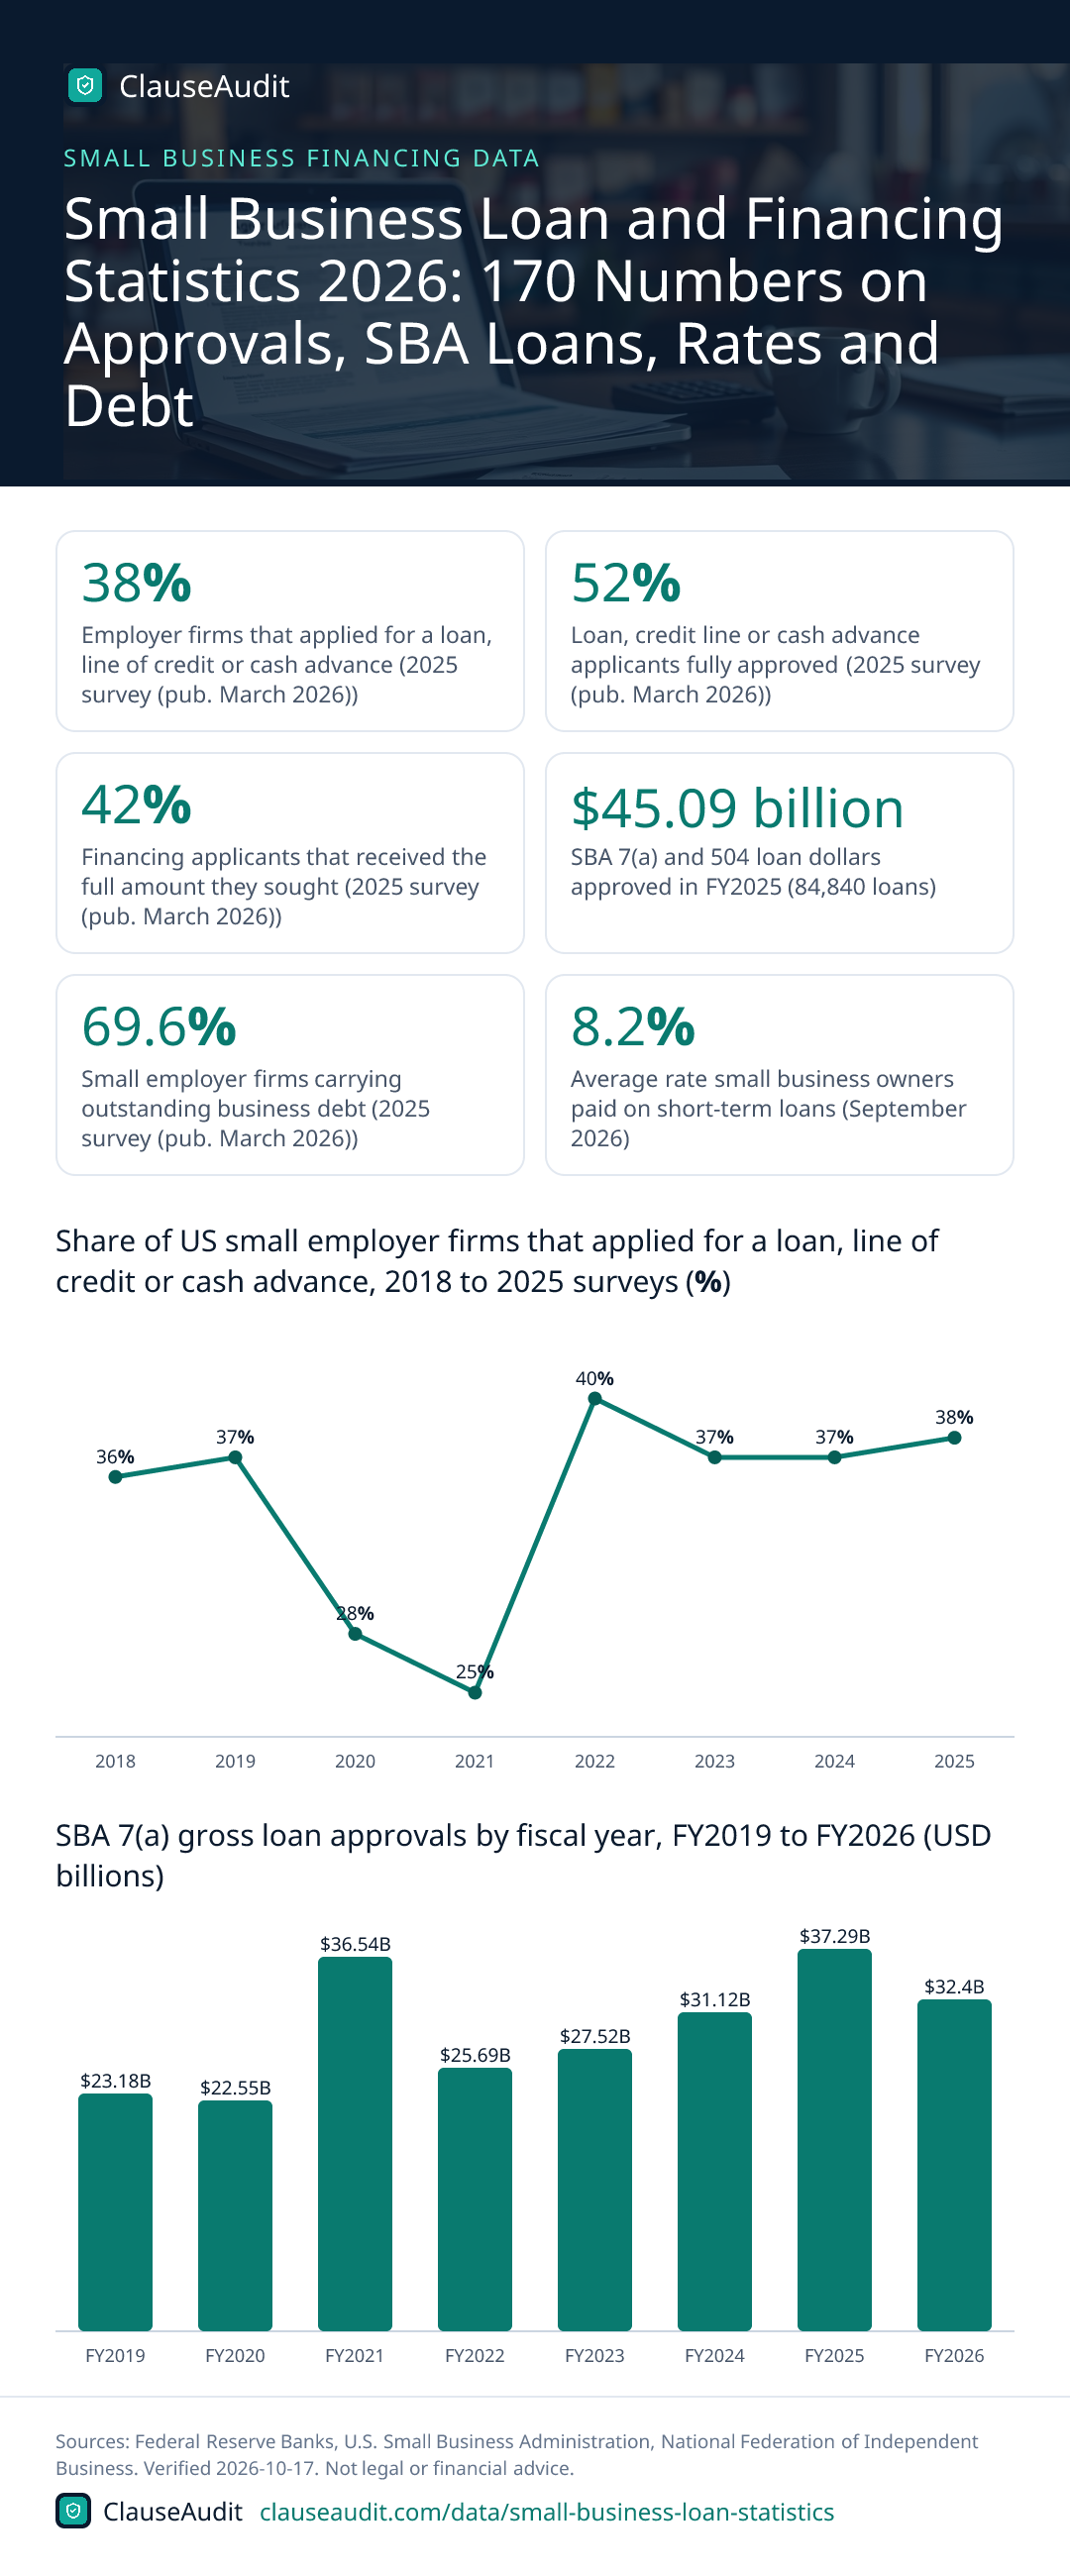
In the Federal Reserve's 2025 Small Business Credit Survey, 38% of small employer firms applied for a loan, line of credit or cash advance, and 52% of applicants were fully approved. Only 42% got the full amount they sought. The SBA approved $45.09 billion in 7(a) and 504 loans in FY2025, and 69.6% of employer firms carry debt.
- Employer firms that applied for a loan, line of credit or cash advance (2025 survey (pub. March 2026), Federal Reserve Banks)
- 38%
- Loan, credit line or cash advance applicants fully approved (2025 survey (pub. March 2026), Federal Reserve Banks)
- 52%
- Financing applicants that received the full amount they sought (2025 survey (pub. March 2026), Federal Reserve Banks)
- 42%
- SBA 7(a) and 504 loan dollars approved in FY2025 (84,840 loans) (FY2025, U.S. Small Business Administration)
- $45.09 billion
- Small employer firms carrying outstanding business debt (2025 survey (pub. March 2026), Federal Reserve Banks)
- 69.6%
- Average rate small business owners paid on short-term loans (September 2026, National Federation of Independent Business)
- 8.2%
- Online lender borrowers whose costs ran higher than expected (2025 survey (pub. March 2026), Federal Reserve Banks)
- 60%
- Black-owned firm applicants fully approved for financing (2025 survey (pub. March 2026), Federal Reserve Banks)
- 32%
This page collects 170 small business loan and financing statistics in twelve groups: demand and applications, approval rates, lender types, SBA programs, business debt, interest rates and borrowing costs, bank lending conditions, defaults and delinquencies, women- and minority-owned firms, equipment and alternative finance, India's MSME credit market and the global SME finance gap.
Most US figures come from the Federal Reserve Banks' Small Business Credit Survey, SBA activity reports, the Federal Reserve's senior loan officer survey, FDIC and Census Bureau data and the NFIB's monthly survey, with industry and lender data labeled as such. Every number links to its source, and the data was checked on October 17, 2026.
Small Business Financing Demand and Loan Application Statistics
Six in ten small employer firms sought some type of financing in the 2025 survey, but only 38% applied for a loan, line of credit or cash advance. These figures show who applied, why, and how many came away short.
- 60% of US small employer firms applied for some type of financing in the 12 months before the 2025 Small Business Credit Survey. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
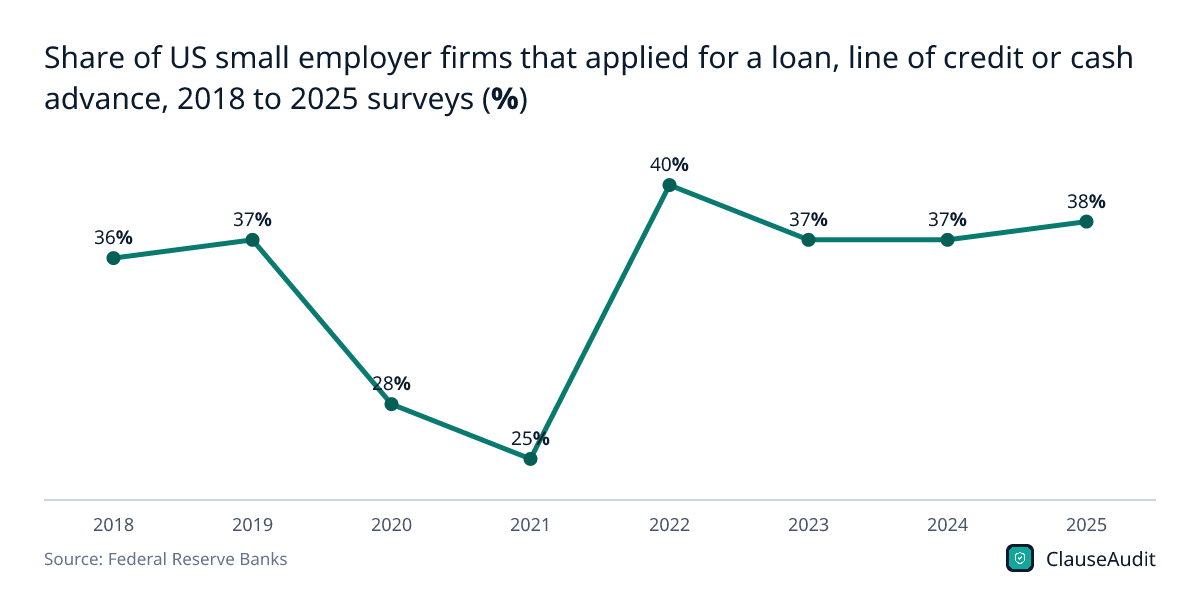
- 38% of small employer firms applied for a loan, line of credit or merchant cash advance, nearly unchanged from the 2024 survey. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 26% of employer firms applied for a business loan, while 24% applied for a line of credit and 8% for a merchant cash advance. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 56% of financing applicants sought money to meet operating expenses, the most common reason small businesses applied. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 46% of financing applicants wanted to expand, pursue a new opportunity or acquire business assets. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 42% of financing applicants sought credit to keep available for future use as needed, while 28% wanted to refinance or pay down debt. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 63% of firms that did not apply for financing said they did not need it or already had sufficient financing. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 10% of nonapplicant firms were discouraged borrowers that expected to be turned down, while 17% were debt averse and 7% found credit too costly. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 34% of all small employer firms applied for financing but had a shortfall, receiving less than the full amount they sought. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 15% of small employer firms needed financing but did not apply, leaving unmet funding needs; 51% had their funding needs met. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 534,947 new US business applications were filed in September 2026, seasonally adjusted, up 0.5% from August 2026. (U.S. Census Bureau, Business Formation Statistics, September 2026 (Release CB26-163), September 2026)
- 60% of small business owners who expect to borrow plan to use the funds for working capital, according to Barlow Research's Q1 2026 survey with Live Oak Bank. (Live Oak Bank, 2026 Small Business Insights (Barlow Research survey with Live Oak Bank), Q1 2026)
- 15% of responding Texas businesses reported at least some difficulty accessing short-term credit in October 2025, and 16% reported difficulty with long-term credit. (Federal Reserve Bank of Dallas, Texas Business Outlook Surveys: Special Questions, October 2025, October 2025)
Figure 1: Share of US small employer firms that applied for a loan, line of credit or cash advance, 2018 to 2025 surveys (%)
Chart data
| Label | Value (%) |
|---|---|
| 2018 | 36% |
| 2019 | 37% |
| 2020 | 28% |
| 2021 | 25% |
| 2022 | 40% |
| 2023 | 37% |
| 2024 | 37% |
| 2025 | 38% |
Small Business Loan Approval Rate Statistics
Approval is not all or nothing. The Federal Reserve's survey separates full approvals, partial approvals and denials, and the gaps by firm size, age and product are wide.
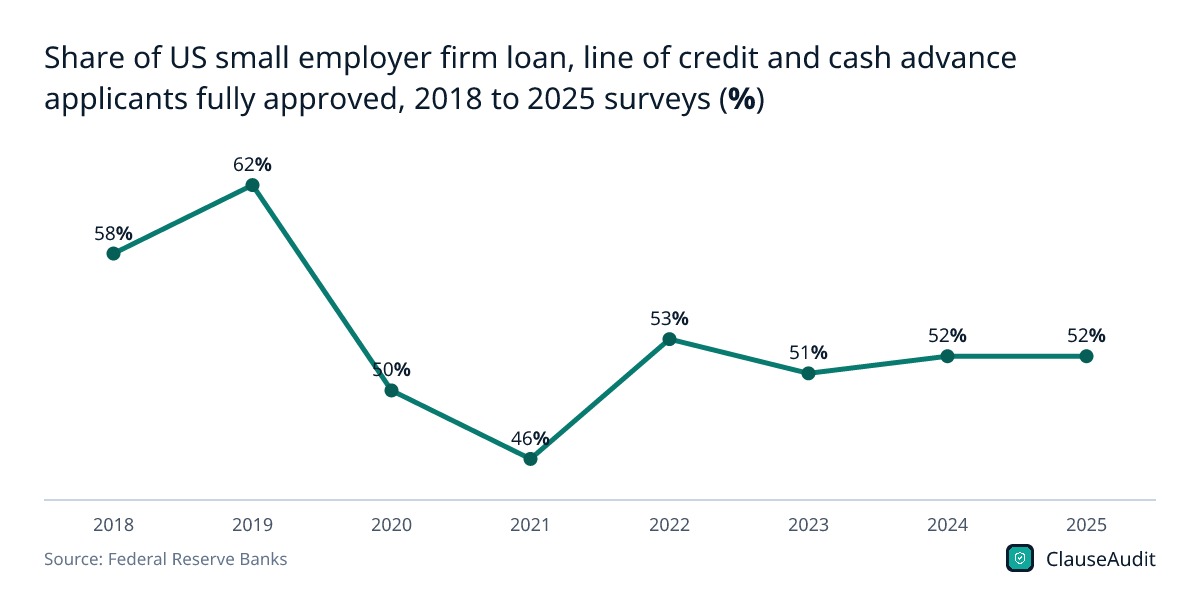
- 52% of US small employer firms that applied for a loan, line of credit or cash advance were fully approved, unchanged from the prior survey and below prepandemic levels. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 19% of loan, line of credit and cash advance applicants were denied outright, down from a 34% denial rate in the 2021 survey. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 80.8% of loan, line of credit and cash advance applicants were approved for at least some of the financing they sought (margin of error plus or minus 2.9 points). (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 42% of small business financing applicants received the full amount they sought, while 36% received some or most and 22% received nothing. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
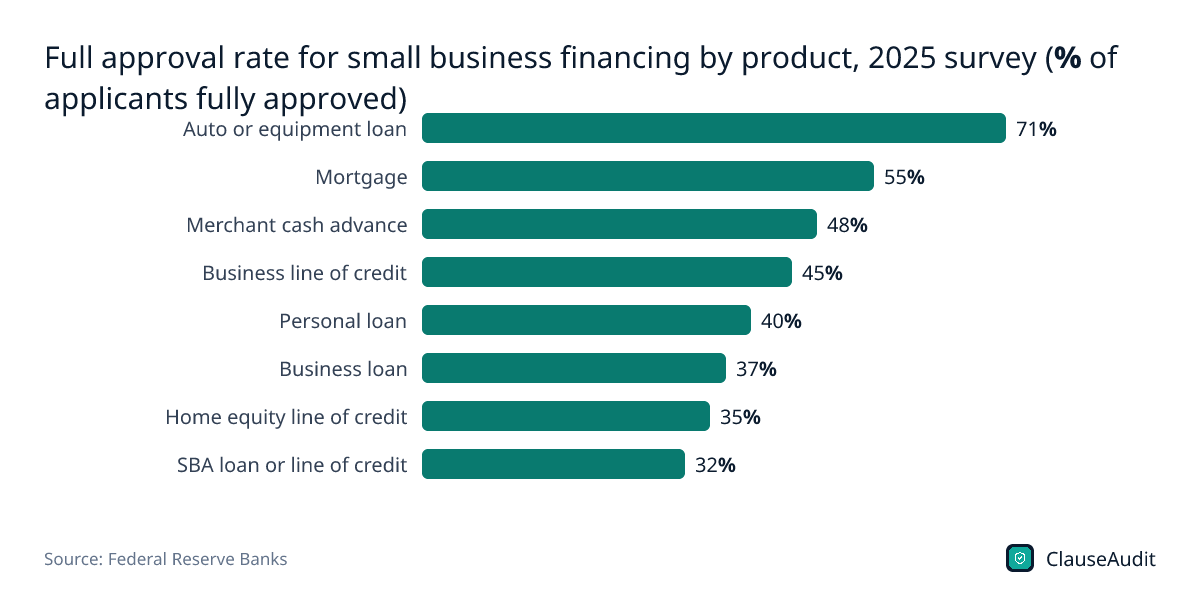
- 71% of auto or equipment loan applicants were fully approved, the highest full-approval rate of any financing product in the survey. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 40% of SBA loan or line of credit applicants were denied, the highest denial rate of any product; only 32% were fully approved. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 76% of applicants with more than $10 million in annual revenue were fully approved, versus 37% of applicants with revenue under $100,000. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 63% of applicants from firms 21 or more years old were fully approved, compared with 48% of firms aged 0 to 5 years. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 46% of applicants not approved for at least some financing said lender requirements were too strict, the most common reason given for credit denial. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 37% of applicants not approved for at least some financing were told they already carried too much debt, the second most common denial reason. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 69% of US banks surveyed said borrower financials were the most common reason for denying a small business loan in the second quarter of 2026. (Federal Reserve Bank of Kansas City, Small Business Lending Survey, Q2 2026, Q2 2026)
- 97% of Canadian small businesses (1 to 99 employees) that requested debt financing in 2025 were approved, up from 89% in 2024. (Innovation, Science and Economic Development Canada, Small Business Credit Condition Trends, 2015-2025, 2025)
Figure 2: Share of US small employer firm loan, line of credit and cash advance applicants fully approved, 2018 to 2025 surveys (%)
Chart data
| Label | Value (%) |
|---|---|
| 2018 | 58% |
| 2019 | 62% |
| 2020 | 50% |
| 2021 | 46% |
| 2022 | 53% |
| 2023 | 51% |
| 2024 | 52% |
| 2025 | 52% |
Bank vs Online Lender vs CDFI Small Business Lending Statistics
Where a business applies shapes its odds and its costs. These numbers compare large banks, small banks, online lenders, credit unions and CDFIs.
- 41% of small employer firms that sought a loan, credit line or cash advance applied at a large bank, the most common lender type. (Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey), 2025 survey (pub. March 2026))
- 29% of loan, credit line and cash advance applicants sought financing at online fintech lenders in the 2025 survey, up from 17% in 2020. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
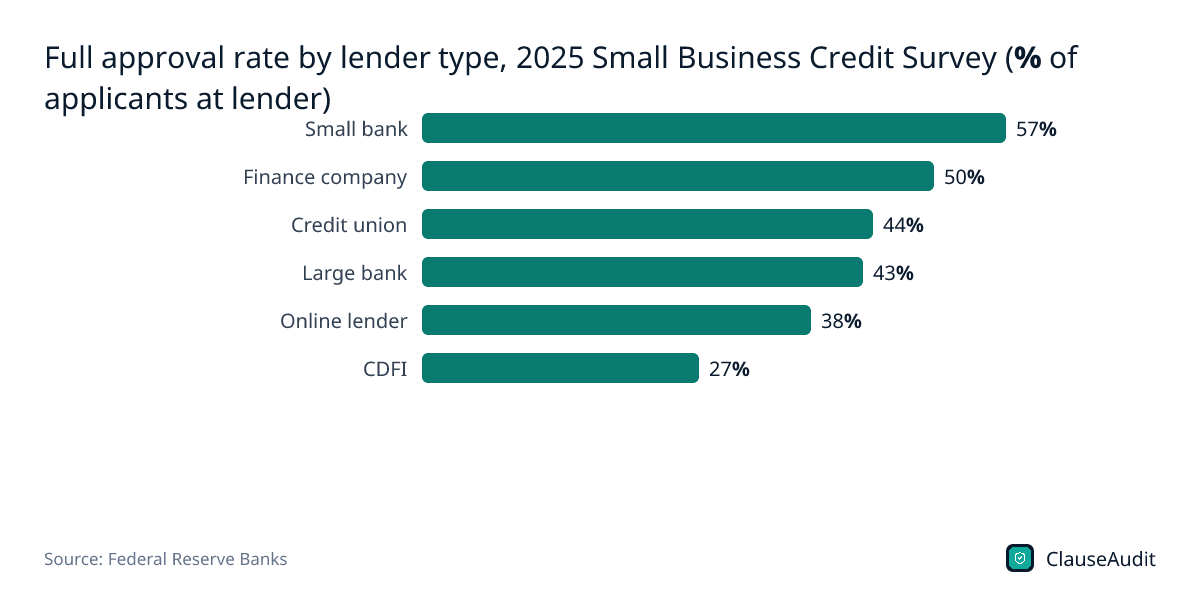
- 57% of applicants at small banks were fully approved, the highest full approval rate of any lender type. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 34% of applicants at community development financial institutions (CDFIs) were denied, and only 27% were fully approved. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 61% of large bank applicants and 62% of small bank applicants chose their lender because of an existing relationship. (Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey), 2025 survey (pub. March 2026))
- 49% of medium- and high-credit-risk applicants applied at online lenders, versus 19% of low-credit-risk applicants, in the 2025 survey. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 76% of approved credit union applicants were satisfied with their lender, compared with 35% of approved online lender applicants. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 64% of applicants with under $1 million in revenue were at least partially approved at large banks, versus 81% of applicants with more revenue. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 1,281 CDFIs were certified by the U.S. Treasury's CDFI Fund as of September 17, 2026, including 561 loan funds and 367 credit unions. (CDFI Fund, U.S. Department of the Treasury, List of Certified CDFIs as of September 17, 2026, September 2026)
- $201.7 billion in commercial loans were held by federally insured credit unions in 2026 Q2, up 10.1% over the year. (National Credit Union Administration, Quarterly Credit Union Data Summary, 2026 Q2, 2026 Q2)
- 9.1 million small business loans worth $276.6 billion were originated or purchased by banks reporting under the Community Reinvestment Act in 2024. (Office of the Comptroller of the Currency, Table 1. Small loans to businesses and farms, 2016-2024 (FFIEC CRA data fact sheet, News Release 2025-107), 2024 (released Nov 2025))
- About 25% of US bank small business loans were held by community banks at year-end 2019, versus their 15% share of all bank loans (FDIC, 2020). (Federal Deposit Insurance Corporation, The Importance of Community Banks in Paycheck Protection Program Lending (FDIC Quarterly, Vol. 14, No. 4), Year-end 2019 (pub. 2020))
- Nearly 85% of loans backed by Treasury's State Small Business Credit Initiative through 2024 went to businesses with fewer than 10 full-time employees. (U.S. Department of the Treasury, State Small Business Credit Initiative (SSBCI) 2024 Annual Report, Through 2024 (pub. Aug 2026))
- 7% of loan, line of credit and cash advance applicants applied at a CDFI in the 2025 survey; about 66% of CDFI applicants got at least some financing. (Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey), 2025 survey (pub. March 2026))
- 71% of CDFIs reported increased demand over 2024 in the Federal Reserve's 2025 CDFI Survey of 446 respondents. (Federal Reserve Bank of Richmond, 2025 Federal Reserve CDFI Survey Key Findings Report, 2024 (survey fielded April to June 2025))
- 80% of CDFIs active in small business lending expected loan demand to increase, while 40% of loan funds ranked lending capital as their biggest issue. (Federal Reserve Bank of Richmond, 2025 Federal Reserve CDFI Survey Key Findings Report, 2025 survey)
- Nearly $10 billion is the size of Treasury's State Small Business Credit Initiative, which aims to catalyze up to $10 of private investment per $1 of capital funding. (U.S. Department of the Treasury, State Small Business Credit Initiative (SSBCI), Program total)
Figure 3: Full approval rate by lender type, 2025 Small Business Credit Survey (% of applicants at lender)
Chart data
| Label | Value |
|---|---|
| Small bank | 57% |
| Finance company | 50% |
| Credit union | 44% |
| Large bank | 43% |
| Online lender | 38% |
| CDFI | 27% |
SBA Loan Statistics: 7(a), 504 and Microloan Data
The SBA guaranteed $145.6 billion in outstanding small business loan principal at the end of FY2025. This section covers 7(a) and 504 volume, average loan sizes, microloan terms and program limits.
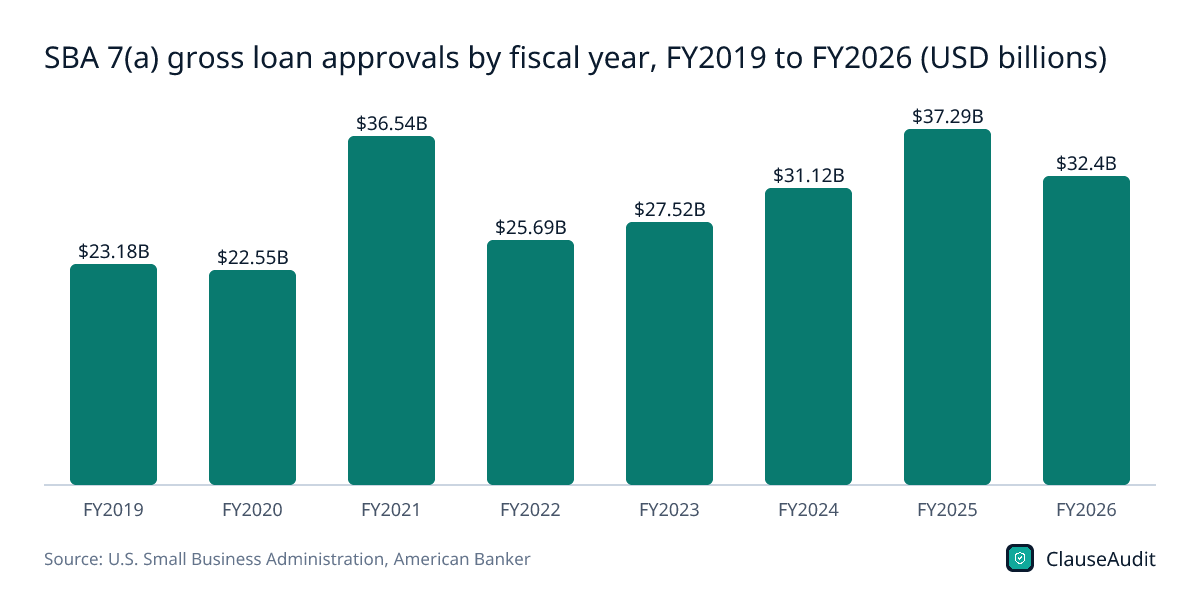
- 56,130 SBA 7(a) loans worth $32.4 billion were approved in fiscal 2026, ended September 30, double-digit declines in both count and dollars from FY2025. (American Banker, SBA starts new fiscal year with even tighter credit box, FY2026)
- $7.1 billion in SBA 504 loans was approved in fiscal 2026, a 9% drop in dollar volume from the prior year. (American Banker, SBA starts new fiscal year with even tighter credit box, FY2026)
- $45.09 billion in SBA 7(a) and 504 loans was approved across 84,840 loans in FY2025, per SBA final activity data; SBA's September 30 release had announced 84,400 loans for $44.8 billion. (U.S. Small Business Administration, 7(a) and 504 Monthly and Yearly Activity Report (Yearly sheet), FY2025)
- 78,078 SBA 7(a) loans were approved in FY2025 for $37.29 billion in gross approvals, up from 70,242 loans in FY2024. (U.S. Small Business Administration, 7(a) and 504 Monthly and Yearly Activity Report (Yearly sheet), FY2025)
- $27.46 billion was the SBA-guaranteed portion of FY2025 7(a) approvals, up from $22.84 billion in FY2024. (U.S. Small Business Administration, 7(a) and 504 Monthly and Yearly Activity Report (Yearly sheet), FY2025)
- 6,762 SBA 504 loans were approved in FY2025, worth $7.80 billion in total. (U.S. Small Business Administration, 7(a) and 504 Monthly and Yearly Activity Report (Yearly sheet), FY2025)
- 8,900 SBA-backed loans worth $5.6 billion went to startups between January 2025 and the end of FY2025, alongside 3,500-plus loans to manufacturers. (U.S. Small Business Administration, Trump SBA Delivers Record Capital to Small Businesses in FY25 (News Release 25-83), January to September 2025)
- 93% of SBA 7(a) loans in FY2025 were made by members of NAGGL, the 7(a) lender trade association. (National Association of Government Guaranteed Lenders, NAGGL: The Voice of 7(a) Lending, FY2025)
- About $477,600 was the average SBA 7(a) loan approved in FY2025, up from about $443,100 in FY2024, calculated from SBA gross approval counts and dollars. (U.S. Small Business Administration, 7(a) and 504 Monthly and Yearly Activity Report (Yearly sheet), FY2025)
- $5 million is the maximum Standard 7(a) loan, with an SBA guarantee of up to 75% and a 5 to 10 business day SBA turnaround. (U.S. Small Business Administration, Types of 7(a) loans, 2026)
- 85% is the maximum SBA guarantee on 7(a) small loans of up to $150,000, falling to 75% above that; 7(a) small loans are capped at $350,000. (U.S. Small Business Administration, Types of 7(a) loans, 2026)
- 20% of small business loan, line of credit and cash advance applicants applied for an SBA loan or line of credit in the 2025 survey. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- $35.5 billion is the FY2026 enacted 7(a) loan authorization for any industry, up from $35.0 billion in FY2025; the 504 limit stayed at $16.5 billion. (Congressional Research Service (via EveryCRSReport), Small Business Administration (SBA) Funding: Overview and Recent Trends (R43846), FY2026)
- Nearly 45,000 SBA 7(a) and 504 loans worth over $23 billion were approved between January 20 and July 30, 2025, an 11% year-over-year rise in loans. (U.S. Small Business Administration, SBA Celebrates 72 Years of Service to America's Small Businesses (News release 25-67), Jan 20 to Jul 30, 2025)
- About $13,000 is the average SBA microloan; the program lends up to $50,000 with a maximum repayment term of seven years. (U.S. Small Business Administration, Microloans, Current program terms)
- 25 years is the longest maturity available on an SBA 504 loan, which also comes in 10- and 20-year terms for fixed assets. (U.S. Small Business Administration, 504 loans, Current program terms)
Figure 4: SBA 7(a) gross loan approvals by fiscal year, FY2019 to FY2026 (USD billions)
Chart data
| Label | Value (USD billions) |
|---|---|
| FY2019 | $23.18B |
| FY2020 | $22.55B |
| FY2021 | $36.54B |
| FY2022 | $25.69B |
| FY2023 | $27.52B |
| FY2024 | $31.12B |
| FY2025 | $37.29B |
| FY2026 | $32.4B |
Small Business Debt Statistics
Most small employer firms carry some debt, and much of it is backed by the owner personally. These figures cover how much firms owe and how they secure it.
- 69.6% of US small employer firms carried outstanding business debt at the time of the survey, including loans from friends and family. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
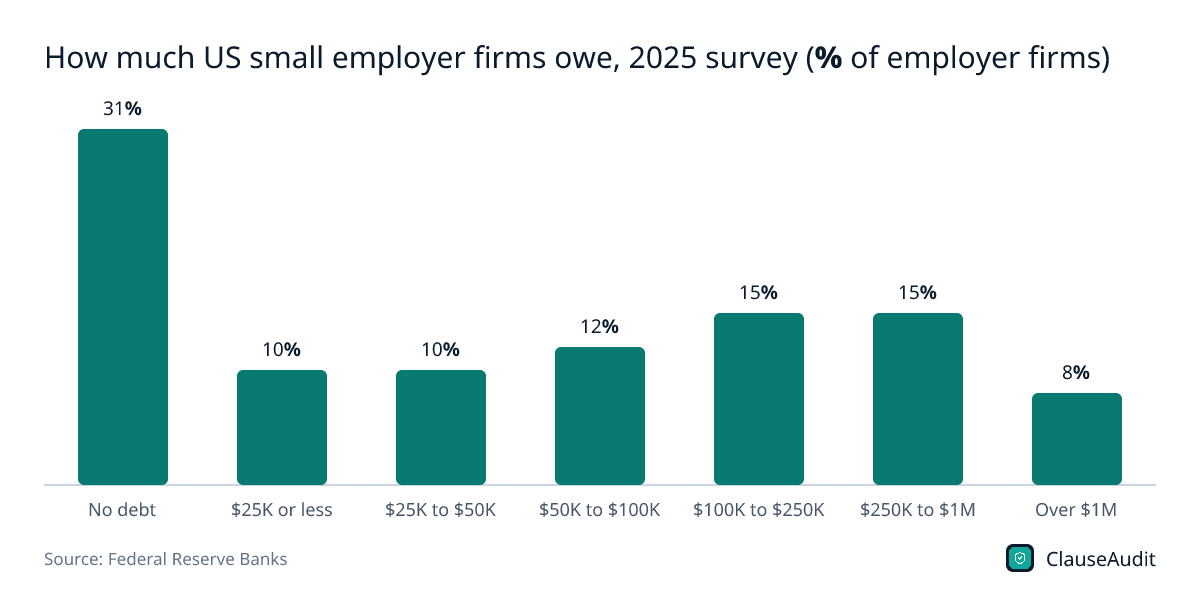
- 31% of small employer firms held no outstanding debt, up from 21% in the 2020 survey and back to prepandemic levels. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 37% of small employer firms owed more than $100,000, while 63% held $100,000 or less, including firms with no debt. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 59% of small employer firms with debt secured it with the owner’s personal guarantee, more than used business assets (51%). (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 38% of indebted small employer firms pledged the owner’s personal assets as collateral, up from 31% in 2019. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 86% of small employer firms use financing on a regular basis, most commonly credit cards and loans. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 62% of small employer firms regularly use or carry a balance on a credit card, the most common financing product, ahead of loans (44%). (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 33% of small employer firms said making payments on debt or interest rates was a financial challenge in the prior 12 months. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 24% of small employer firms facing financial challenges made a late payment or did not pay; 36% took on more debt in response. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 64% of US nonemployer firms relied on owners’ personal funds to handle financial challenges, compared with 54% of employer firms. (Federal Reserve Banks, Small Business Credit Survey: 2026 Chartbook on Nonemployer Firms (2025 survey), 2025 survey (pub. July 2026))
- $145.6 billion in outstanding small business loan principal was guaranteed by the SBA at the end of FY2025, up $6.1 billion during the year. (U.S. Small Business Administration, Agency Financial Report, Fiscal Year 2025, FY2025)
- 72% of US small businesses said they were comfortable with their current cash flow in the Q3 2026 Small Business Index. (U.S. Chamber of Commerce, Q3 2026 Small Business Index, Q3 2026)
- $23.97 trillion in debt securities and loans was owed by US nonfinancial businesses in Q2 2026, according to the Federal Reserve's Financial Accounts. (Board of Governors of the Federal Reserve System (Financial Accounts Z.1) via FRED, Nonfinancial Business; Debt Securities and Loans; Liability, Level (TBSDODNS), Q2 2026)
- 14% of New Jersey small employer firms used home equity loans or lines of credit, versus 2% in Pennsylvania, per the Philadelphia Fed's Third District SBCS insights. (Federal Reserve Bank of Philadelphia, Small Business Credit Survey: 2026 Insights into the Third District Region, 2025 survey (pub. August 2026))
Figure 5: How much US small employer firms owe, 2025 survey (% of employer firms)
Chart data
| Label | Value (% of employer firms) |
|---|---|
| No debt | 31% |
| $25K or less | 10% |
| $25K to $50K | 10% |
| $50K to $100K | 12% |
| $100K to $250K | 15% |
| $250K to $1M | 15% |
| Over $1M | 8% |
Small Business Loan Interest Rate and Borrowing Cost Statistics
Many small business lines of credit and SBA loans are priced as a margin over the prime rate, which moves with Federal Reserve policy. This section covers benchmark rates, rates owners reported paying, SBA rate caps and the cost of online and cash advance products.
- 7.00% was the bank prime loan rate on October 15, 2026, the benchmark many small business lines of credit and SBA loans float over. (Board of Governors of the Federal Reserve System, H.15 Selected Interest Rates (Daily), October 15, 2026)
- 1/4 point rate increase by the Federal Reserve on September 16, 2026 lifted the federal funds target range to 3.75% to 4%. (Board of Governors of the Federal Reserve System, Federal Reserve issues FOMC statement, September 16, 2026)
- 8.00% was the monthly average prime rate in October 2024; it fell to 6.75% from January to August 2026 before rising to 6.87% in September. (Federal Reserve Bank of St. Louis (FRED), from Federal Reserve H.15, Bank Prime Loan Rate (MPRIME), monthly, Oct 2024 to Sept 2026)
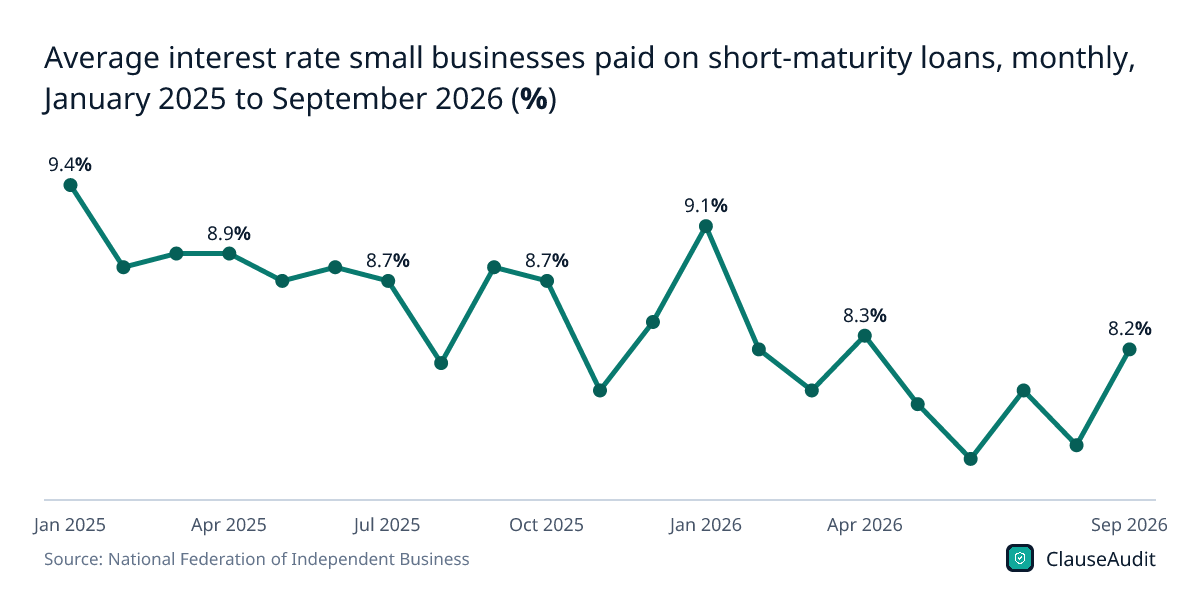
- 8.2% was the average interest rate small business owners paid on short-maturity loans in September 2026, up 0.7 points from August. (National Federation of Independent Business, NFIB Small Business Economic Trends, September 2026, September 2026)
- net 8% of owners reported paying a higher interest rate on their most recent loan in September 2026, the highest reading since June 2025. (National Federation of Independent Business, NFIB Small Business Economic Trends, September 2026, September 2026)
- 3% of small business owners named financing and interest rates as their top business problem in September 2026, unchanged from August. (National Federation of Independent Business, NFIB Small Business Economic Trends, September 2026, September 2026)
- base rate +6.5% is the most an SBA 7(a) working capital pilot lender can charge on loans of $50,000 or less. (U.S. Small Business Administration, 7(a) loans, 2026)
- base rate +3.0% is the rate cap for SBA 7(a) working capital pilot loans of $350,001 and more, the tightest of the four size tiers. (U.S. Small Business Administration, 7(a) loans, 2026)
- 6.7% was the variable rate on new small business term loans at rural banks in Q2 2026, the lowest term loan rate in the Kansas City Fed survey. (Federal Reserve Bank of Kansas City, Small Business Lending Survey, Q2 2026, Q2 2026)
- 60% of small businesses that borrowed from online lenders said actual borrowing costs were higher than expected; only 4% found them lower. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 61% of online lender applicants cited high interest rates as a challenge, versus 28% at large banks and 30% at small banks. (Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey), 2025 survey (pub. March 2026))
- Up to 820 percent was the top annual interest rate New York's Attorney General said Yellowstone Capital's merchant cash advances effectively charged; a $1.065 billion judgment followed. (New York State Office of the Attorney General, Attorney General James Announces $1 Billion Settlement with Predatory Lender, January 2025)
- $549,000 in a third round of FTC refunds went out in 3,759 checks to small businesses overcharged by merchant cash advance firm Yellowstone Capital. (Federal Trade Commission, Yellowstone Capital Refunds, June 2026)
Figure 6: Average interest rate small businesses paid on short-maturity loans, monthly, January 2025 to September 2026 (%)
Chart data
| Label | Value (%) |
|---|---|
| Jan 2025 | 9.4% |
| Feb 2025 | 8.8% |
| Mar 2025 | 8.9% |
| Apr 2025 | 8.9% |
| May 2025 | 8.7% |
| Jun 2025 | 8.8% |
| Jul 2025 | 8.7% |
| Aug 2025 | 8.1% |
| Sep 2025 | 8.8% |
| Oct 2025 | 8.7% |
| Nov 2025 | 7.9% |
| Dec 2025 | 8.4% |
| Jan 2026 | 9.1% |
| Feb 2026 | 8.2% |
| Mar 2026 | 7.9% |
| Apr 2026 | 8.3% |
| May 2026 | 7.8% |
| Jun 2026 | 7.4% |
| Jul 2026 | 7.9% |
| Aug 2026 | 7.5% |
| Sep 2026 | 8.2% |
Bank Small Business Lending Volume and Credit Conditions Statistics
Bank surveys show how much credit is flowing and whether lenders are loosening or tightening. These figures come mainly from the Kansas City Fed, the Federal Reserve's loan officer survey and the NFIB.
- 8.5% year-over-year rise in total new small business loan balances was reported by banks in the Kansas City Fed's Q2 2026 lending survey. (Federal Reserve Bank of Kansas City, Small Business Lending Survey, Q2 2026, Q2 2026)
- 2.9% year-over-year growth in outstanding small business loans was reported by surveyed banks in Q2 2026. (Federal Reserve Bank of Kansas City, Small Business Lending Survey, Q2 2026, Q2 2026)
- $66 billion+ in small business loans was reported by the 146 banks responding to the Kansas City Fed Small Business Lending Survey for Q2 2026. (Federal Reserve Bank of Kansas City, Small Business Lending Survey, Q2 2026, Q2 2026)
- 8% of Kansas City Fed survey banks, on net, reported tightening small business credit standards in Q2 2026. (Federal Reserve Bank of Kansas City, Small Business Lending Survey, Q2 2026, Q2 2026)
- 11% of surveyed banks, on net, said small business credit line usage increased in Q2 2026, up from 5% the previous quarter. (Federal Reserve Bank of Kansas City, Small Business Lending Survey, Q2 2026, Q2 2026)
- 90.9% of US banks left C&I lending standards for small firms (annual sales under $50 million) basically unchanged in the July 2026 Senior Loan Officer Survey. (Board of Governors of the Federal Reserve System, Senior Loan Officer Opinion Survey on Bank Lending Practices, July 2026, Table 1 (domestic banks), July 2026 survey)
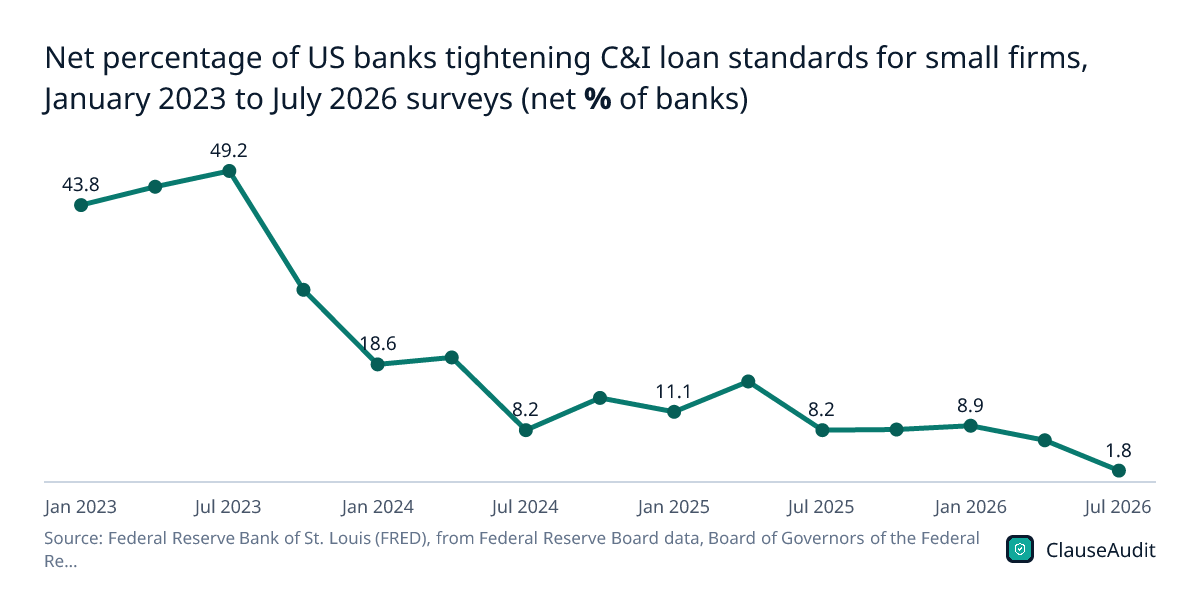
- 1.8 was the net percentage of US banks tightening C&I loan standards for small firms in the July 2026 survey, down from 8.2 a year earlier. (Federal Reserve Bank of St. Louis (FRED), from Federal Reserve Board data, Net Percentage of Domestic Banks Tightening Standards for Commercial and Industrial Loans to Small Firms (DRTSCIS), July 2026 survey)
- 9.1% of banks reported moderately stronger C&I loan demand from small firms in the July 2026 survey, against 5.5% reporting moderately weaker demand. (Board of Governors of the Federal Reserve System, Senior Loan Officer Opinion Survey on Bank Lending Practices, July 2026, Table 1 (domestic banks), July 2026 survey)
- 22% of small business owners reported borrowing regularly in September 2026, down 3 points from August and below the 34% historical average. (National Federation of Independent Business, NFIB Small Business Economic Trends, September 2026, September 2026)
- Net 3% of small business owners said their last loan was harder to obtain than previous attempts in September 2026, unchanged from August. (National Federation of Independent Business, NFIB Small Business Economic Trends, September 2026, September 2026)
- Net -3% was the net share of small business owners expecting easier credit conditions in September 2026, meaning more owners expect credit to get harder than easier. (National Federation of Independent Business, NFIB Small Business Economic Trends, September 2026, September 2026)
- Three in ten US banks could approve a small, simple business loan within one business day in the FDIC's 2022 Small Business Lending Survey; three in four within five days. (Federal Deposit Insurance Corporation, FDIC Issues 2024 Small Business Lending Survey Report (press release), 2022 survey (pub. October 2024))
- 1,000 loans a year is the new origination threshold, up from 100, for lenders covered by the CFPB's revised Section 1071 small business lending data rule issued May 2026. (Consumer Financial Protection Bureau, Fair Lending Report of the Consumer Financial Protection Bureau for 2025, May 2026 rule)
- $2.96 trillion in commercial and industrial loans were held by all US commercial banks in September 2026, seasonally adjusted, the loan category that includes most small business credit lines. (Board of Governors of the Federal Reserve System via FRED, Federal Reserve Bank of St. Louis, Commercial and Industrial Loans, All Commercial Banks (BUSLOANS), September 2026)
- Net 3.6% of US banks reported stronger demand for commercial and industrial loans from small firms in the Q3 2026 senior loan officer survey. (Board of Governors of the Federal Reserve System via FRED, Federal Reserve Bank of St. Louis, Net Percentage of Domestic Banks Reporting Stronger Demand for C&I Loans From Small Firms (DRSDCIS), Q3 2026)
- Net 16.1% of US banks reported stronger C&I loan demand from large and middle-market firms in Q3 2026, well above the net 3.6% for small firms. (Board of Governors of the Federal Reserve System via FRED, Federal Reserve Bank of St. Louis, Net Percentage of Domestic Banks Reporting Stronger Demand for C&I Loans From Large and Middle-Market Firms (DRSDCILM), Q3 2026)
- Net 0.0% of US banks tightened C&I lending standards for large and middle-market firms in Q3 2026, meaning as many eased as tightened. (Board of Governors of the Federal Reserve System via FRED, Federal Reserve Bank of St. Louis, Net Percentage of Domestic Banks Tightening Standards for C&I Loans to Large and Middle-Market Firms (DRTSCILM), Q3 2026)
- January 1, 2028 is the extended compliance date for the CFPB's Section 1071 small business lending data rule, under a final rule issued May 1, 2026. (Consumer Financial Protection Bureau, Small business lending rule (Section 1071), May 2026 rule)
Figure 7: Net percentage of US banks tightening C&I loan standards for small firms, January 2023 to July 2026 surveys (net % of banks)
Chart data
| Label | Value (net % of banks) |
|---|---|
| Jan 2023 | 43.8 |
| Apr 2023 | 46.7 |
| Jul 2023 | 49.2 |
| Oct 2023 | 30.4 |
| Jan 2024 | 18.6 |
| Apr 2024 | 19.7 |
| Jul 2024 | 8.2 |
| Oct 2024 | 13.3 |
| Jan 2025 | 11.1 |
| Apr 2025 | 15.9 |
| Jul 2025 | 8.2 |
| Oct 2025 | 8.3 |
| Jan 2026 | 8.9 |
| Apr 2026 | 6.6 |
| Jul 2026 | 1.8 |
Small Business Loan Default and Delinquency Statistics
Default and delinquency data shows how loans are performing after they close. This section covers bank C&I loans, SBA programs, COVID-19 EIDLs and small business bankruptcy filings.
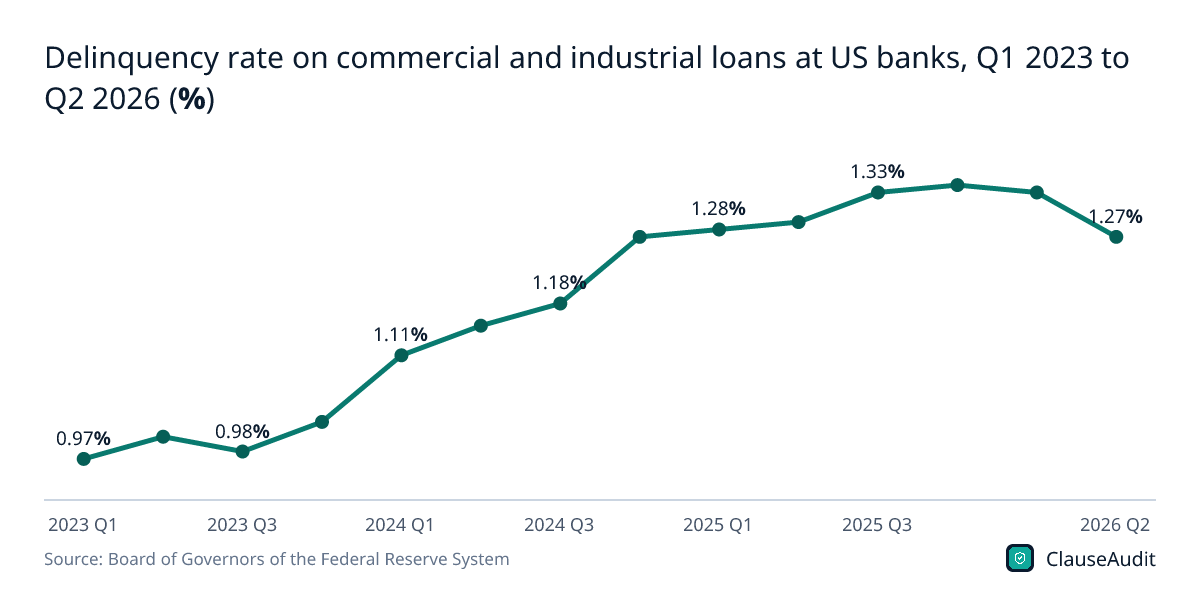
- 1.27% of commercial and industrial loans at US banks were delinquent in Q2 2026 (seasonally adjusted), down from 1.34% in Q4 2025. (Board of Governors of the Federal Reserve System, Charge-Off and Delinquency Rates on Loans and Leases at Commercial Banks: Delinquency Rates, All Banks, SA, Q2 2026)
- 0.58% net charge-off rate on commercial and industrial loans at US banks in Q2 2026, roughly double the 0.28% rate in Q1 2023. (Board of Governors of the Federal Reserve System, Charge-Off and Delinquency Rates on Loans and Leases at Commercial Banks: Charge-Off Rates, All Banks, SA, Q2 2026)
- 0.96% of commercial and industrial loans at FDIC-insured institutions were noncurrent (90+ days past due or nonaccrual) on June 30, 2026. (Federal Deposit Insurance Corporation, Quarterly Banking Profile, Second Quarter 2026, June 30, 2026)
- 1.15% average SBA 7(a) loan delinquency rate for FY2025 through July 2025, up from an FY2024 average of 0.88%. (U.S. Small Business Administration, Agency Financial Report, Fiscal Year 2025, FY2025 (through July 2025))
- 0.68% 12-month charge-off rate for the SBA 7(a) loan program as of July 2025, a level the SBA describes as very low. (U.S. Small Business Administration, Agency Financial Report, Fiscal Year 2025, July 2025)
- $5.2 billion in defaulted SBA-guaranteed loans was purchased from lenders in FY2025, which the SBA attributed to higher-than-expected defaults. (U.S. Small Business Administration, Agency Financial Report, Fiscal Year 2025, FY2025)
- 14.97% default rate on SBA 7(a) loans made by small business lending companies (FY2016 to FY2023 loans, as of March 31, 2025), versus 9.79% for other lenders. (U.S. Small Business Administration, Office of Inspector General, Small Business Lending Companies’ Performance in the 7(a) Loan Program and SBA’s Oversight (Report 26-14), As of March 31, 2025)
- 5.38% of 7(a) loans from small business lending companies defaulted within 18 months of disbursement, more than double the 2.62% early default rate for other lenders. (U.S. Small Business Administration, Office of Inspector General, Small Business Lending Companies’ Performance in the 7(a) Loan Program and SBA’s Oversight (Report 26-14), As of March 31, 2025)
- $47 billion in delinquent COVID-19 EIDLs, covering 369,588 loans with original balances over $25,000, had been charged off by the SBA as of December 18, 2024. (U.S. Small Business Administration, Office of Inspector General, SBA OIG Report 25-23: SBA's Collection Efforts on Delinquent COVID-19 EIDLs, December 18, 2024)
- Less than 1% of the original loan amounts on charged-off COVID-19 EIDLs was recovered during the SBA’s liquidation process, according to its inspector general. (U.S. Small Business Administration, Office of Inspector General, SBA OIG Report 25-23: SBA's Collection Efforts on Delinquent COVID-19 EIDLs, December 18, 2024)
- $14.7 billion in COVID-19 EIDLs (96,745 loans) were 90 or more days delinquent and still in collection as of December 18, 2024. (U.S. Small Business Administration, Office of Inspector General, SBA OIG Report 25-23: SBA's Collection Efforts on Delinquent COVID-19 EIDLs, December 18, 2024)
- 2,442 small business Subchapter V elections were filed in the first nine months of 2026, up 46% from 1,672 a year earlier. (Epiq (Epiq AACER data), Small Business Subchapter V Elections Increase 46% Compared to Last Year, January to September 2026)
- 6 basis points drop in defaults in July 2026 versus June, with 31 to 90 day delinquencies down 4 basis points, in Equifax small business lending trends. (Equifax, U.S. Economic Outlook: Main Street Holds Steady as Price Pressures Return (Equifax Main Street Lending Report), July 2026)
Figure 8: Delinquency rate on commercial and industrial loans at US banks, Q1 2023 to Q2 2026 (%)
Chart data
| Label | Value (%) |
|---|---|
| 2023 Q1 | 0.97% |
| 2023 Q2 | 1.00% |
| 2023 Q3 | 0.98% |
| 2023 Q4 | 1.02% |
| 2024 Q1 | 1.11% |
| 2024 Q2 | 1.15% |
| 2024 Q3 | 1.18% |
| 2024 Q4 | 1.27% |
| 2025 Q1 | 1.28% |
| 2025 Q2 | 1.29% |
| 2025 Q3 | 1.33% |
| 2025 Q4 | 1.34% |
| 2026 Q1 | 1.33% |
| 2026 Q2 | 1.27% |
Women-Owned and Minority-Owned Business Loan Statistics
Approval rates and loan amounts differ sharply by owner race, ethnicity and gender. These figures come mainly from the 2025 Small Business Credit Survey and Census Bureau ownership data.
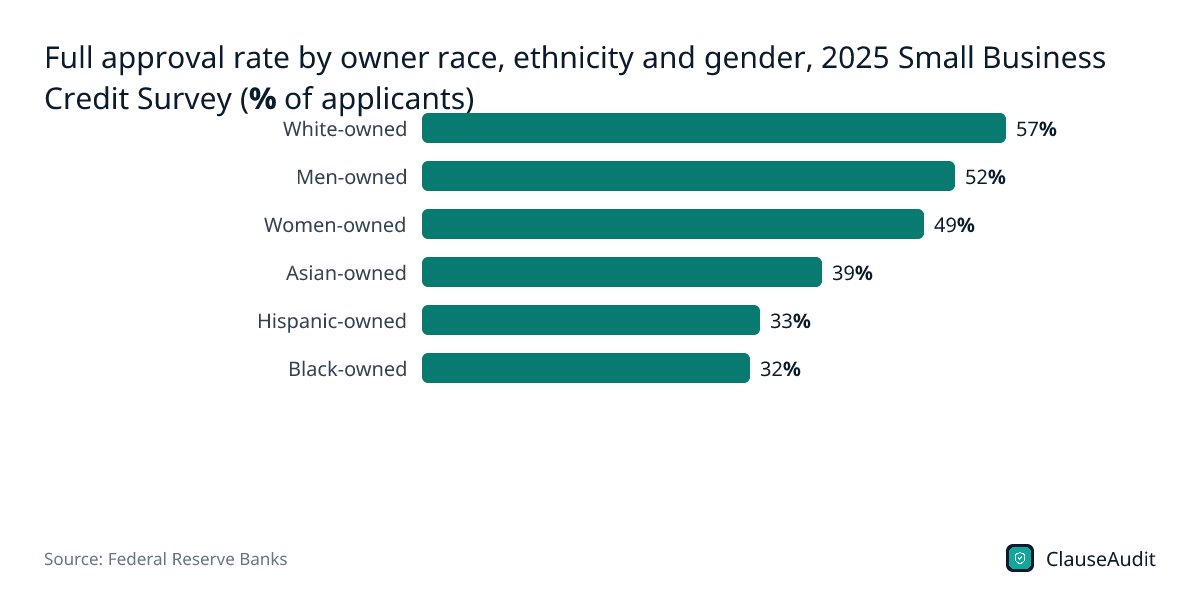
- 57% of applicants at firms owned by non-Hispanic white owners were fully approved for loans, credit lines or cash advances. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 32% of applicants at Black-owned employer firms were fully approved, the lowest rate of any owner race or ethnicity group shown. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 33% of applicants at Hispanic-owned employer firms were fully approved for a loan, line of credit or cash advance. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- 21% of Black-owned financing applicants received the full amount they sought, compared with 47% of white-owned applicants. (Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey), 2025 survey (pub. March 2026))
- 22% of Hispanic-owned financing applicants received all the financing they sought, and 31% received none. (Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey), 2025 survey (pub. March 2026))
- 49% of applicants at women-owned employer firms were fully approved, compared with 52% at men-owned firms. (Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey), 2025 survey (pub. March 2026))
- 43% of women-owned employer firms were operating at a loss at the end of 2024, versus 31% of men-owned firms. (Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey), End of 2024 (2025 survey))
- 41% of Black-owned employer firms applied for a loan, line of credit or cash advance, slightly above the 38% of white-owned firms. (Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey), 2025 survey (pub. March 2026))
- 1.4 million U.S. employer firms, or 22.9% of the total, were owned by women in 2023. (U.S. Census Bureau, Census Bureau Releases New Data on Business Owner Characteristics (Annual Business Survey, reference year 2023), 2023 (released Nov 2025))
- 201,000 Black-owned firms made up 3.4% of U.S. employer businesses in 2023, with $249.0 billion in receipts. (U.S. Census Bureau, Census Bureau Releases New Data on Business Owner Characteristics (Annual Business Survey, reference year 2023), 2023 (released Nov 2025))
- 496,000 Hispanic-owned firms accounted for 8.4% of U.S. employer businesses in 2023 and had $730.3 billion in receipts. (U.S. Census Bureau, Census Bureau Releases New Data on Business Owner Characteristics (Annual Business Survey, reference year 2023), 2023 (released Nov 2025))
- 620,000 women-owned small and medium businesses have been reached by the Women Entrepreneurs Finance Initiative (We-Fi), which is active in 81 countries. (We-Fi, Women Entrepreneurs Finance Initiative (We-Fi), Accessed October 2026)
- $55.4 billion was lent through 1.6 million loans to women-owned SMEs by IFC's financial institution clients in 2025. (International Finance Corporation (World Bank Group), MSME Finance, 2025)
Figure 9: Full approval rate by owner race, ethnicity and gender, 2025 Small Business Credit Survey (% of applicants)
Chart data
| Label | Value |
|---|---|
| White-owned | 57% |
| Men-owned | 52% |
| Women-owned | 49% |
| Asian-owned | 39% |
| Hispanic-owned | 33% |
| Black-owned | 32% |
Equipment Financing and Alternative Small Business Lending Statistics
Equipment finance, merchant cash advances and platform lenders now sit alongside bank loans. This section covers their volume, approval rates and cost.
- $11.8 billion in new equipment finance business volume was booked by surveyed ELFA member companies in August 2026, seasonally adjusted. (Equipment Leasing and Finance Association, ELFA CapEx Finance Index, August 2026, August 2026)
- $14.3 billion was July 2026 equipment finance new business volume, an all-time high for the ELFA CapEx Finance Index, before a 17.3% drop in August. (Equipment Leasing and Finance Association, ELFA CapEx Finance Index, August 2026, July 2026)
- 17.3% year-to-date rise in equipment finance new business volume through August 2026 compared with the same period of 2025. (Equipment Leasing and Finance Association, ELFA CapEx Finance Index, August 2026, January to August 2026)
- 75.4% was the average equipment finance credit approval rate in August 2026, down 2.0 points and the lowest since February 2025. (Equipment Leasing and Finance Association, ELFA CapEx Finance Index, August 2026, August 2026)
- 1.8% was the overall delinquency rate on equipment finance receivables in August 2026, down 0.4 points from a year earlier. (Equipment Leasing and Finance Association, ELFA CapEx Finance Index, August 2026, August 2026)
- $129 billion+ in 2026 new business volume is forecast for surveyed ELFA members, which would be the strongest reading in the CapEx Finance Index's history. (Equipment Leasing and Finance Association, U.S. Economic Outlook: Q3 2026, 2026 forecast (pub. August 2026))
- 48% of merchant cash advance applicants were fully approved in the 2025 survey, 40% were partially approved and 12% were denied. (Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey), 2025 survey (pub. March 2026))
- ~70% APR is the estimated APR of a 1.15 factor rate product with fees when $50,000 is repaid as $59,000 over six months, per a Federal Reserve study (2019). (Board of Governors of the Federal Reserve System, with the Federal Reserve Bank of Cleveland, Uncertain Terms: What Small Business Borrowers Find When Browsing Online Lender Websites (Barbara J. Lipman and Ann Marie Wiersch), December 2019)
- 74% of 468 small businesses with working capital loans surveyed by OnDeck and Ocrolus in December 2025 chose non-bank lenders over traditional banks. (Enova International (OnDeck), New Report: Small Businesses Enter 2026 with Sustained Confidence, Expanding Access to Capital and Growing Use of AI (OnDeck and Ocrolus), December 2025)
- $30 billion in global loan originations had been passed by PayPal's small business lending, across 1.4 million-plus loans and cash advances since 2013. (PayPal Holdings, Inc., PayPal Surpasses $30B in Global Small Business Lending, Since 2013 (as of March 2025))
- 7.3% was PayPal's annualized net charge-off rate on merchant loans and advances for the fourth quarter of 2025, per its 10-K, up from 5.3% a year earlier. (PayPal Holdings, Inc. via U.S. Securities and Exchange Commission, PayPal Holdings, Inc. Form 10-K for fiscal year 2025, Q4 2025)
- $1.3 billion in proceeds was reported by issuers in more than 3,800 Regulation Crowdfunding offerings between May 2016 and December 2024, according to SEC data. (U.S. Securities and Exchange Commission, SEC Publishes Data on Regulation Crowdfunding Offerings (Press Release 2025-79), May 2016 to December 2024)
- $9.1 million+ in FTC refunds went to small businesses after Yellowstone Capital allegedly kept withdrawing merchant cash advance payments once balances were repaid. (Federal Trade Commission, Yellowstone Capital Refunds, 2022 to 2024 refund rounds)
- $32.8 billion+ in principal has been loaned or advanced through Square Loans across more than 4.0 million loans and advances since the product launched in May 2014. (Block, Inc. (SEC filing), Block, Inc. Form 10-K for fiscal year 2025, Cumulative to Dec 31, 2025)
Figure 10: Full approval rate for small business financing by product, 2025 survey (% of applicants fully approved)
Chart data
| Label | Value |
|---|---|
| Auto or equipment loan | 71% |
| Mortgage | 55% |
| Merchant cash advance | 48% |
| Business line of credit | 45% |
| Personal loan | 40% |
| Business loan | 37% |
| Home equity line of credit | 35% |
| SBA loan or line of credit | 32% |
India MSME Loan and Credit Statistics
India's micro, small and medium enterprises borrow through banks, government guarantee schemes and micro-loan programs. These figures cover credit volume, access and delinquency.
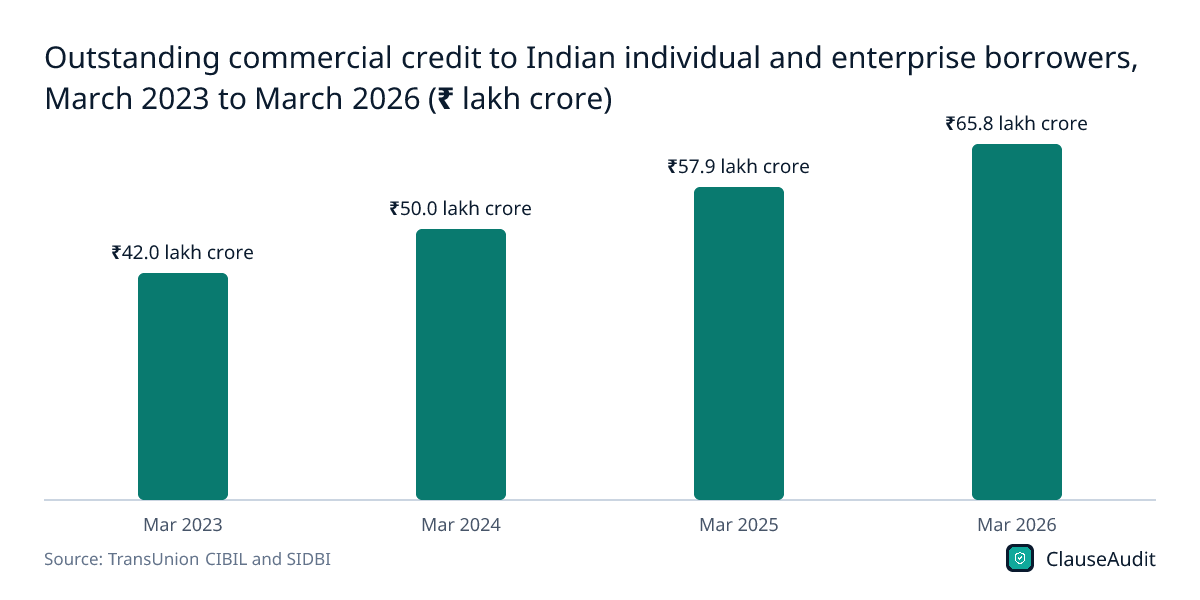
- ₹65.8 lakh crore in outstanding commercial credit to Indian individual and enterprise borrowers as of March 2026, according to TransUnion CIBIL and SIDBI. (TransUnion CIBIL and SIDBI, MSME Pulse Report, July 2026, March 2026)
- 41% of registered Indian MSMEs have ever accessed formal credit, leaving a large gap between registered and credit-active enterprises. (TransUnion CIBIL and SIDBI, MSME Pulse Report, July 2026, June 2026 (Udyam registrations))
- 1.8% of India’s commercial credit balances were 90+ days past due at the aggregate level in March 2026, which the report calls stable. (TransUnion CIBIL and SIDBI, MSME Pulse Report, July 2026, March 2026)
- 7.2% delinquency rate on unsecured business loans to Indian enterprises in March 2026, up 274 basis points since March 2023. (TransUnion CIBIL and SIDBI, MSME Pulse Report, July 2026, March 2026)
- 42% of MSME loan originations went to new-to-credit enterprises in FY2026, down from 52% in FY2023. (TransUnion CIBIL and SIDBI, MSME Pulse Report, July 2026, FY2026)
- ₹13.67 lakh crore in cumulative credit guarantees across 1.41 crore approvals had been issued by CGTMSE for collateral-free MSE loans as of March 31, 2026. (Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE), CGTMSE: Measuring Our Impact and Progress, March 31, 2026)
- 9,89,48,700 enterprises (about 98.9 million) were registered on India’s Udyam portal, including the Udyam Assist Platform, as of October 17, 2026. (Ministry of Micro, Small and Medium Enterprises, Government of India, Udyam Registration portal factsheet, October 17, 2026)
- 52.07 crore Mudra (PMMY) loan accounts worth Rs. 33.19 lakh crore had been sanctioned since the scheme’s April 2015 launch, as of February 28, 2025. (Department of Financial Services, Ministry of Finance, Government of India, Pradhan Mantri MUDRA Yojana (PMMY), February 28, 2025)
- 68 percent of all Mudra (PMMY) loan beneficiaries are women, according to the Ministry of Finance's 10-year review of the scheme. (Press Information Bureau, Ministry of Finance, Government of India, A Decade of Growth with PM Mudra Yojana, April 2025)
- ₹1.02 lakh average Mudra loan ticket size in FY2025, up from ₹38,000 in FY2016, as more borrowers moved to larger Kishor and Tarun loans. (Press Information Bureau, Ministry of Finance, Government of India, A Decade of Growth with PM Mudra Yojana, FY2025)
- 6,58,057 MSME guarantees worth Rs 2,02,646 crore had been issued under ECLGS 5.0 as of September 30, 2026. (Department of Financial Services, Ministry of Finance, Government of India, Emergency Credit Line Guarantee Scheme (ECLGS), September 30, 2026)
- 1,22,60,219 PM SVANidhi micro-loans for street vendors had been sanctioned and 1,20,44,836 disbursed, worth 19,711 crore rupees, per the scheme portal (updated October 13, 2026). (Ministry of Housing and Urban Affairs, Government of India, PM SVANidhi portal, October 2026 (portal updated October 13, 2026))
- 18.2% year-on-year growth in Indian bank credit to industry as of August 31, 2026, with micro and small industries sustaining steady expansion. (Reserve Bank of India, Sectoral Deployment of Bank Credit, August 2026, August 31, 2026)
Figure 11: Outstanding commercial credit to Indian individual and enterprise borrowers, March 2023 to March 2026 (₹ lakh crore)
Chart data
| Label | Value (₹ lakh crore) |
|---|---|
| Mar 2023 | ₹42.0 lakh crore |
| Mar 2024 | ₹50.0 lakh crore |
| Mar 2025 | ₹57.9 lakh crore |
| Mar 2026 | ₹65.8 lakh crore |
Global SME Finance Gap Statistics
Outside the US, small firms face similar gaps between what they need and what lenders provide. This section covers emerging markets, Europe, the UK, Canada and Australia.
- $5.7 trillion was the MSME finance gap across 119 emerging and developing economies in 2019, equal to 19% of GDP, up from $4.4 trillion in 2015. (SME Finance Forum, World Bank Group (IFC and World Bank), MSME Finance Gap Report (March 2025), 2019 data (pub. March 2025))
- 34 percent of the 2019 MSME finance gap in emerging economies belonged to women-owned businesses, a shortfall valued at $1.9 trillion. (SME Finance Forum, World Bank Group (IFC and World Bank), MSME Finance Gap Report (March 2025), 2019 data (pub. March 2025))
- $321.7 billion was lent through 6.9 million loans to SMEs by IFC's financial institution clients in 2025. (International Finance Corporation (World Bank Group), MSME Finance, 2025)
- 90% of businesses worldwide are MSMEs, which also provide 60% to 70% of employment and about 50% of global GDP. (United Nations, Micro-, Small and Medium-sized Enterprises Day, Cited 2026)
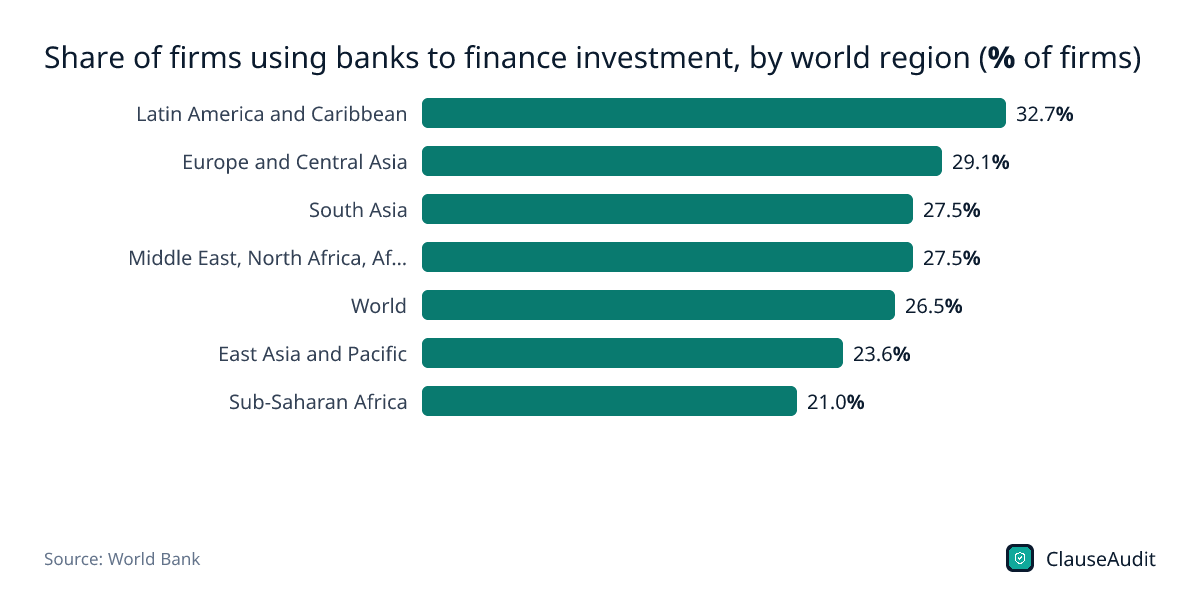
- 26.5% of firms worldwide use banks to finance investment, according to World Bank Enterprise Surveys aggregates for 2025. (World Bank, Firms using banks to finance investment (% of firms), IC.FRM.BNKS.ZS, World Bank Enterprise Surveys via WDI, Latest surveys (WDI 2025 series))
- net 43% of euro area SMEs reported higher bank loan interest rates in Q2 2026, up from a net 24% in the previous quarter. (European Central Bank, Survey on the Access to Finance of Enterprises in the euro area, second quarter of 2026, Q2 2026)
- 6.1% of firms in the European Union were finance-constrained in the EIB Investment Survey 2025, a slight decline from the previous year. (European Investment Bank, EIB Investment Survey 2025: European Union overview, 2025)
- 41% of SME trade finance applications were rejected, close to the 40% rate for large and mid-cap firms, as the global trade finance gap held at $2.5 trillion. (Asian Development Bank, Demand for Trade Finance to Rise Amid Supply Chain Realignment, ADB Report, 2025 (pub. Jan 2026))
- £5.35 billion in gross bank lending went to UK SMEs in the second quarter of 2026, a post-pandemic high and up 26% year on year. (UK Finance, Business Finance Review 2026 Q2, Q2 2026)
- 51% year-on-year rise in gross lending to the smallest UK businesses in Q1 2026, though UK Finance said this surge unwound in Q2. (UK Finance, SME lending hits post-pandemic high, Q1 2026)
- £2,453m in credit was extended to UK small businesses by online lender Funding Circle in 2025, up 29% from £1,899m in 2024. (Funding Circle Holdings plc, Full year 2025 results, 2025)
- 68.5% of Canadian SME debt financing came from chartered banks in 2023, versus 20.6% from credit unions and 2.2% from online alternative lenders. (Statistics Canada, Survey on Financing and Growth of Small and Medium Enterprises, 2023 (The Daily), 2023 (released Feb 2025))
- 5.8% was the average interest rate Canadian small businesses paid on debt financing in 2025, down 1.5 points from 7.3% in 2024. (Innovation, Science and Economic Development Canada, Small Business Credit Condition Trends, 2015-2025, 2025)
- 18% of Australian businesses sought debt or equity finance in 2024-25, up from 5% in 2021-22; banks were the most common source. (Australian Bureau of Statistics, Characteristics of Australian Business, 2024-25, 2024-25 (released June 2026))
Figure 12: Share of firms using banks to finance investment, by world region (% of firms)
Chart data
| Label | Value |
|---|---|
| Latin America and Caribbean | 32.7% |
| Europe and Central Asia | 29.1% |
| South Asia | 27.5% |
| Middle East, North Africa, Afghanistan and Pakistan | 27.5% |
| World | 26.5% |
| East Asia and Pacific | 23.6% |
| Sub-Saharan Africa | 21.0% |
What the numbers mean for small business owners
Getting approved is only half the result. In the 2025 Small Business Credit Survey, 52% of applicants for a loan, line of credit or cash advance were fully approved, but just 42% of financing applicants received the full amount they sought and 22% received nothing. Size and age count heavily: 76% of applicants with more than $10 million in revenue were fully approved, against 37% of those with revenue under $100,000, and firms aged 0 to 5 years were fully approved 48% of the time.
The product you apply for matters as much as the lender. Auto and equipment loans had a 71% full approval rate, while SBA loans or lines of credit had the highest denial rate at 40%. Among applicants who were not approved, 46% said lender requirements were too strict and 37% were told they already carried too much debt. Owners planning to borrow in the next year may want to pay down existing balances first, keep financial statements current, and match the product to the purpose, such as equipment financing for equipment rather than a general term loan.
Cost and personal risk often show up after the loan closes
Many owners are surprised by what they end up paying. Among businesses that borrowed from online lenders, 60% said actual costs were higher than expected and only 4% found them lower. A Federal Reserve study estimated that a 1.15 factor rate product with fees works out to about 70% APR when $50,000 is repaid as $59,000 over six months. At the extreme, New York's Attorney General said Yellowstone Capital's merchant cash advances effectively charged up to 820 percent a year.
The risk also reaches the owner's own finances. Of small employer firms with debt, 59% secured it with the owner's personal guarantee and 38% pledged personal assets as collateral, up from 31% in 2019. With 33% of firms naming debt payments or interest rates as a financial challenge, and the average short-term loan rate at 8.2% in September 2026, a guarantee can turn a slow quarter into a personal problem.
Before signing, convert any factor rate or fee schedule into an annual cost, ask whether the guarantee can be capped or limited to a set period, and confirm whether the lender can take payments directly from your bank account and what stops those withdrawals once the balance is paid.
Where to apply and what lenders are doing now
Bank credit conditions have loosened. The net share of banks tightening standards for small firms fell to 1.8 in the July 2026 senior loan officer survey, from 8.2 a year earlier, and 90.9% of banks left standards unchanged. Small banks gave the highest full approval rate at 57%, and about six in ten bank applicants chose their lender because of an existing relationship.
Online lenders are growing anyway: 29% of applicants sought financing from them in the 2025 survey, up from 17% in 2020, and 49% of medium- and high-risk applicants applied there. Satisfaction is lower, at 35% of approved online borrowers against 76% at credit unions. For most owners, a sensible order is a bank or credit union where you already have accounts, then an SBA lender or CDFI, with online and cash advance products compared on full cost rather than speed alone.
Check your loan or financing agreement before you sign
The figures on this page show that the terms of a small business loan often matter more than the approval itself: personal guarantees, collateral, variable rates and payment mechanics decide how much risk the owner carries. An automated review of your loan, credit line, equipment finance or cash advance agreement flags those clauses and explains them in plain English, so you know what to question before you sign.
- Personal guarantee scope, including whether it is unlimited, joint and several, or capped
- Collateral and blanket liens on business or personal assets
- The true annual cost behind any factor rate, origination fee or monthly fee
- Variable rate terms tied to prime and any rate floor or cap
- Prepayment penalties and early payoff discounts
- Default triggers, cross-default clauses and acceleration rights
- Automatic ACH or daily withdrawals and the reconciliation process
- Confession of judgment, venue and arbitration clauses
Frequently asked questions
What percentage of small business loan applications are approved?
In the Federal Reserve's 2025 Small Business Credit Survey, 52% of small employer firms that applied for a loan, line of credit or cash advance were fully approved, and 80.8% were approved for at least some of what they sought. About 19% were denied outright.
How many small businesses apply for loans?
38% of US small employer firms applied for a loan, line of credit or merchant cash advance in the 2025 survey, and 60% applied for some type of financing. Of firms that did not apply, 63% said they did not need it or already had enough financing.
How much did the SBA lend in FY2025?
The SBA approved $45.09 billion in 7(a) and 504 loans across 84,840 loans in FY2025. That included 78,078 7(a) loans worth $37.29 billion and 6,762 504 loans worth $7.80 billion. The average 7(a) loan was about $477,600.
What is the average interest rate on a small business loan?
Small business owners reported paying an average of 8.2% on short-maturity loans in September 2026, according to the NFIB. The bank prime rate was 7.00% on October 15, 2026, and many lines of credit and SBA loans are priced as a margin above it.
Is it easier to get a loan from a bank or an online lender?
Small banks had the highest full approval rate in the 2025 survey at 57%, compared with 43% at large banks and 38% at online lenders. Online lenders draw more higher-risk applicants, and 60% of their borrowers said costs were higher than expected.
How many small businesses personally guarantee their debt?
59% of small employer firms with debt secured it with the owner's personal guarantee in the 2025 survey, more than the 51% that used business assets. 38% pledged the owner's personal assets as collateral, up from 31% in 2019.
What is the SBA 7(a) loan default rate?
The average SBA 7(a) delinquency rate was 1.15% for FY2025 through July 2025, up from 0.88% in FY2024, and the 12-month charge-off rate was 0.68% as of July 2025. Among 7(a) loans made from FY2016 to FY2023, those from small business lending companies had defaulted at 14.97% as of March 31, 2025, versus 9.79% for other lenders.
Use this data
Every chart and card below is free to reuse under CC BY 4.0. Download what you need and link back to this page.
 Stat cards
 Key findings card
 Infographic
 Share of US small employer firms that applied for a loan, line of credit or cash advance, 2018 to 2025 surveys (%)
 SBA 7(a) gross loan approvals by fiscal year, FY2019 to FY2026 (USD billions)
 Net percentage of US banks tightening C&I loan standards for small firms, January 2023 to July 2026 surveys (net % of banks)
 Full approval rate for small business financing by product, 2025 survey (% of applicants fully approved)
 Share of US small employer firm loan, line of credit and cash advance applicants fully approved, 2018 to 2025 surveys (%)
 How much US small employer firms owe, 2025 survey (% of employer firms)
 Delinquency rate on commercial and industrial loans at US banks, Q1 2023 to Q2 2026 (%)
 Outstanding commercial credit to Indian individual and enterprise borrowers, March 2023 to March 2026 (₹ lakh crore)
 Full approval rate by lender type, 2025 Small Business Credit Survey (% of applicants at lender)
 Average interest rate small businesses paid on short-maturity loans, monthly, January 2025 to September 2026 (%)
 Full approval rate by owner race, ethnicity and gender, 2025 Small Business Credit Survey (% of applicants)
 Share of firms using banks to finance investment, by world region (% of firms)
Embed the infographic
Free to share on your site, blog or slides under CC BY 4.0. Please keep the credit link.
Sources and method
Every number on this page comes from the sources below, each opened and read on or before October 17, 2026. A second, independent review checked every figure against its source and corrected anything that did not match. Figures that could not be confirmed were left out.
- Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (findings from the 2025 survey) (March 2026)
- U.S. Census Bureau, Business Formation Statistics, September 2026 (Release CB26-163) (October 14, 2026)
- National Federation of Independent Business, NFIB Small Business Economic Trends, September 2026 (October 2026)
- Live Oak Bank, 2026 Small Business Insights (Barlow Research survey with Live Oak Bank) (Q1 2026)
- Enova International (OnDeck), New Report: Small Businesses Enter 2026 with Sustained Confidence, Expanding Access to Capital and Growing Use of AI (OnDeck and Ocrolus) (January 28, 2026)
- U.S. Small Business Administration, 7(a) and 504 Monthly and Yearly Activity Report (Yearly sheet) (Data as of September 30, 2025)
- U.S. Small Business Administration, Trump SBA Delivers Record Capital to Small Businesses in FY25 (News Release 25-83) (September 30, 2025)
- U.S. Small Business Administration, Types of 7(a) loans (Accessed October 2026)
- American Banker, SBA starts new fiscal year with even tighter credit box (October 9, 2026)
- National Association of Government Guaranteed Lenders, NAGGL: The Voice of 7(a) Lending (Accessed October 2026)
- Congressional Research Service (via EveryCRSReport), Small Business Administration (SBA) Funding: Overview and Recent Trends (R43846) (March 12, 2026)
- Federal Reserve Bank of Kansas City, Small Business Lending Survey, Q2 2026 (September 24, 2026)
- Board of Governors of the Federal Reserve System, Senior Loan Officer Opinion Survey on Bank Lending Practices, July 2026, Table 1 (domestic banks) (August 3, 2026)
- Federal Reserve Bank of St. Louis (FRED), from Federal Reserve Board data, Net Percentage of Domestic Banks Tightening Standards for Commercial and Industrial Loans to Small Firms (DRTSCIS) (Through July 2026 survey)
- Federal Deposit Insurance Corporation, FDIC Issues 2024 Small Business Lending Survey Report (press release) (October 2, 2024 (survey conducted 2022))
- Consumer Financial Protection Bureau, Fair Lending Report of the Consumer Financial Protection Bureau for 2025 (September 2026)
- Equipment Leasing and Finance Association, ELFA CapEx Finance Index, August 2026 (September 29, 2026)
- Equipment Leasing and Finance Association, U.S. Economic Outlook: Q3 2026 (August 19, 2026)
- PayPal Holdings, Inc., PayPal Surpasses $30B in Global Small Business Lending (March 26, 2025)
- PayPal Holdings, Inc. via U.S. Securities and Exchange Commission, PayPal Holdings, Inc. Form 10-K for fiscal year 2025 (February 2026)
- U.S. Securities and Exchange Commission, SEC Publishes Data on Regulation Crowdfunding Offerings (Press Release 2025-79) (May 28, 2025)
- Federal Trade Commission, Yellowstone Capital Refunds (June 2026)
- Federal Reserve Banks, Small Business Credit Survey: 2026 Chartbook on Nonemployer Firms (2025 survey) (July 7, 2026)
- Innovation, Science and Economic Development Canada, Small Business Credit Condition Trends, 2015-2025 (Date modified July 14, 2026)
- Board of Governors of the Federal Reserve System, Charge-Off and Delinquency Rates on Loans and Leases at Commercial Banks: Delinquency Rates, All Banks, SA (Last update August 25, 2026 (data through 2026:Q2))
- Board of Governors of the Federal Reserve System, Charge-Off and Delinquency Rates on Loans and Leases at Commercial Banks: Charge-Off Rates, All Banks, SA (Last update August 25, 2026 (data through 2026:Q2))
- Federal Deposit Insurance Corporation, Quarterly Banking Profile, Second Quarter 2026 (Second quarter 2026 (data as of June 30, 2026))
- U.S. Small Business Administration, Office of Inspector General, SBA OIG Report 25-23: SBA's Collection Efforts on Delinquent COVID-19 EIDLs (August 12, 2025)
- U.S. Small Business Administration, Agency Financial Report, Fiscal Year 2025 (FY2025 (posted February 2026))
- Epiq (Epiq AACER data), Small Business Subchapter V Elections Increase 46% Compared to Last Year (October 8, 2026)
- Equifax, U.S. Economic Outlook: Main Street Holds Steady as Price Pressures Return (Equifax Main Street Lending Report) (September 23, 2026)
- U.S. Chamber of Commerce, Q3 2026 Small Business Index (July 30, 2026)
- TransUnion CIBIL and SIDBI, MSME Pulse Report, July 2026 (July 2026)
- Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE), CGTMSE: Measuring Our Impact and Progress (Data as on March 31, 2026)
- Ministry of Micro, Small and Medium Enterprises, Government of India, Udyam Registration portal factsheet (Facts dated October 17, 2026)
- Department of Financial Services, Ministry of Finance, Government of India, Pradhan Mantri MUDRA Yojana (PMMY) (Progress as on February 28, 2025)
- Department of Financial Services, Ministry of Finance, Government of India, Emergency Credit Line Guarantee Scheme (ECLGS) (Data as on September 30, 2026)
- Ministry of Housing and Urban Affairs, Government of India, PM SVANidhi portal (Last updated October 13, 2026)
- Reserve Bank of India, Sectoral Deployment of Bank Credit, August 2026 (September 30, 2026)
- U.S. Small Business Administration, Office of Inspector General, Small Business Lending Companies’ Performance in the 7(a) Loan Program and SBA’s Oversight (Report 26-14) (September 17, 2026)
- Press Information Bureau, Ministry of Finance, Government of India, A Decade of Growth with PM Mudra Yojana (April 7, 2025)
- Federal Reserve Banks, 2026 Report on Employer Firms, data appendix (2025 Small Business Credit Survey) (Last updated March 3, 2026)
- National Credit Union Administration, Quarterly Credit Union Data Summary, 2026 Q2 (September 2026)
- CDFI Fund, U.S. Department of the Treasury, List of Certified CDFIs as of September 17, 2026 (September 17, 2026)
- Board of Governors of the Federal Reserve System, H.15 Selected Interest Rates (Daily) (October 16, 2026)
- Board of Governors of the Federal Reserve System, Federal Reserve issues FOMC statement (September 16, 2026)
- Federal Reserve Bank of St. Louis (FRED), from Federal Reserve H.15, Bank Prime Loan Rate (MPRIME), monthly (Data through September 2026)
- U.S. Small Business Administration, 7(a) loans (Accessed October 17, 2026)
- U.S. Census Bureau, Census Bureau Releases New Data on Business Owner Characteristics (Annual Business Survey, reference year 2023) (November 20, 2025)
- International Finance Corporation (World Bank Group), MSME Finance (Accessed October 17, 2026)
- We-Fi, Women Entrepreneurs Finance Initiative (We-Fi) (Accessed October 17, 2026)
- United Nations, Micro-, Small and Medium-sized Enterprises Day (Accessed October 17, 2026)
- World Bank, Firms using banks to finance investment (% of firms), IC.FRM.BNKS.ZS, World Bank Enterprise Surveys via WDI (Last updated October 8, 2026)
- European Central Bank, Survey on the Access to Finance of Enterprises in the euro area, second quarter of 2026 (Q2 2026 survey round (fieldwork 21 May to 26 June 2026))
- Office of the Comptroller of the Currency, Table 1. Small loans to businesses and farms, 2016-2024 (FFIEC CRA data fact sheet, News Release 2025-107) (November 13, 2025)
- U.S. Department of the Treasury, State Small Business Credit Initiative (SSBCI) 2024 Annual Report (August 20, 2026)
- New York State Office of the Attorney General, Attorney General James Announces $1 Billion Settlement with Predatory Lender (January 22, 2025)
- SME Finance Forum, World Bank Group (IFC and World Bank), MSME Finance Gap Report (March 2025) (March 3, 2025)
- European Investment Bank, EIB Investment Survey 2025: European Union overview (2025)
- Asian Development Bank, Demand for Trade Finance to Rise Amid Supply Chain Realignment, ADB Report (January 15, 2026)
- UK Finance, SME lending hits post-pandemic high (June 11, 2026)
- Funding Circle Holdings plc, Full year 2025 results (March 5, 2026)
- Statistics Canada, Survey on Financing and Growth of Small and Medium Enterprises, 2023 (The Daily) (February 20, 2025)
- Australian Bureau of Statistics, Characteristics of Australian Business, 2024-25 (June 25, 2026)
- Board of Governors of the Federal Reserve System via FRED, Federal Reserve Bank of St. Louis, Commercial and Industrial Loans, All Commercial Banks (BUSLOANS) (October 2026 (Sep 2026 observation))
- Board of Governors of the Federal Reserve System via FRED, Federal Reserve Bank of St. Louis, Net Percentage of Domestic Banks Reporting Stronger Demand for C&I Loans From Small Firms (DRSDCIS) (Q3 2026 observation)
- Board of Governors of the Federal Reserve System via FRED, Federal Reserve Bank of St. Louis, Net Percentage of Domestic Banks Tightening Standards for C&I Loans to Large and Middle-Market Firms (DRTSCILM) (Q3 2026 observation)
- Board of Governors of the Federal Reserve System via FRED, Federal Reserve Bank of St. Louis, Net Percentage of Domestic Banks Reporting Stronger Demand for C&I Loans From Large and Middle-Market Firms (DRSDCILM) (Q3 2026 observation)
- Board of Governors of the Federal Reserve System (Financial Accounts Z.1) via FRED, Nonfinancial Business; Debt Securities and Loans; Liability, Level (TBSDODNS) (Q2 2026 observation)
- Federal Reserve Bank of Philadelphia, Small Business Credit Survey: 2026 Insights into the Third District Region (August 12, 2026)
- Federal Reserve Bank of Dallas, Texas Business Outlook Surveys: Special Questions, October 2025 (October 27, 2025)
- Consumer Financial Protection Bureau, Small business lending rule (Section 1071) (Updated June 22, 2026)
- U.S. Department of the Treasury, State Small Business Credit Initiative (SSBCI) (Accessed October 2026)
- U.S. Small Business Administration, SBA Celebrates 72 Years of Service to America's Small Businesses (News release 25-67) (July 30, 2025)
- Block, Inc. (SEC filing), Block, Inc. Form 10-K for fiscal year 2025 (February 2026)
- Federal Reserve Bank of Richmond, 2025 Federal Reserve CDFI Survey Key Findings Report (September 19, 2025)
- U.S. Small Business Administration, Microloans (Accessed October 2026)
- U.S. Small Business Administration, 504 loans (Accessed October 2026)
- Board of Governors of the Federal Reserve System, with the Federal Reserve Bank of Cleveland, Uncertain Terms: What Small Business Borrowers Find When Browsing Online Lender Websites (Barbara J. Lipman and Ann Marie Wiersch) (December 2019)
- Federal Deposit Insurance Corporation, The Importance of Community Banks in Paycheck Protection Program Lending (FDIC Quarterly, Vol. 14, No. 4) (2020)
- UK Finance, Business Finance Review 2026 Q2 (September 2026)
Cite this page
ClauseAudit, “Small Business Loan and Financing Statistics 2026: 170 Numbers on Approvals, SBA Loans, Rates and Debt”, updated October 17, 2026, https://clauseaudit.com/data/small-business-loan-statistics. Free to reuse with a link back (CC BY 4.0).
This page summarises published data and law as checked on October 17, 2026. Figures are updated as new editions are released, and your own situation may differ. It is general information, not legal, tax or financial advice.