SBA Loan Default Rates by Franchise Brand, Computed From SBA 7(a) Data
By ClauseAudit Research · 6 sources ·
What is the SBA loan default rate by franchise?
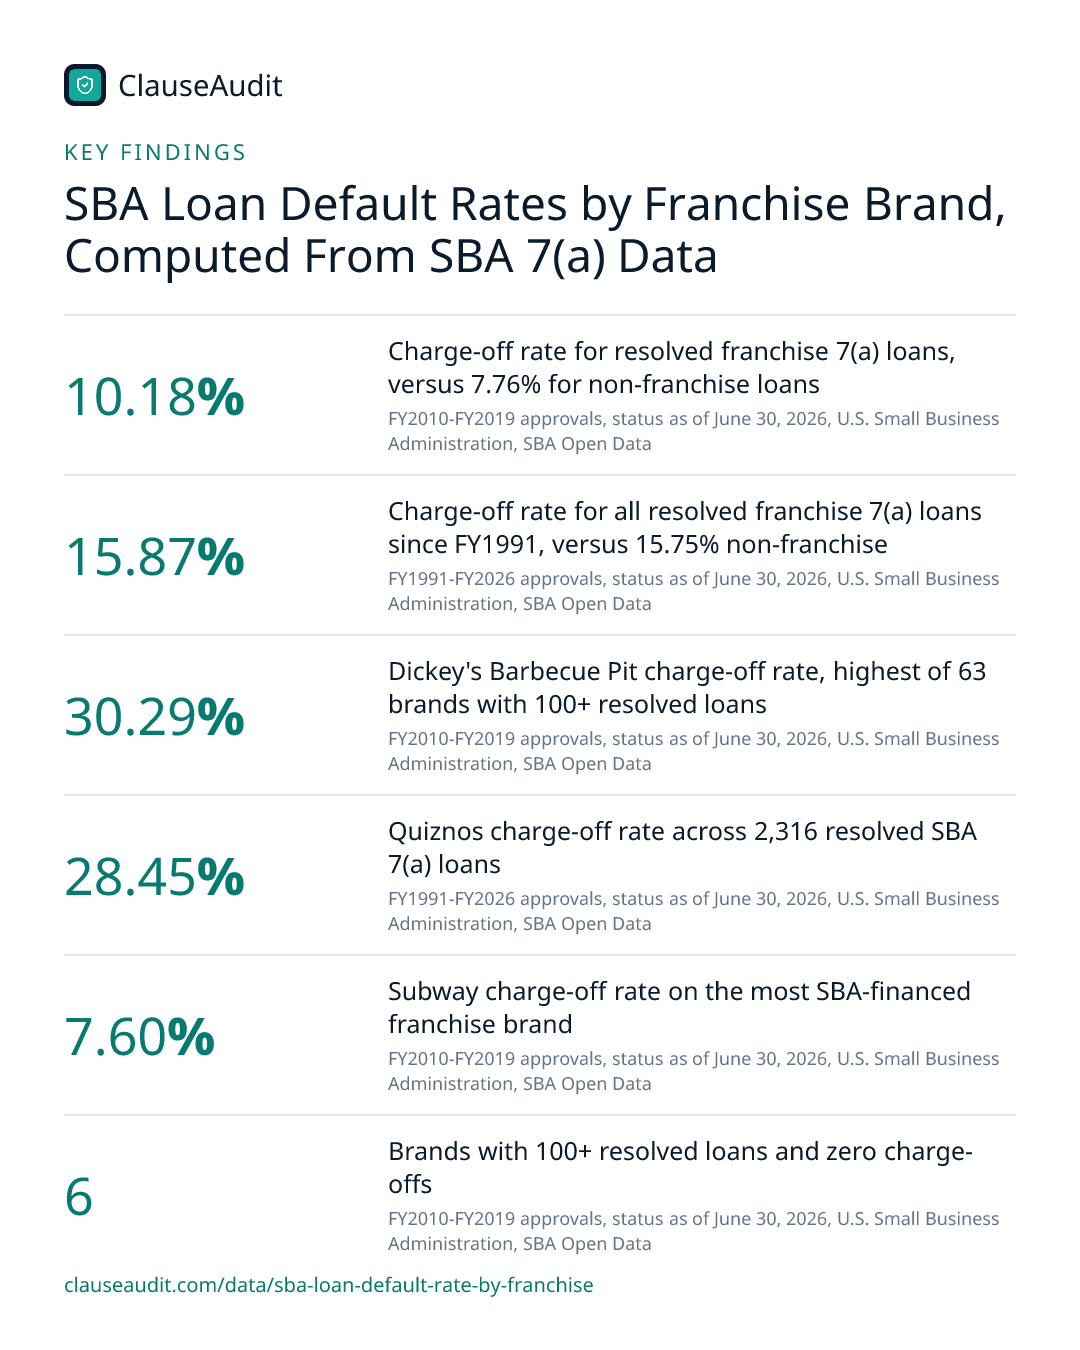
Franchise loans are not safer than independent ones. Among resolved SBA 7(a) loans approved FY2010-FY2019, 10.18% of franchise loans were charged off, versus 7.76% for non-franchise loans. The brand matters far more than the label: Dickey's Barbecue Pit hit 30.29%, while 6 brands with 100+ resolved loans had zero charge-offs.
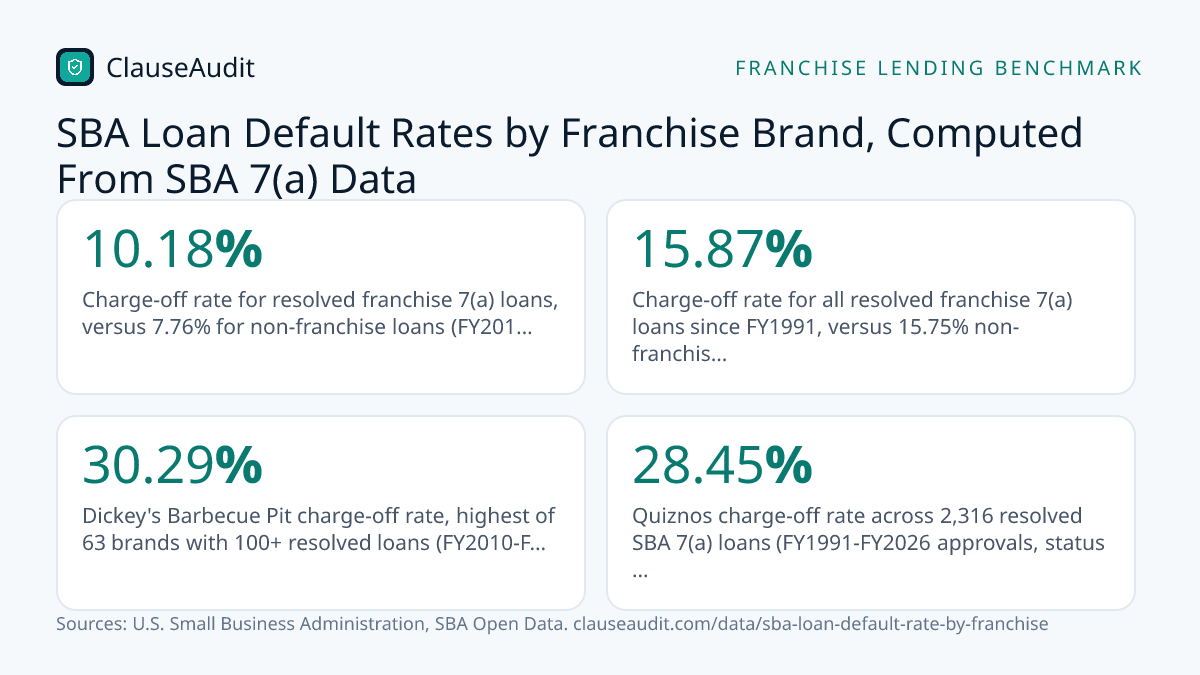
- Charge-off rate for resolved franchise 7(a) loans, versus 7.76% for non-franchise loans (FY2010-FY2019 approvals, status as of June 30, 2026, U.S. Small Business Administration, SBA Open Data)
- 10.18%
- Charge-off rate for all resolved franchise 7(a) loans since FY1991, versus 15.75% non-franchise (FY1991-FY2026 approvals, status as of June 30, 2026, U.S. Small Business Administration, SBA Open Data)
- 15.87%
- Dickey's Barbecue Pit charge-off rate, highest of 63 brands with 100+ resolved loans (FY2010-FY2019 approvals, status as of June 30, 2026, U.S. Small Business Administration, SBA Open Data)
- 30.29%
- Quiznos charge-off rate across 2,316 resolved SBA 7(a) loans (FY1991-FY2026 approvals, status as of June 30, 2026, U.S. Small Business Administration, SBA Open Data)
- 28.45%
- Subway charge-off rate on the most SBA-financed franchise brand (FY2010-FY2019 approvals, status as of June 30, 2026, U.S. Small Business Administration, SBA Open Data)
- 7.60%
- Brands with 100+ resolved loans and zero charge-offs (FY2010-FY2019 approvals, status as of June 30, 2026, U.S. Small Business Administration, SBA Open Data)
- 6
- Matco Tools charge-off rate, highest of 36 brands with 400+ resolved loans (FY1991-FY2026 approvals, status as of June 30, 2026, U.S. Small Business Administration, SBA Open Data)
- 34.72%
- Share of FY2025 SBA 7(a) loan approvals that went to franchise businesses (FY2025, U.S. Small Business Administration, SBA Open Data)
- 9.19%
Franchise sellers like to say you're buying a proven system. The SBA's own loan records let you test that claim brand by brand. We pulled every 7(a) loan in the SBA's public FOIA files, matched each one to its franchise code, and counted how many ended in a charge-off, meaning the loan was written off as a loss.
The short version: a franchise name on the loan application doesn't lower the odds of failure on its own. Some brands repaid almost every loan. Others lost close to a third. If you're about to borrow for a franchise, the brand-level rate tells you more than any brochure, and the contract tells you how much of that risk lands on you personally.
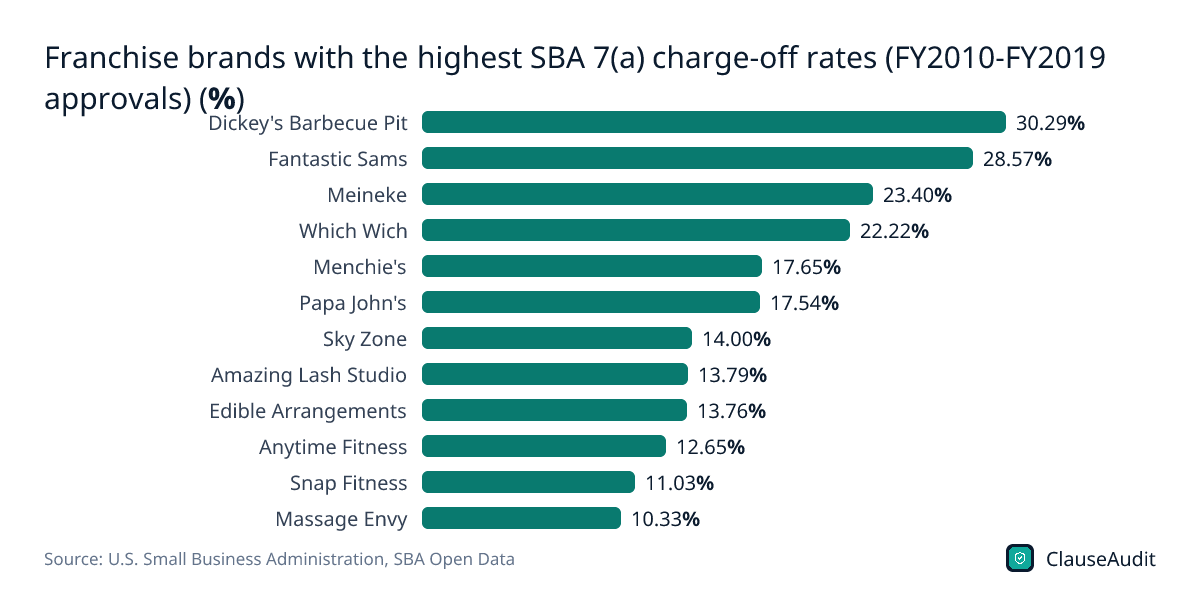
Franchise brands with the highest SBA 7(a) charge-off rates (FY2010-FY2019 approvals) (%)
Chart data
| Label | Value |
|---|---|
| Dickey's Barbecue Pit | 30.29% |
| Fantastic Sams | 28.57% |
| Meineke | 23.40% |
| Which Wich | 22.22% |
| Menchie's | 17.65% |
| Papa John's | 17.54% |
| Sky Zone | 14.00% |
| Amazing Lash Studio | 13.79% |
| Edible Arrangements | 13.76% |
| Anytime Fitness | 12.65% |
| Snap Fitness | 11.03% |
| Massage Envy | 10.33% |
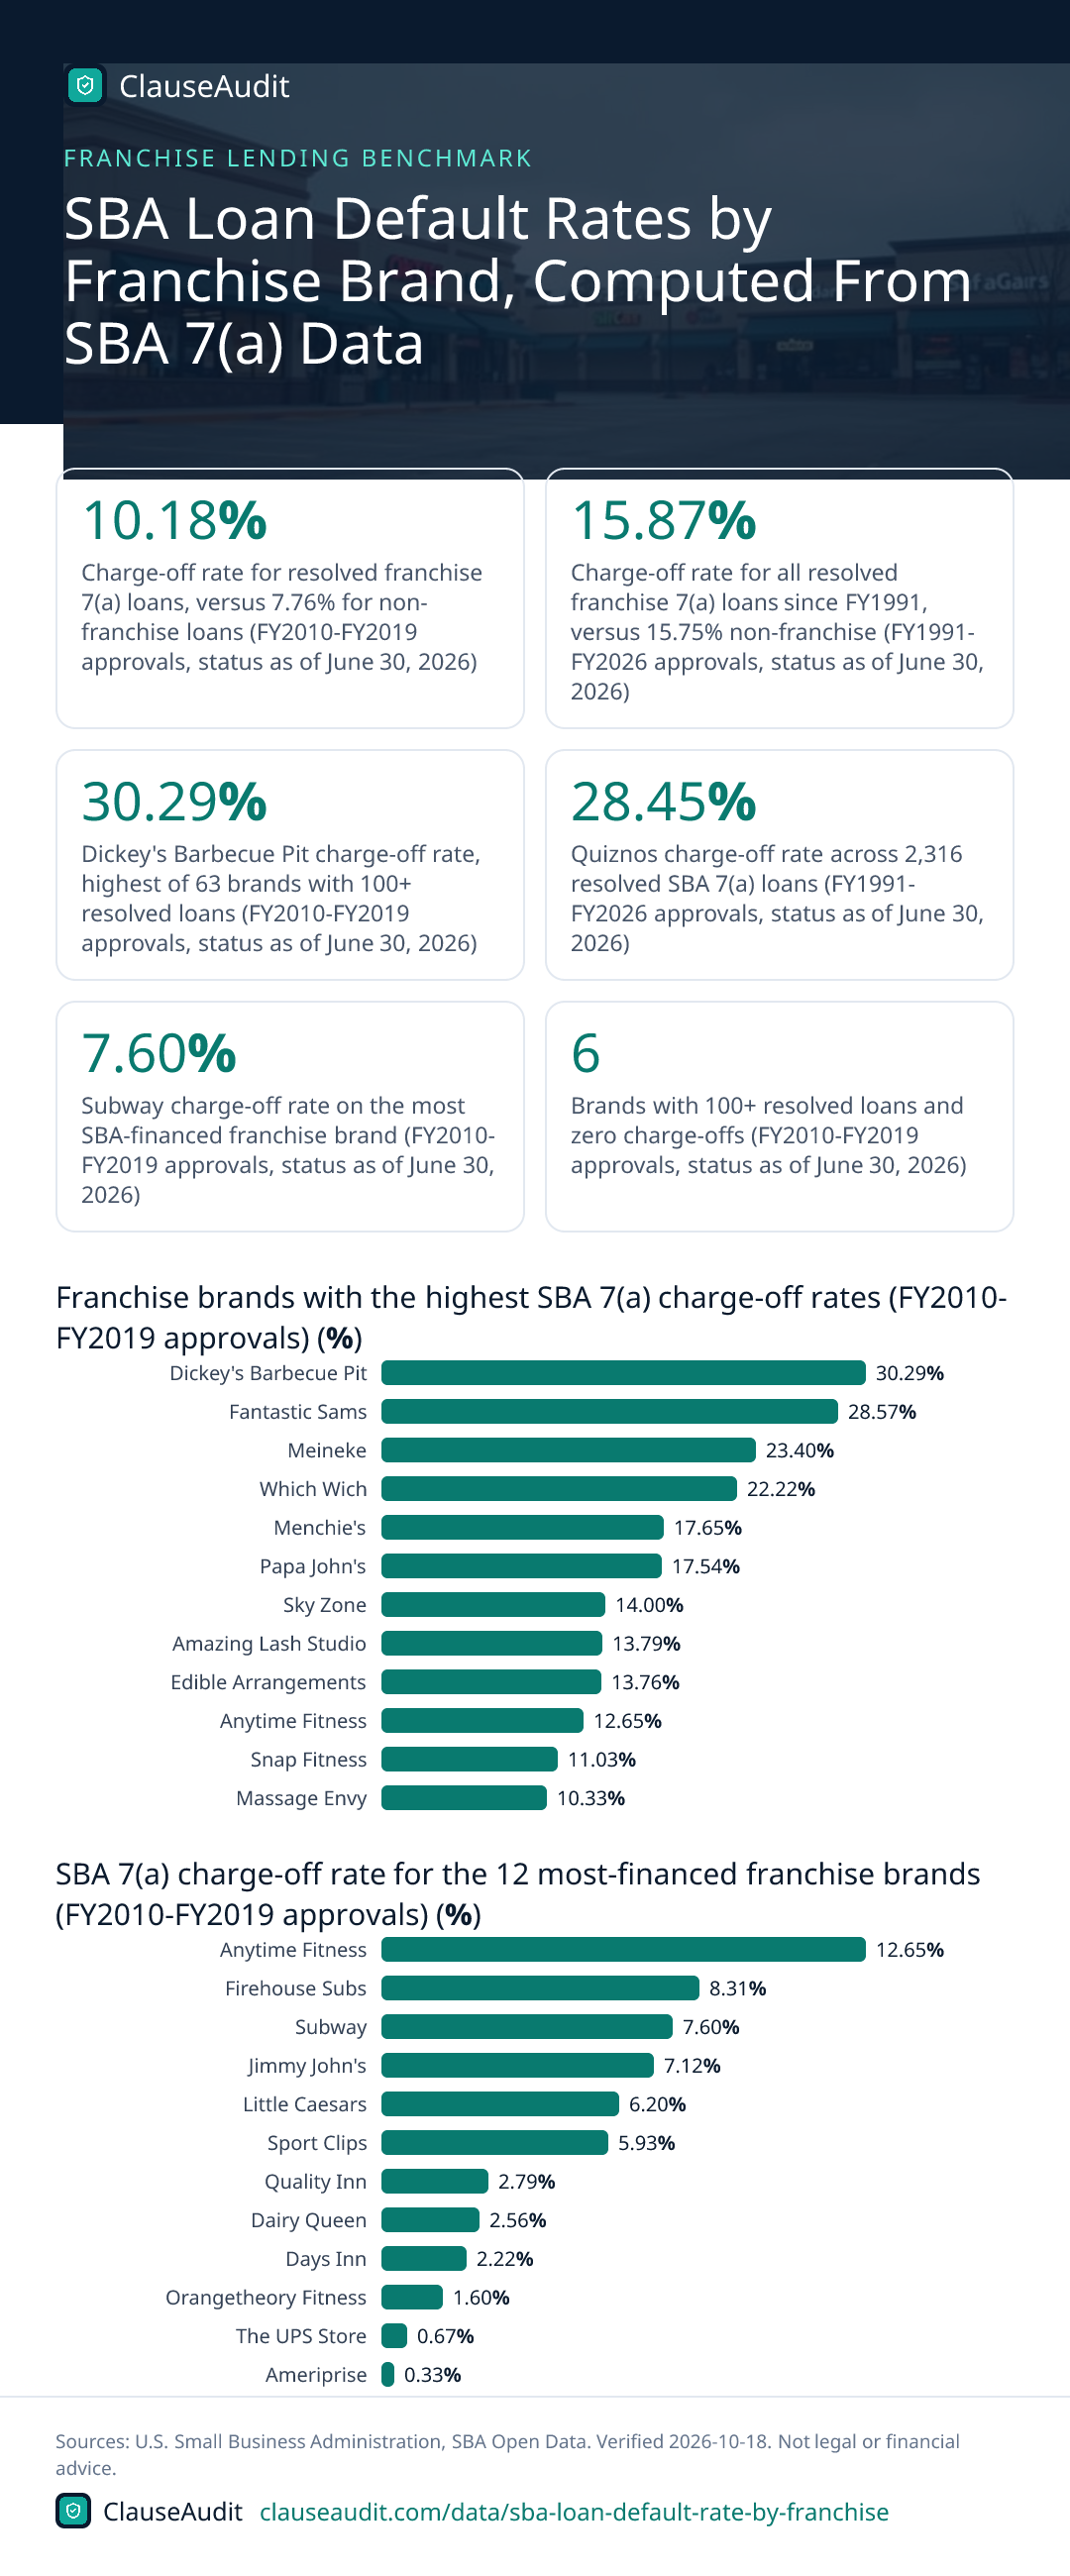
Dickey's Barbecue Pit leads at 30.29%, with Fantastic Sams close behind at 28.57%. These loans were all approved after the 2008-2009 recession, so that downturn doesn't explain them.
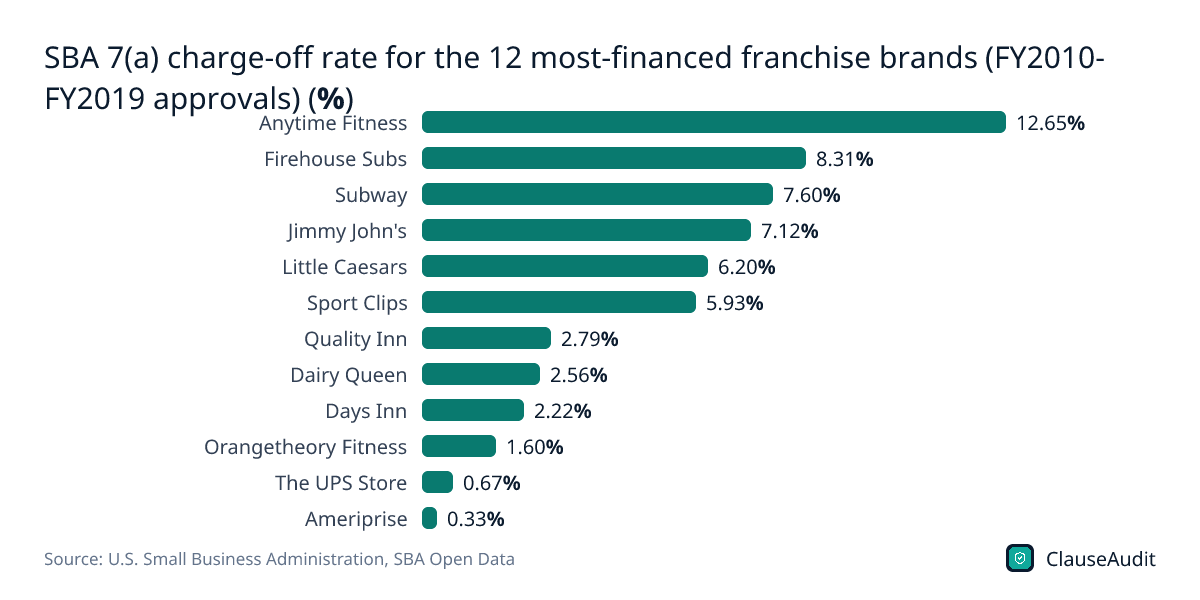
Download this chart (PNG)SBA 7(a) charge-off rate for the 12 most-financed franchise brands (FY2010-FY2019 approvals) (%)
Chart data
| Label | Value |
|---|---|
| Anytime Fitness | 12.65% |
| Firehouse Subs | 8.31% |
| Subway | 7.60% |
| Jimmy John's | 7.12% |
| Little Caesars | 6.20% |
| Sport Clips | 5.93% |
| Quality Inn | 2.79% |
| Dairy Queen | 2.56% |
| Days Inn | 2.22% |
| Orangetheory Fitness | 1.60% |
| The UPS Store | 0.67% |
| Ameriprise | 0.33% |
Even among the most popular brands the spread is wide: Anytime Fitness at 12.65% versus The UPS Store at 0.67%. Popularity with lenders is not the same as a track record of repayment.
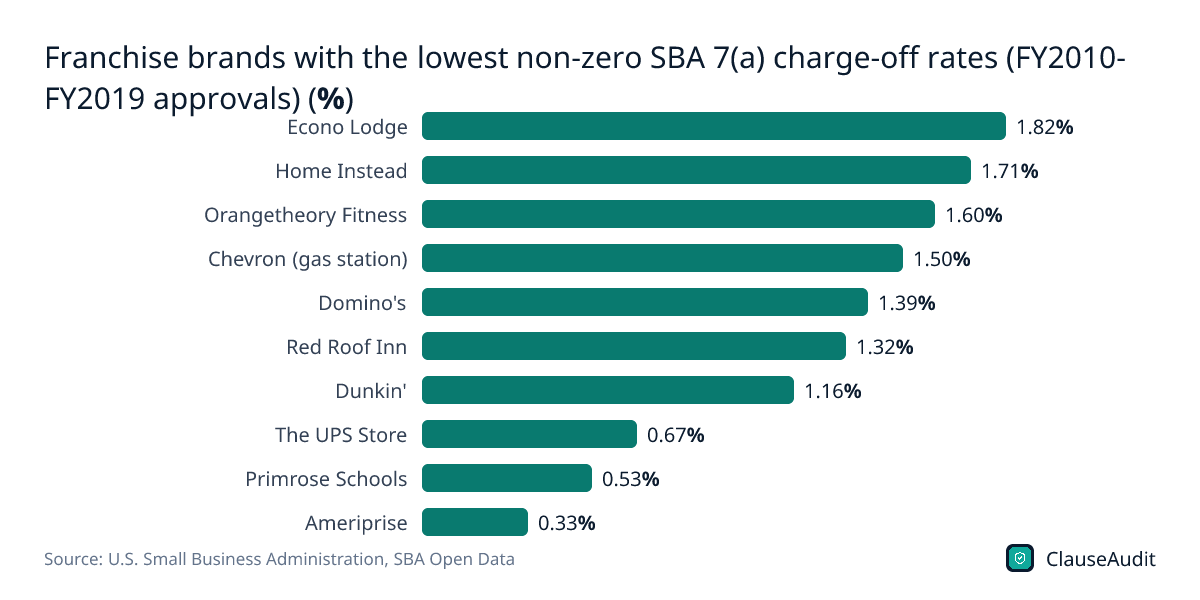
Download this chart (PNG)Franchise brands with the lowest non-zero SBA 7(a) charge-off rates (FY2010-FY2019 approvals) (%)
Chart data
| Label | Value |
|---|---|
| Econo Lodge | 1.82% |
| Home Instead | 1.71% |
| Orangetheory Fitness | 1.60% |
| Chevron (gas station) | 1.50% |
| Domino's | 1.39% |
| Red Roof Inn | 1.32% |
| Dunkin' | 1.16% |
| The UPS Store | 0.67% |
| Primrose Schools | 0.53% |
| Ameriprise | 0.33% |
Hotels, child care and service brands cluster at the low end, such as Primrose Schools at 0.53%. Several of these carry big loans: Primrose averaged $2.70 million and Red Roof Inn $2.01 million.
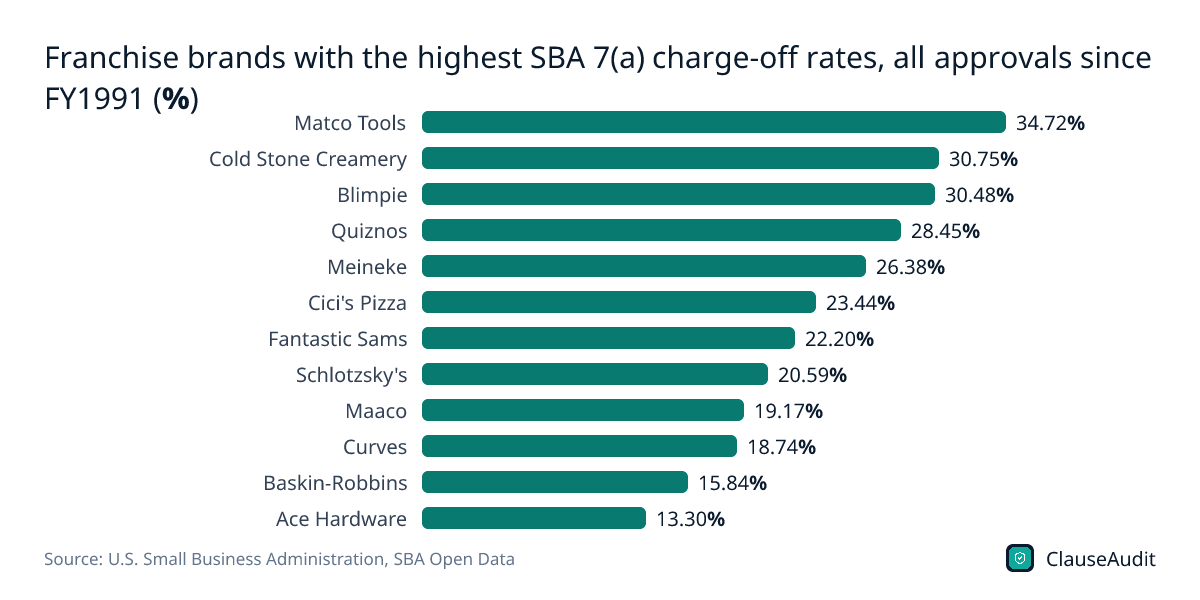
Download this chart (PNG)Franchise brands with the highest SBA 7(a) charge-off rates, all approvals since FY1991 (%)
Chart data
| Label | Value |
|---|---|
| Matco Tools | 34.72% |
| Cold Stone Creamery | 30.75% |
| Blimpie | 30.48% |
| Quiznos | 28.45% |
| Meineke | 26.38% |
| Cici's Pizza | 23.44% |
| Fantastic Sams | 22.20% |
| Schlotzsky's | 20.59% |
| Maaco | 19.17% |
| Curves | 18.74% |
| Baskin-Robbins | 15.84% |
| Ace Hardware | 13.30% |
Matco Tools tops the long-run list at 34.72%, but its loans averaged about $80K for mobile tool routes. Quiznos lost 659 of 2,316 resolved loans, a 28.45% rate across the full history.
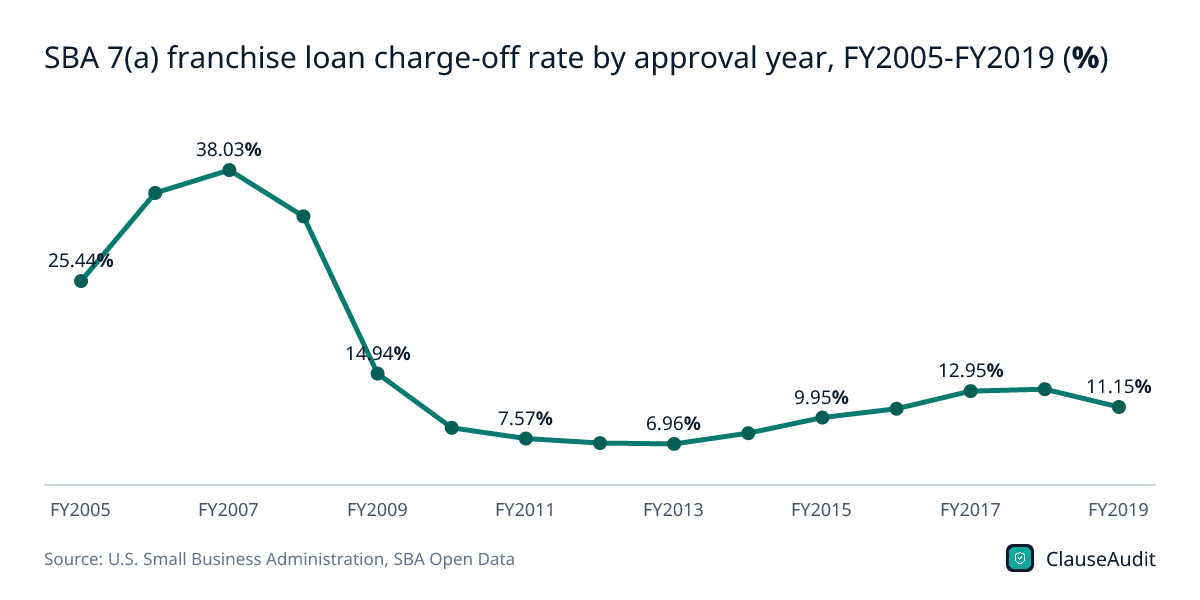
Download this chart (PNG)SBA 7(a) franchise loan charge-off rate by approval year, FY2005-FY2019 (%)
Chart data
| Label | Value (%) |
|---|---|
| FY2005 | 25.44% |
| FY2006 | 35.43% |
| FY2007 | 38.03% |
| FY2008 | 32.78% |
| FY2009 | 14.94% |
| FY2010 | 8.79% |
| FY2011 | 7.57% |
| FY2012 | 7.06% |
| FY2013 | 6.96% |
| FY2014 | 8.18% |
| FY2015 | 9.95% |
| FY2016 | 10.95% |
| FY2017 | 12.95% |
| FY2018 | 13.17% |
| FY2019 | 11.15% |
Loans approved in FY2007 failed at 38.03% because they ran straight into the recession. Rates bottomed at 6.96% in FY2013, then climbed to 13.17% for FY2018 approvals, many of which hit the pandemic shutdowns early in their life.
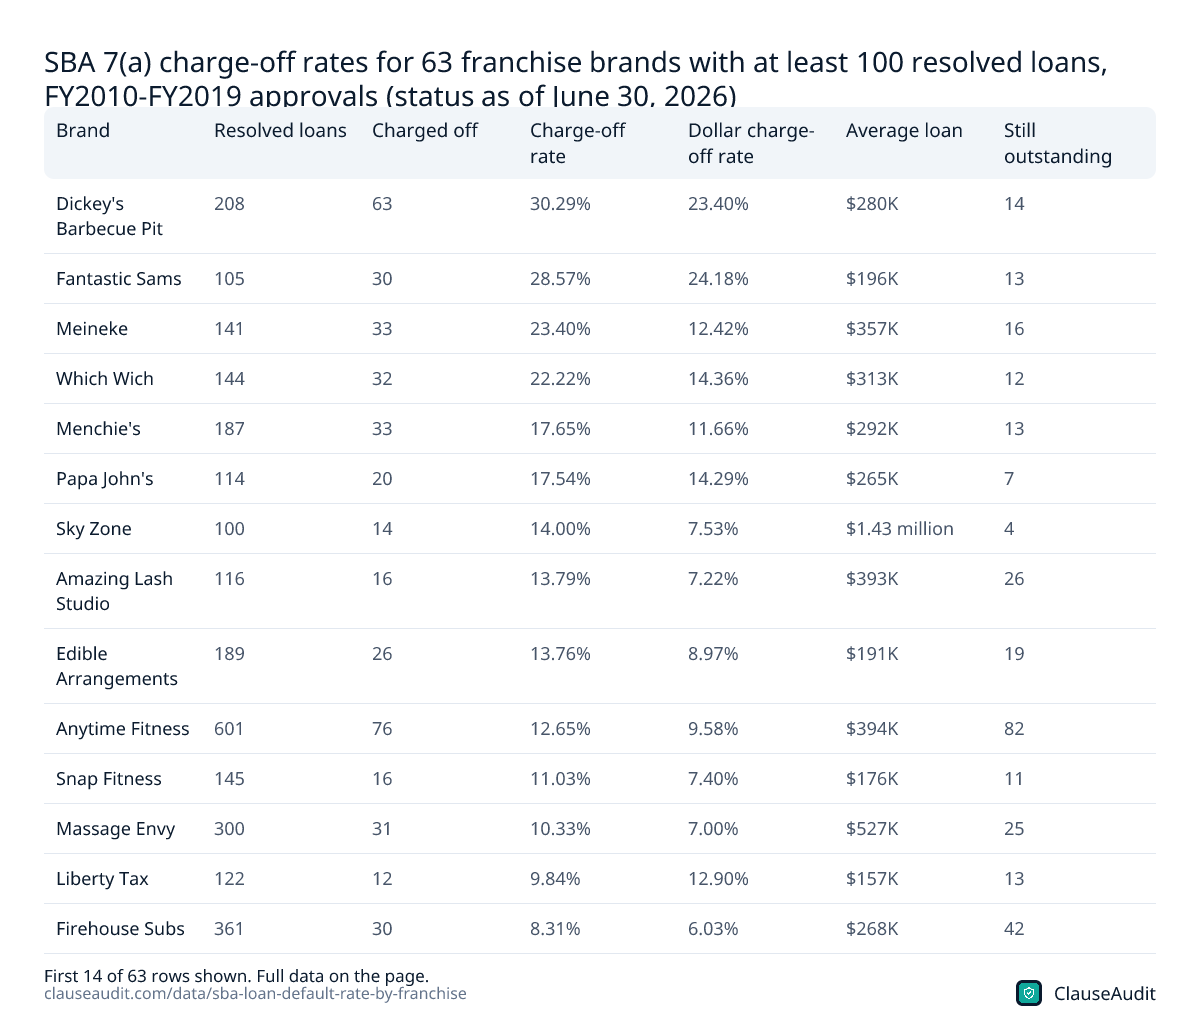
Download this chart (PNG)SBA 7(a) charge-off rates for 63 franchise brands with at least 100 resolved loans, FY2010-FY2019 approvals (status as of June 30, 2026)
| Brand | Resolved loans | Charged off | Charge-off rate | Dollar charge-off rate | Average loan | Still outstanding |
|---|---|---|---|---|---|---|
| Dickey's Barbecue Pit | 208 | 63 | 30.29% | 23.40% | $280K | 14 |
| Fantastic Sams | 105 | 30 | 28.57% | 24.18% | $196K | 13 |
| Meineke | 141 | 33 | 23.40% | 12.42% | $357K | 16 |
| Which Wich | 144 | 32 | 22.22% | 14.36% | $313K | 12 |
| Menchie's | 187 | 33 | 17.65% | 11.66% | $292K | 13 |
| Papa John's | 114 | 20 | 17.54% | 14.29% | $265K | 7 |
| Sky Zone | 100 | 14 | 14.00% | 7.53% | $1.43 million | 4 |
| Amazing Lash Studio | 116 | 16 | 13.79% | 7.22% | $393K | 26 |
| Edible Arrangements | 189 | 26 | 13.76% | 8.97% | $191K | 19 |
| Anytime Fitness | 601 | 76 | 12.65% | 9.58% | $394K | 82 |
| Snap Fitness | 145 | 16 | 11.03% | 7.40% | $176K | 11 |
| Massage Envy | 300 | 31 | 10.33% | 7.00% | $527K | 25 |
| Liberty Tax | 122 | 12 | 9.84% | 12.90% | $157K | 13 |
| Firehouse Subs | 361 | 30 | 8.31% | 6.03% | $268K | 42 |
| FASTSIGNS | 140 | 11 | 7.86% | 4.04% | $326K | 22 |
| FedEx Ground | 217 | 17 | 7.83% | 8.70% | $261K | 14 |
| Subway | 1,211 | 92 | 7.60% | 4.88% | $251K | 95 |
| Papa Murphy's | 187 | 14 | 7.49% | 4.27% | $266K | 18 |
| The Learning Experience | 108 | 8 | 7.41% | 3.48% | $543K | 20 |
| Marco's Pizza | 221 | 16 | 7.24% | 4.39% | $333K | 47 |
| Jimmy John's | 562 | 40 | 7.12% | 5.08% | $414K | 58 |
| Ace Hardware | 256 | 18 | 7.03% | 2.49% | $662K | 39 |
| Budget Blinds | 106 | 7 | 6.60% | 3.95% | $208K | 18 |
| Little Caesars | 355 | 22 | 6.20% | 4.30% | $357K | 10 |
| Sport Clips | 489 | 29 | 5.93% | 3.69% | $229K | 25 |
| Baymont | 103 | 5 | 4.85% | 2.59% | $2.37 million | 35 |
| Servpro | 287 | 13 | 4.53% | 4.76% | $290K | 8 |
| Kiddie Academy | 160 | 7 | 4.38% | 0.91% | $1.50 million | 36 |
| Allstate | 204 | 8 | 3.92% | 1.28% | $368K | 8 |
| Smoothie King | 182 | 7 | 3.85% | 2.96% | $268K | 33 |
| Supercuts | 197 | 7 | 3.55% | 1.53% | $280K | 23 |
| Hand & Stone | 118 | 4 | 3.39% | 2.06% | $398K | 21 |
| Tropical Smoothie Cafe | 194 | 6 | 3.09% | 1.92% | $288K | 30 |
| Motel 6 | 165 | 5 | 3.03% | 0.68% | $1.88 million | 57 |
| Quality Inn | 358 | 10 | 2.79% | 2.37% | $2.29 million | 99 |
| The Goddard School | 225 | 6 | 2.67% | 0.59% | $1.86 million | 91 |
| Dairy Queen | 351 | 9 | 2.56% | 1.50% | $556K | 65 |
| European Wax Center | 274 | 7 | 2.55% | 1.54% | $368K | 34 |
| ServiceMaster | 118 | 3 | 2.54% | 0.42% | $458K | 15 |
| Comfort Inn / Suites | 238 | 6 | 2.52% | 1.30% | $2.83 million | 59 |
| Super 8 | 279 | 7 | 2.51% | 1.32% | $1.71 million | 84 |
| Great Clips | 222 | 5 | 2.25% | 1.73% | $223K | 9 |
| Days Inn | 316 | 7 | 2.22% | 1.31% | $1.99 million | 84 |
| Jersey Mike's | 226 | 5 | 2.21% | 1.98% | $292K | 19 |
| Holiday Inn / Express | 142 | 3 | 2.11% | 2.11% | $3.33 million | 27 |
| Best Western | 201 | 4 | 1.99% | 1.18% | $2.62 million | 58 |
| Cold Stone Creamery | 102 | 2 | 1.96% | 0.65% | $188K | 19 |
| Econo Lodge | 165 | 3 | 1.82% | 1.04% | $1.53 million | 46 |
| Home Instead | 175 | 3 | 1.71% | 0.90% | $563K | 17 |
| Orangetheory Fitness | 312 | 5 | 1.60% | 0.97% | $491K | 34 |
| Chevron (gas station) | 133 | 2 | 1.50% | 0.79% | $1.46 million | 32 |
| Domino's | 216 | 3 | 1.39% | 0.47% | $394K | 19 |
| Red Roof Inn | 152 | 2 | 1.32% | 0.24% | $2.01 million | 45 |
| Dunkin' | 259 | 3 | 1.16% | 1.81% | $650K | 11 |
| The UPS Store | 447 | 3 | 0.67% | 0.45% | $214K | 72 |
| Primrose Schools | 190 | 1 | 0.53% | 0.24% | $2.70 million | 54 |
| Ameriprise | 307 | 1 | 0.33% | 0.07% | $562K | 23 |
| Culver's | 178 | 0 | 0.00% | 0.00% | $1.36 million | 37 |
| Club Pilates | 151 | 0 | 0.00% | 0.00% | $222K | 21 |
| Wingstop | 149 | 0 | 0.00% | 0.00% | $383K | 8 |
| Christian Brothers Automotive | 139 | 0 | 0.00% | 0.00% | $340K | 34 |
| Nothing Bundt Cakes | 116 | 0 | 0.00% | 0.00% | $343K | 15 |
| Planet Fitness | 111 | 0 | 0.00% | 0.00% | $1.06 million | 3 |
Source: U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY2010-FY2019) loan-level data, as of June 30, 2026 (FOIA_7a_FY2010_FY2019_asof_260630.csv); U.S. Small Business Administration, SBA Open Data, 7(a) and 504 FOIA data dictionary (LoanStatus: CHGOFF = Charged Off, PIF = Paid In Full, EXEMPT = disbursed loans not yet resolved). Download as image
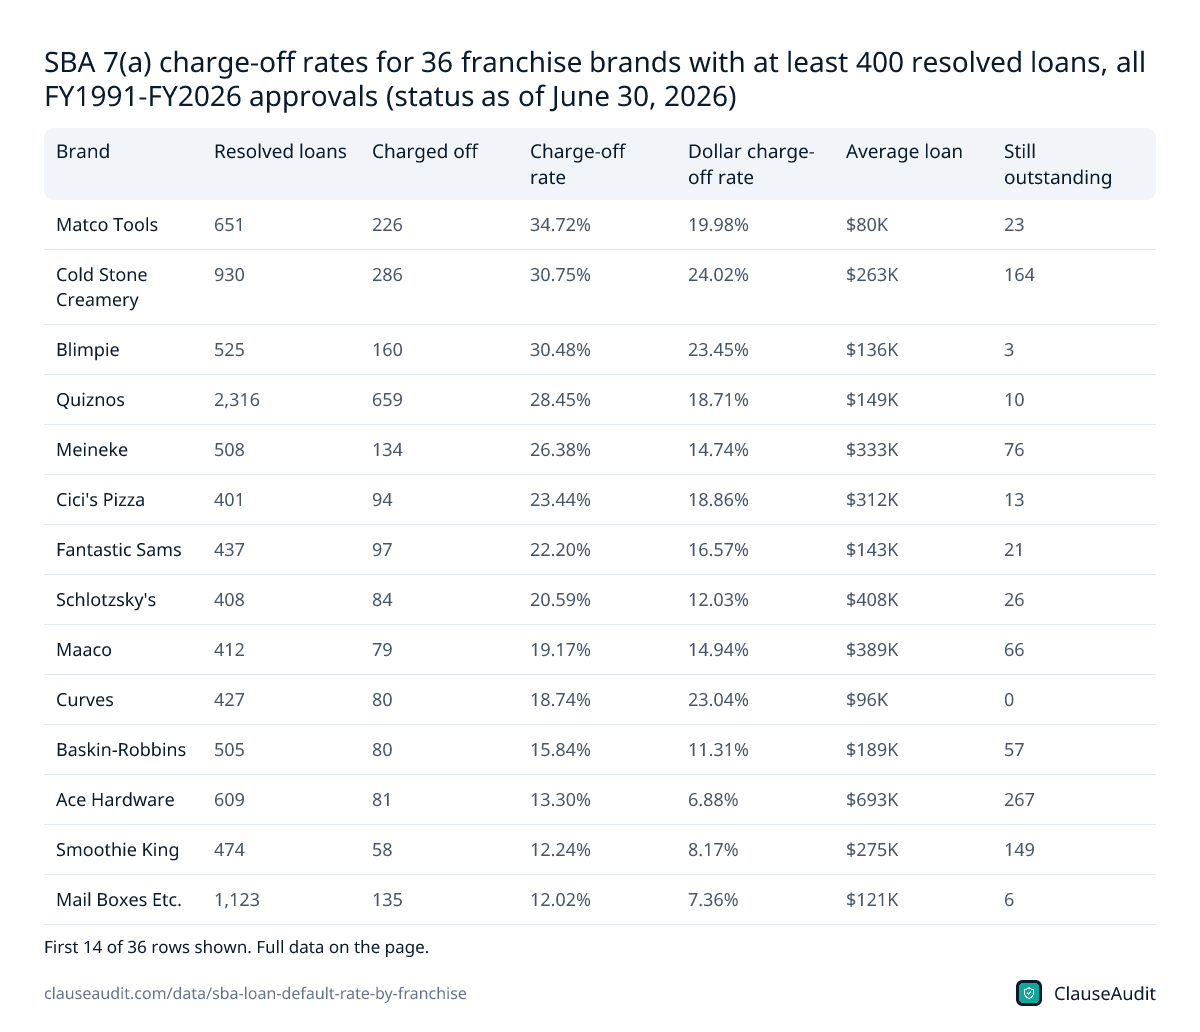
SBA 7(a) charge-off rates for 36 franchise brands with at least 400 resolved loans, all FY1991-FY2026 approvals (status as of June 30, 2026)
| Brand | Resolved loans | Charged off | Charge-off rate | Dollar charge-off rate | Average loan | Still outstanding |
|---|---|---|---|---|---|---|
| Matco Tools | 651 | 226 | 34.72% | 19.98% | $80K | 23 |
| Cold Stone Creamery | 930 | 286 | 30.75% | 24.02% | $263K | 164 |
| Blimpie | 525 | 160 | 30.48% | 23.45% | $136K | 3 |
| Quiznos | 2,316 | 659 | 28.45% | 18.71% | $149K | 10 |
| Meineke | 508 | 134 | 26.38% | 14.74% | $333K | 76 |
| Cici's Pizza | 401 | 94 | 23.44% | 18.86% | $312K | 13 |
| Fantastic Sams | 437 | 97 | 22.20% | 16.57% | $143K | 21 |
| Schlotzsky's | 408 | 84 | 20.59% | 12.03% | $408K | 26 |
| Maaco | 412 | 79 | 19.17% | 14.94% | $389K | 66 |
| Curves | 427 | 80 | 18.74% | 23.04% | $96K | 0 |
| Baskin-Robbins | 505 | 80 | 15.84% | 11.31% | $189K | 57 |
| Ace Hardware | 609 | 81 | 13.30% | 6.88% | $693K | 267 |
| Smoothie King | 474 | 58 | 12.24% | 8.17% | $275K | 149 |
| Mail Boxes Etc. | 1,123 | 135 | 12.02% | 7.36% | $121K | 6 |
| Anytime Fitness | 827 | 99 | 11.97% | 8.93% | $409K | 281 |
| Firehouse Subs | 477 | 53 | 11.11% | 8.18% | $306K | 163 |
| Days Inn | 859 | 84 | 9.78% | 5.15% | $1.68 million | 277 |
| Domino's | 851 | 82 | 9.64% | 5.97% | $376K | 166 |
| Dairy Queen | 1,369 | 123 | 8.98% | 4.18% | $427K | 224 |
| Massage Envy | 476 | 41 | 8.61% | 6.33% | $446K | 44 |
| Super 8 | 825 | 66 | 8.00% | 3.73% | $1.53 million | 272 |
| Dunkin' | 1,030 | 76 | 7.38% | 4.41% | $596K | 75 |
| The UPS Store | 1,143 | 83 | 7.26% | 4.16% | $275K | 774 |
| Best Western | 504 | 36 | 7.14% | 2.91% | $2.31 million | 190 |
| Econo Lodge | 435 | 31 | 7.13% | 3.77% | $1.33 million | 152 |
| Papa Murphy's | 441 | 30 | 6.80% | 4.80% | $254K | 47 |
| Subway | 4,834 | 328 | 6.79% | 3.99% | $190K | 310 |
| Servpro | 583 | 39 | 6.69% | 4.96% | $429K | 130 |
| Little Caesars | 550 | 34 | 6.18% | 3.61% | $402K | 90 |
| Sport Clips | 798 | 48 | 6.02% | 3.83% | $229K | 67 |
| Jimmy John's | 779 | 46 | 5.91% | 4.13% | $441K | 146 |
| Great Clips | 515 | 26 | 5.05% | 2.64% | $224K | 32 |
| Quality Inn | 529 | 25 | 4.73% | 2.65% | $2.39 million | 304 |
| Jersey Mike's | 432 | 18 | 4.17% | 2.11% | $355K | 165 |
| The Goddard School | 420 | 16 | 3.81% | 0.88% | $1.59 million | 293 |
| Comfort Inn / Suites | 534 | 11 | 2.06% | 1.21% | $2.59 million | 211 |
Source: U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY1991-FY1999) loan-level data, as of June 30, 2026 (FOIA_7a_FY1991_FY1999_asof_260630.csv); U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY2000-FY2009) loan-level data, as of June 30, 2026 (FOIA_7a_FY2000_FY2009_asof_260630.csv); U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY2010-FY2019) loan-level data, as of June 30, 2026 (FOIA_7a_FY2010_FY2019_asof_260630.csv); U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY2020-Present) loan-level data, as of June 30, 2026 (FOIA_7a_FY2020_Present_asof_260630.csv); U.S. Small Business Administration, SBA Open Data, 7(a) and 504 FOIA data dictionary (LoanStatus: CHGOFF = Charged Off, PIF = Paid In Full, EXEMPT = disbursed loans not yet resolved). Download as image
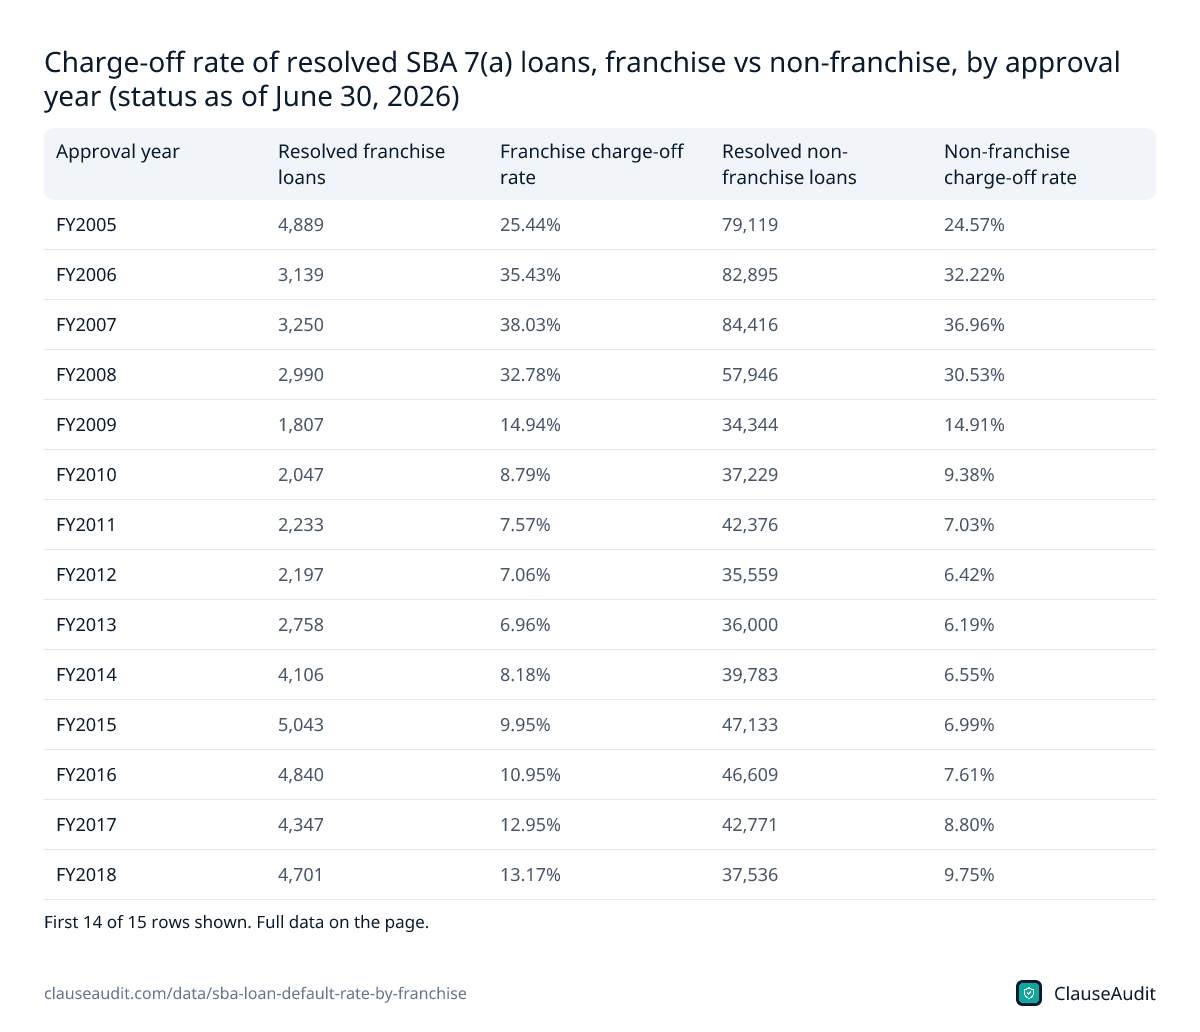
Charge-off rate of resolved SBA 7(a) loans, franchise vs non-franchise, by approval year (status as of June 30, 2026)
| Approval year | Resolved franchise loans | Franchise charge-off rate | Resolved non-franchise loans | Non-franchise charge-off rate |
|---|---|---|---|---|
| FY2005 | 4,889 | 25.44% | 79,119 | 24.57% |
| FY2006 | 3,139 | 35.43% | 82,895 | 32.22% |
| FY2007 | 3,250 | 38.03% | 84,416 | 36.96% |
| FY2008 | 2,990 | 32.78% | 57,946 | 30.53% |
| FY2009 | 1,807 | 14.94% | 34,344 | 14.91% |
| FY2010 | 2,047 | 8.79% | 37,229 | 9.38% |
| FY2011 | 2,233 | 7.57% | 42,376 | 7.03% |
| FY2012 | 2,197 | 7.06% | 35,559 | 6.42% |
| FY2013 | 2,758 | 6.96% | 36,000 | 6.19% |
| FY2014 | 4,106 | 8.18% | 39,783 | 6.55% |
| FY2015 | 5,043 | 9.95% | 47,133 | 6.99% |
| FY2016 | 4,840 | 10.95% | 46,609 | 7.61% |
| FY2017 | 4,347 | 12.95% | 42,771 | 8.80% |
| FY2018 | 4,701 | 13.17% | 37,536 | 9.75% |
| FY2019 | 3,945 | 11.15% | 27,661 | 9.46% |
Source: U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY2000-FY2009) loan-level data, as of June 30, 2026 (FOIA_7a_FY2000_FY2009_asof_260630.csv); U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY2010-FY2019) loan-level data, as of June 30, 2026 (FOIA_7a_FY2010_FY2019_asof_260630.csv); U.S. Small Business Administration, SBA Open Data, 7(a) and 504 FOIA data dictionary (LoanStatus: CHGOFF = Charged Off, PIF = Paid In Full, EXEMPT = disbursed loans not yet resolved). Download as image
What is the SBA loan default rate for franchises?
For loans approved between FY2010 and FY2019, 10.18% of resolved franchise loans were charged off. That counts 3,686 failed loans out of 36,217 that either paid in full or were written off by June 30, 2026. Non-franchise loans from the same years failed at 7.76%.
Stretch the window back to FY1991 and the two groups look almost identical: 15.87% for franchises and 15.75% for everyone else. The long-run number is higher because it includes loans approved in the mid-2000s that ran straight into the 2008-2009 recession.
A note on wording. The SBA files don't have a field called "default." A borrower can miss payments, catch up, and never show up as a loss. A charge-off is the end of the road: the lender stopped collecting and wrote off what was left. So these rates understate how many owners hit trouble, but they show exactly how many loans were lost.
Loans still being repaid are left out. That matters for newer brands, where many loans haven't had time to either succeed or fail.
Which franchise brands have the highest SBA default rates?
Among 63 brands with at least 100 resolved loans from FY2010-FY2019, Dickey's Barbecue Pit had the worst record at 30.29%. That's 63 charge-offs out of 208 loans. Fantastic Sams, Meineke and Which Wich round out the top of the list.
Over the full history, among brands with 400+ resolved loans, Matco Tools sits highest at 34.72%, followed by Cold Stone Creamery, Blimpie and Quiznos. Quiznos alone accounts for 659 charge-offs.
Brands can change, for better or worse. Cold Stone Creamery charged off 30.75% of loans across all years, but only 1.96% of its FY2010-FY2019 loans. Read the decade table first, then use the all-years table to see whether a brand has a history worth asking about.
Look at what these brands share. Most are food, service and repair concepts, and 10 of the 12 worst averaged under $400K per loan. A smaller loan makes a franchise easier to buy, but it can also mean less cushion when sales come in under plan. Fitness concepts show up too: Anytime Fitness charged off 12.65% of its loans in the decade, Snap Fitness 11.03%.
Are franchises safer than independent businesses?
Not on this evidence. Franchise loans in the 2010s did worse than non-franchise loans, and over three decades the two are basically tied. The year-by-year table shows the gap widening from FY2014 on: franchise loans approved in FY2016 failed at 10.95%, against 7.61% for non-franchise loans.
What a franchise does give you is a much narrower set of outcomes per brand. Subway, the most financed brand of the decade, charged off 7.60% of its resolved loans. The UPS Store charged off 0.67%. Planet Fitness and Wingstop had none. If you pick a brand with a strong record, a franchise can be a safer bet than starting from scratch. If you pick a weak one, it can be worse.
Franchises are still a big slice of SBA lending. In FY2025, 9.19% of 7(a) loan approvals went to franchise businesses, roughly 1 in 11.
Why did franchise defaults rise for loans made after FY2014?
The approval-year chart has a shape worth understanding. Franchise loans made in FY2013 charged off at 6.96%. By FY2018 the rate had nearly doubled to 13.17%. Non-franchise loans rose too, but less, reaching 9.75% for the same year.
A few things likely played a part. Franchise lending grew fast in those years: resolved franchise loans went from 2,758 for FY2013 approvals to 5,043 for FY2015. When money flows easily, weaker borrowers and weaker brands get funded. A brand with little history can look great on paper until its first wave of owners runs out of cash.
Timing hurt as well. A loan approved in FY2017 or FY2018 was only a couple of years old when the pandemic closed dining rooms, gyms and salons. Young loans have the least equity and the largest balances, so they break first.
The lesson for a buyer today: a brand's recent growth is not proof that its owners are doing well. Check its charge-off rate next to the closure counts in its FDD before you trust the sales pitch.
What the dollar charge-off rate adds
The brand tables show two rates. The loan count rate tells you how often borrowers failed. The dollar rate tells you how much money was lost, and it's usually lower because lenders recover some of the balance from collateral and guarantors.
When the dollar rate is close to or above the count rate, it can mean failures came early, before much was repaid, or that the bigger loans were the ones that failed. Liberty Tax is an example: 9.84% of loans charged off, but 12.90% of dollars. Dickey's lost 23.40% of dollars. For you as the borrower, early failure is the worst case, because the unpaid balance is large and your personal guarantee covers it.
How to use these numbers before you sign
- Look up the brand in both tables. A brand with 100+ resolved loans and a rate under the 10.18% franchise average is a reasonable start, not a guarantee.
- Ask the franchisor about the gap. If their rate is well above average, ask what changed and get the answer in writing.
- Compare against the FDD's outlet tables, which list closures, transfers and terminations by year. High charge-offs plus high turnover is a pattern, not bad luck.
- Call former franchisees listed in the FDD. Ask whether they still owed on their SBA loan when they closed.
- Read the personal guarantee on the loan and on the franchise agreement. SBA lenders require one from major owners, and a charge-off can follow you to your house and savings.
- Check what the franchise agreement makes you spend after opening, such as remodels or new equipment. Required spending soon after opening piles on cost right when cash is tightest and the loan balance is highest.
How ClauseAudit helps
A brand's default rate tells you the odds. Your franchise agreement decides who pays when things go wrong. Upload it and our automated review flags the clauses that turn a slow year into a charge-off with your name on it.
It reads the agreement in plain English and points to terms worth negotiating before you take on SBA debt.
- Personal guarantees and spousal guarantees tied to the franchise agreement
- Termination triggers and cross-default terms that link the agreement to your loan or lease
- Mandatory remodel, equipment upgrade and technology fees in the first years
- Royalty, ad fund and minimum payment terms that keep running in a weak month
- Territory protection and the franchisor's right to open nearby
- Transfer and resale restrictions that make it hard to sell your way out
Frequently asked questions
What franchise has the highest SBA loan default rate?
Among brands with 100+ resolved loans approved FY2010-FY2019, Dickey's Barbecue Pit had the highest charge-off rate at 30.29%. Across all approvals since FY1991, Matco Tools was highest at 34.72% among brands with 400+ resolved loans, though its loans were small, averaging about $80K.
Do franchises default less than independent businesses on SBA loans?
No. For FY2010-FY2019 approvals, 10.18% of resolved franchise loans were charged off, compared with 7.76% of non-franchise loans. Over all years since FY1991 the rates are close, at 15.87% and 15.75%. The brand you pick moves the odds far more than franchising itself.
What is the Subway SBA loan default rate?
Subway charged off 7.60% of its resolved SBA 7(a) loans approved FY2010-FY2019, or 92 of 1,211. Across all years the rate was 6.79%, 328 of 4,834 loans. That puts Subway below the franchise average for the decade, even though it was the most financed brand.
Which franchises had zero SBA loan charge-offs?
Six brands with 100+ resolved FY2010-FY2019 loans had no charge-offs: Culver's, Club Pilates, Wingstop, Christian Brothers Automotive, Nothing Bundt Cakes and Planet Fitness. Some of their loans are still outstanding, so a zero today could change as those loans finish.
Is a charge-off the same as a default?
Not exactly. A default can be a missed payment that the borrower later fixes. A charge-off means the lender gave up collecting and wrote the remaining balance off as a loss. These rates count charge-offs only, so they show loans that were truly lost, not every borrower who struggled.
Why are the all-years default rates so much higher?
The all-years figures include loans approved in the mid-2000s that hit the 2008-2009 recession. Franchise loans approved in FY2007 failed at 38.03%. Loans from the 2010s did much better, which is why the FY2010-FY2019 franchise rate is 10.18% while the long-run rate is 15.87%.
Does a low brand default rate mean my franchise will succeed?
No. It means past borrowers in that brand usually repaid. Your location, lease, opening costs and management still decide your result. Use the rate as a filter, then check the brand's FDD, talk to current and former owners, and read the guarantee and termination terms carefully.
Where does this SBA franchise data come from?
It comes from the SBA's public 7(a) FOIA loan files, status as of June 30, 2026. ClauseAudit matched each loan to its franchise code, merged spelling variants of brand names, and counted only loans that were paid in full or charged off. Loans still being repaid are excluded.
Use this data
Every chart and card below is free to reuse under CC BY 4.0. Download what you need and link back to this page.
 Stat cards
 Key findings card
 Infographic
 Franchise brands with the highest SBA 7(a) charge-off rates (FY2010-FY2019 approvals) (%)
 SBA 7(a) charge-off rate for the 12 most-financed franchise brands (FY2010-FY2019 approvals) (%)
 Franchise brands with the lowest non-zero SBA 7(a) charge-off rates (FY2010-FY2019 approvals) (%)
 Franchise brands with the highest SBA 7(a) charge-off rates, all approvals since FY1991 (%)
 SBA 7(a) franchise loan charge-off rate by approval year, FY2005-FY2019 (%)
 SBA 7(a) charge-off rates for 63 franchise brands with at least 100 resolved loans, FY2010-FY2019 approvals (status as of June 30, 2026)
 SBA 7(a) charge-off rates for 36 franchise brands with at least 400 resolved loans, all FY1991-FY2026 approvals (status as of June 30, 2026)
 Charge-off rate of resolved SBA 7(a) loans, franchise vs non-franchise, by approval year (status as of June 30, 2026)
Embed the infographic
Free to share on your site, blog or slides under CC BY 4.0. Please keep the credit link.
Sources and method
Every number on this page comes from the sources below, each opened and read on or before October 18, 2026. A second, independent review checked every figure against its source and corrected anything that did not match. Figures that could not be confirmed were left out.
- U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY1991-FY1999) loan-level data, as of June 30, 2026 (FOIA_7a_FY1991_FY1999_asof_260630.csv) (As of June 30, 2026 (file posted July 21, 2026))
- U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY2000-FY2009) loan-level data, as of June 30, 2026 (FOIA_7a_FY2000_FY2009_asof_260630.csv) (As of June 30, 2026 (file posted July 21, 2026))
- U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY2010-FY2019) loan-level data, as of June 30, 2026 (FOIA_7a_FY2010_FY2019_asof_260630.csv) (As of June 30, 2026 (file posted July 21, 2026))
- U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) (FY2020-Present) loan-level data, as of June 30, 2026 (FOIA_7a_FY2020_Present_asof_260630.csv) (As of June 30, 2026 (file posted July 21, 2026))
- U.S. Small Business Administration, SBA Open Data, FOIA - 7(a) loan-level data, all four files (FY1991-FY1999, FY2000-FY2009, FY2010-FY2019, FY2020-Present), as of June 30, 2026 (As of June 30, 2026 (files posted July 21, 2026))
- U.S. Small Business Administration, SBA Open Data, 7(a) and 504 FOIA data dictionary (LoanStatus: CHGOFF = Charged Off, PIF = Paid In Full, EXEMPT = disbursed loans not yet resolved) (Data dictionary posted with the June 30, 2026 FOIA files)
Cite this page
ClauseAudit, “SBA Loan Default Rates by Franchise Brand, Computed From SBA 7(a) Data”, updated October 18, 2026, https://clauseaudit.com/data/sba-loan-default-rate-by-franchise. Free to reuse with a link back (CC BY 4.0).
This page summarises published data and law as checked on October 18, 2026. Figures are updated as new editions are released, and your own situation may differ. It is general information, not legal, tax or financial advice.