SBA 7(a) Maximum Interest Rates and Guarantee Fees for FY2026
By ClauseAudit Research · 8 sources ·
What are the current SBA 7(a) interest rates?
SBA 7(a) rates are capped, not set. For October 2026 the maximum fixed rate is 12% on loans over $250,000 and 15% on loans of $25,000 or less, built on a 7% prime rate. Variable loans over $350,000 can go no higher than the base rate plus 3.0 points. Lenders can quote below the cap.
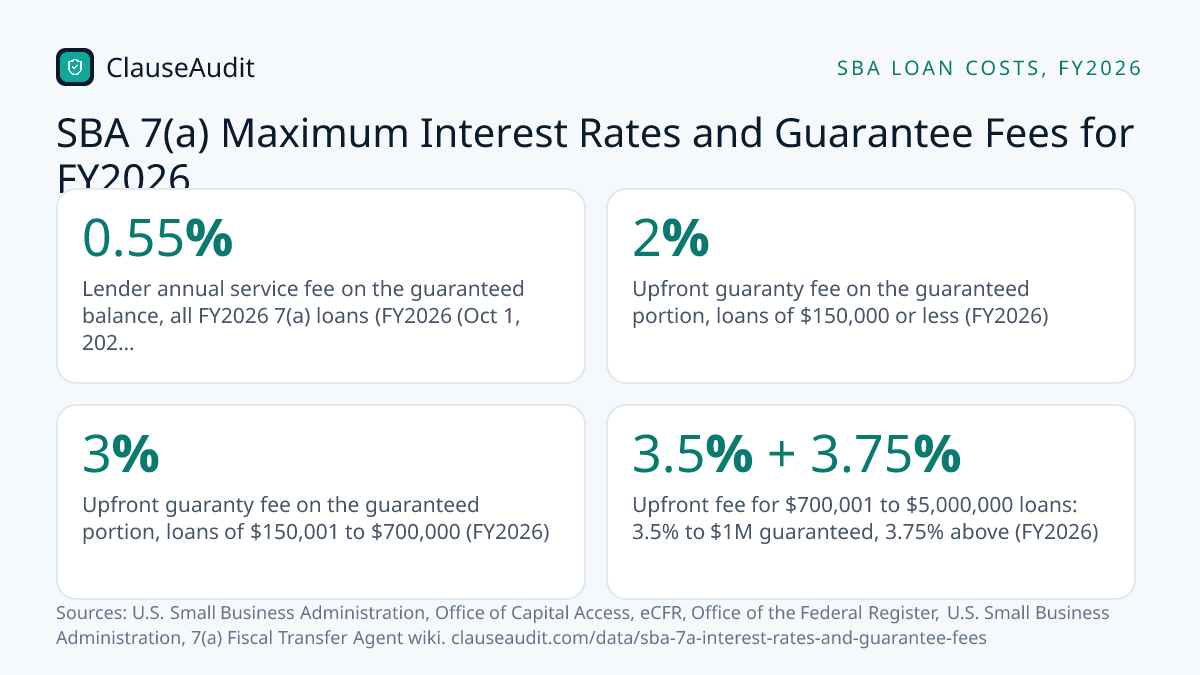
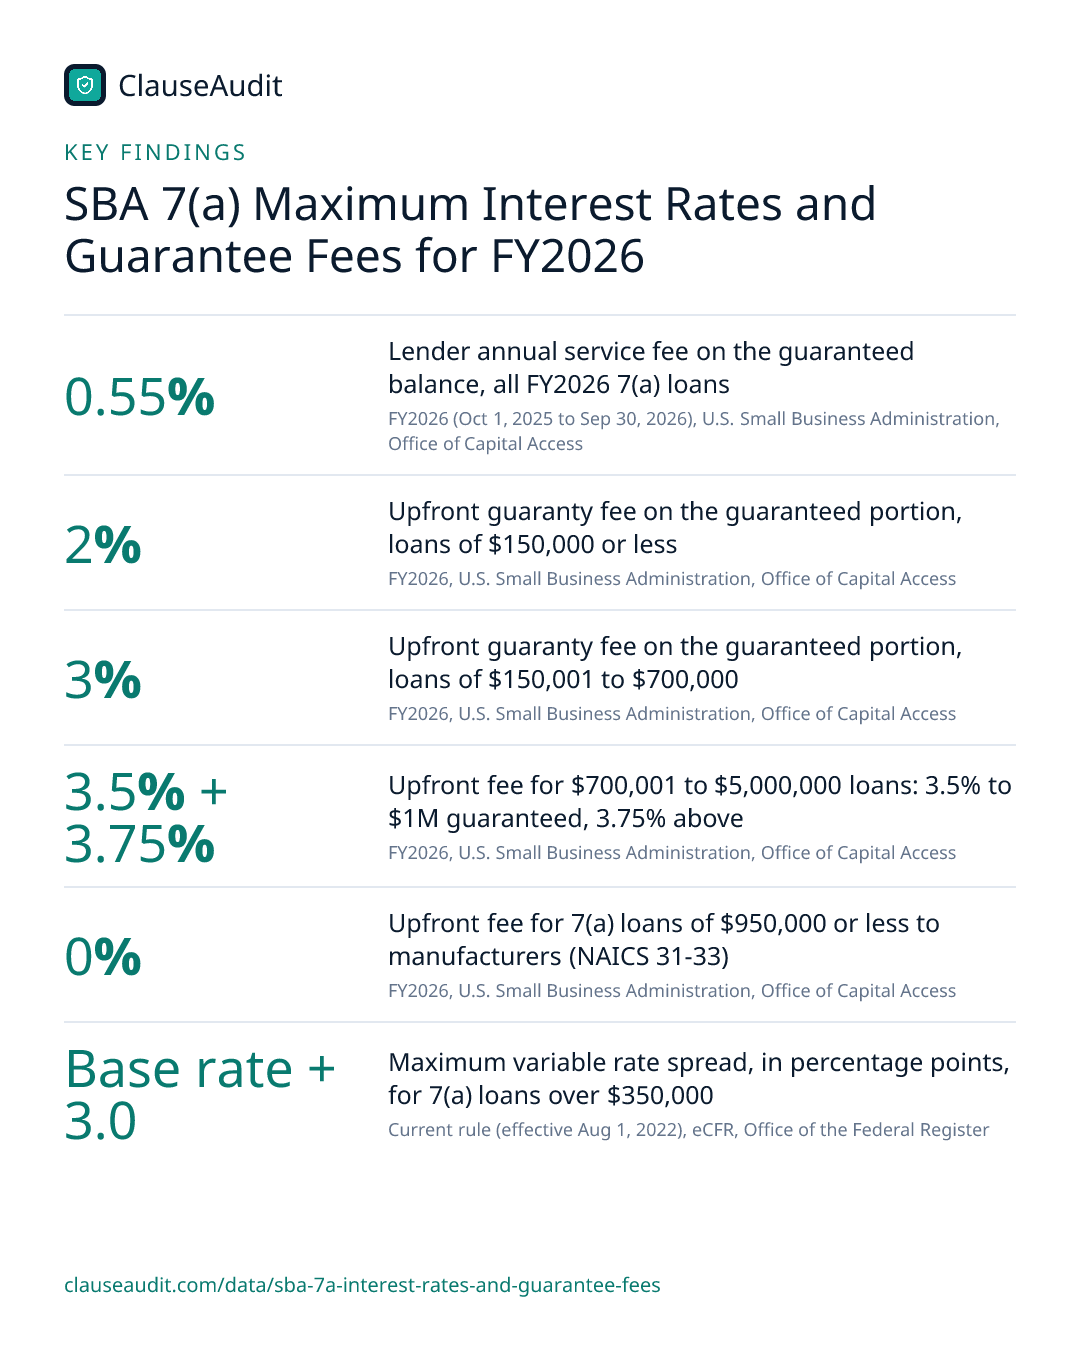
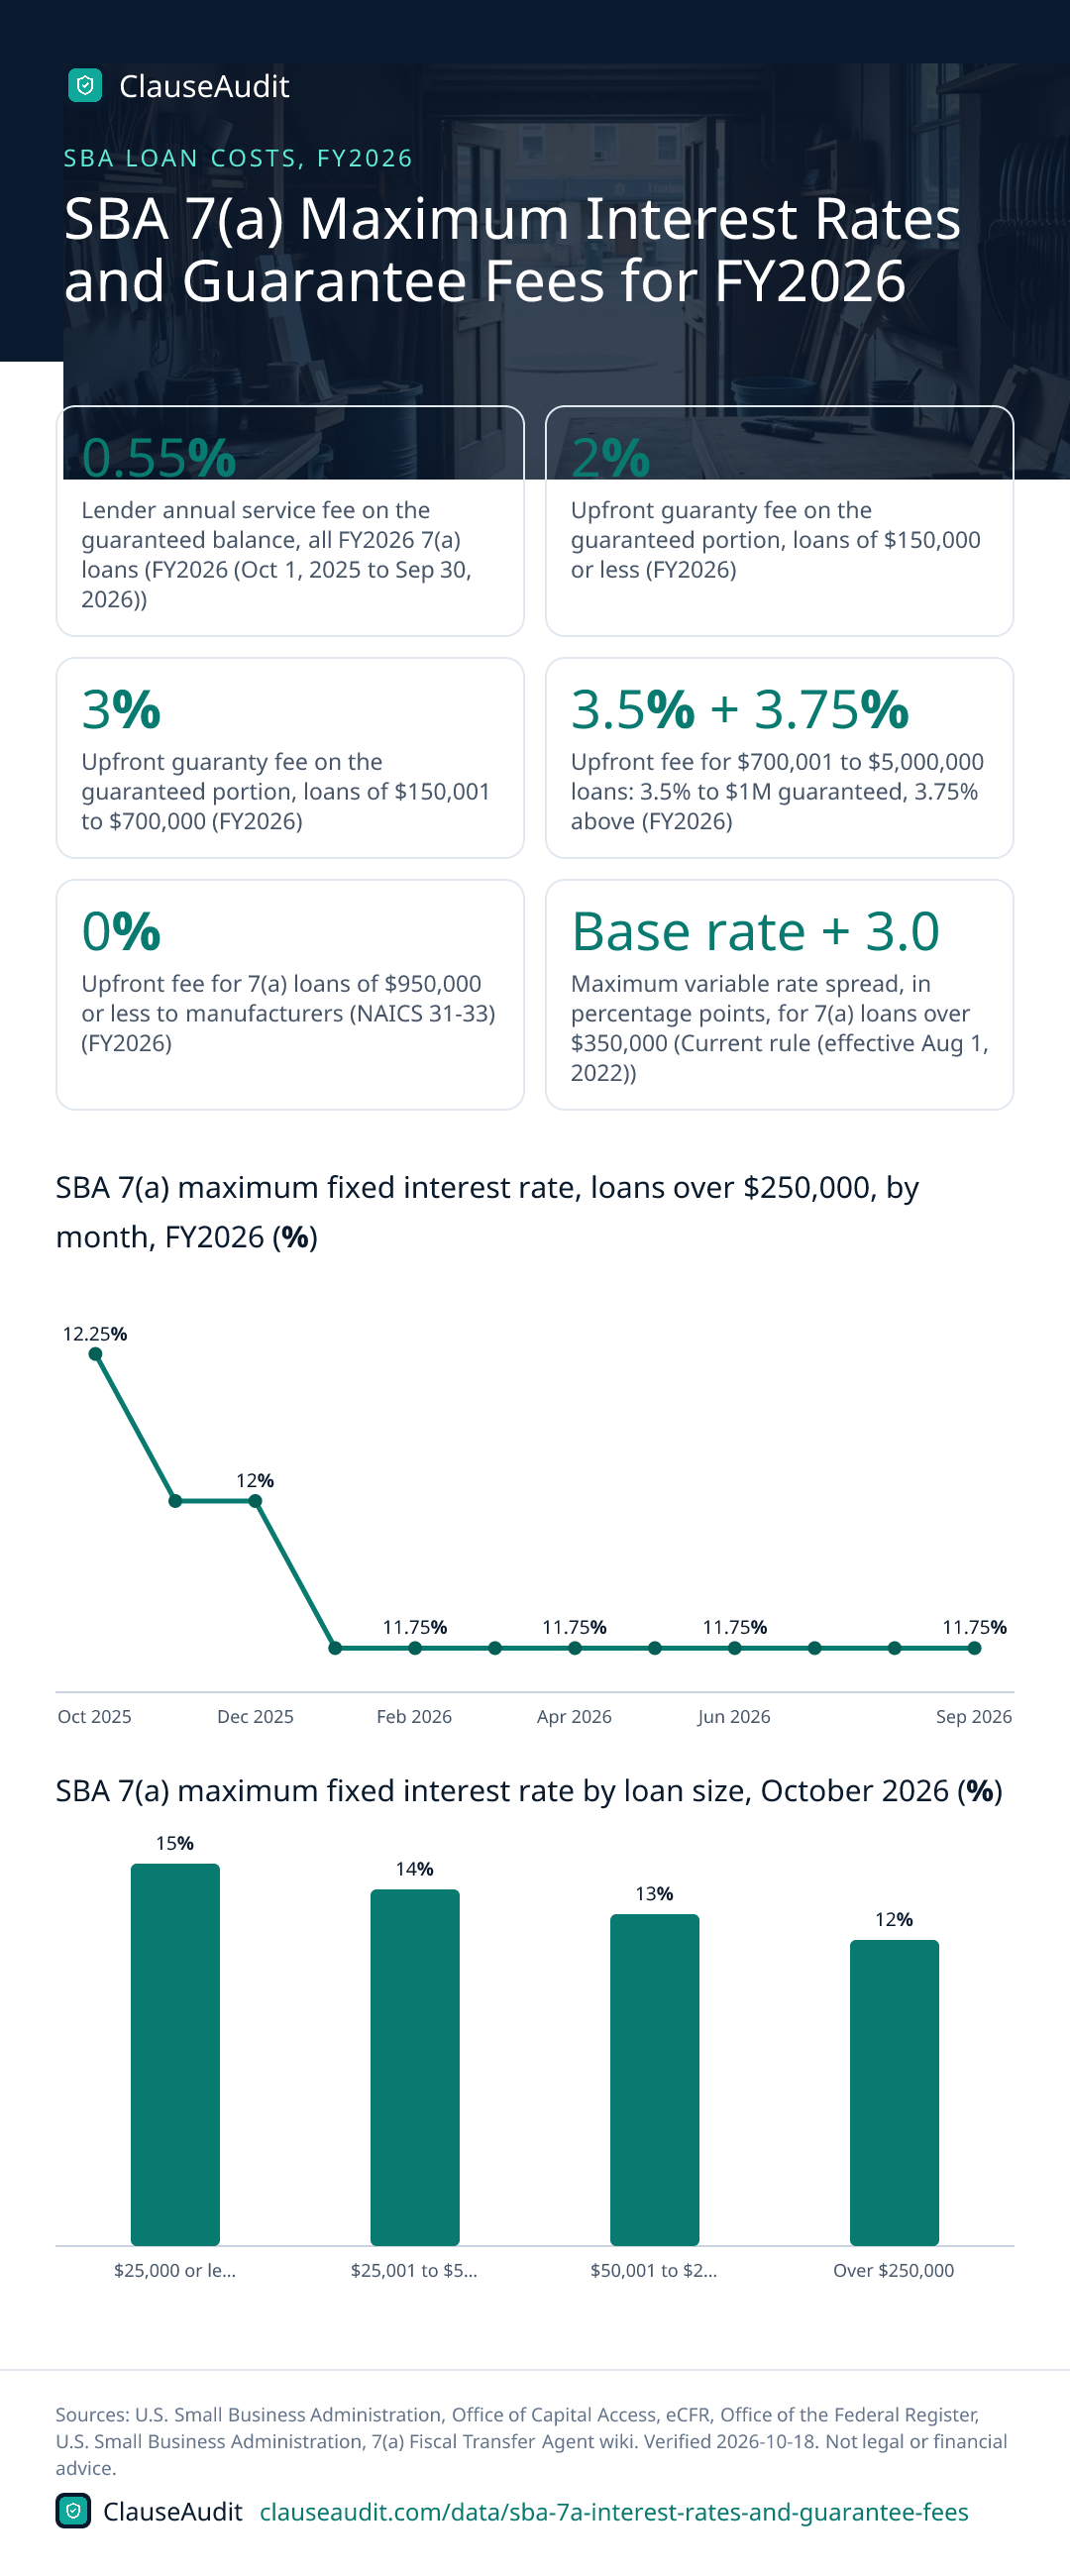
- Lender annual service fee on the guaranteed balance, all FY2026 7(a) loans (FY2026 (Oct 1, 2025 to Sep 30, 2026), U.S. Small Business Administration, Office of Capital Access)
- 0.55%
- Upfront guaranty fee on the guaranteed portion, loans of $150,000 or less (FY2026, U.S. Small Business Administration, Office of Capital Access)
- 2%
- Upfront guaranty fee on the guaranteed portion, loans of $150,001 to $700,000 (FY2026, U.S. Small Business Administration, Office of Capital Access)
- 3%
- Upfront fee for $700,001 to $5,000,000 loans: 3.5% to $1M guaranteed, 3.75% above (FY2026, U.S. Small Business Administration, Office of Capital Access)
- 3.5% + 3.75%
- Upfront fee for 7(a) loans of $950,000 or less to manufacturers (NAICS 31-33) (FY2026, U.S. Small Business Administration, Office of Capital Access)
- 0%
- Maximum variable rate spread, in percentage points, for 7(a) loans over $350,000 (Current rule (effective Aug 1, 2022), eCFR, Office of the Federal Register)
- Base rate + 3.0
- Maximum fixed rate for 7(a) loans over $250,000 (prime 7% + 5 points) (October 2026, U.S. Small Business Administration, 7(a) Fiscal Transfer Agent wiki)
- 12%
- Maximum fixed rate for 7(a) loans of $25,000 or less (prime 7% + 8 points) (October 2026, U.S. Small Business Administration, 7(a) Fiscal Transfer Agent wiki)
- 15%
The SBA does not set your interest rate. Your lender does. What the SBA sets is a ceiling, tied to the prime rate, and the ceiling moves every time prime moves. Smaller loans get a higher ceiling, in part because they take nearly as much work to process as big ones.
Fees are where FY2026 changed the math. After a year when loans up to $1,000,000 paid no upfront guarantee fee at all, the fee came back at 2% to 3.75% of the guaranteed portion. If you are comparing an SBA offer with a bank term loan or online lender, you need both numbers, not just the rate.
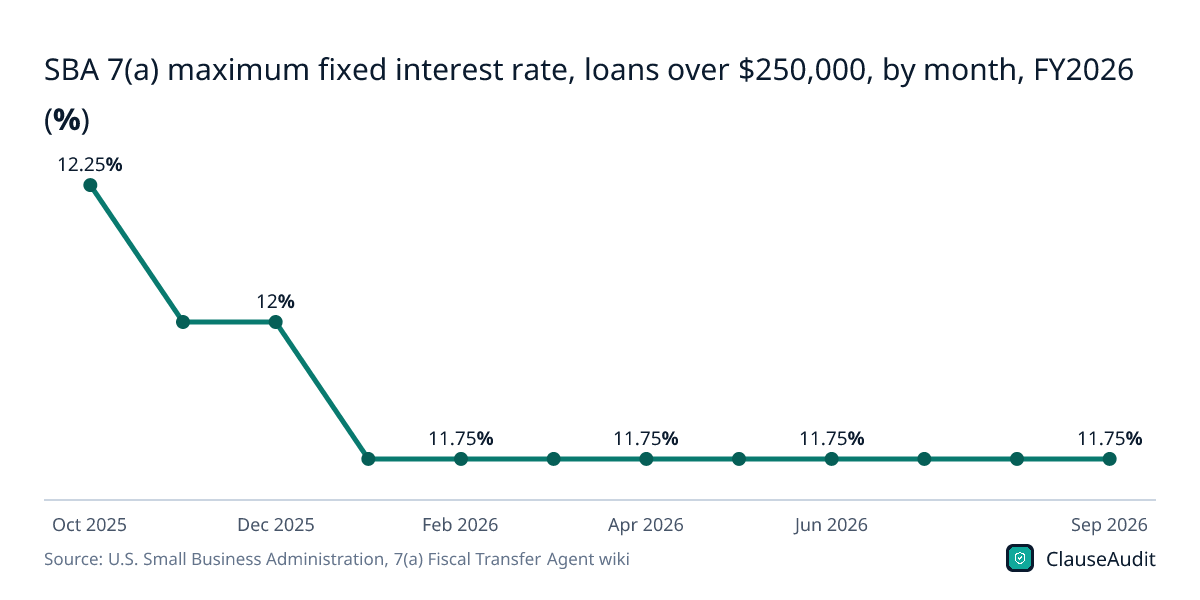
SBA 7(a) maximum fixed interest rate, loans over $250,000, by month, FY2026 (%)
Chart data
| Label | Value (%) |
|---|---|
| Oct 2025 | 12.25% |
| Nov 2025 | 12% |
| Dec 2025 | 12% |
| Jan 2026 | 11.75% |
| Feb 2026 | 11.75% |
| Mar 2026 | 11.75% |
| Apr 2026 | 11.75% |
| May 2026 | 11.75% |
| Jun 2026 | 11.75% |
| Jul 2026 | 11.75% |
| Aug 2026 | 11.75% |
| Sep 2026 | 11.75% |
The cap dropped from 12.25% in October 2025 to 11.75% in January 2026 and stayed there through September. It only moves when prime moves, so a flat line means prime held steady.
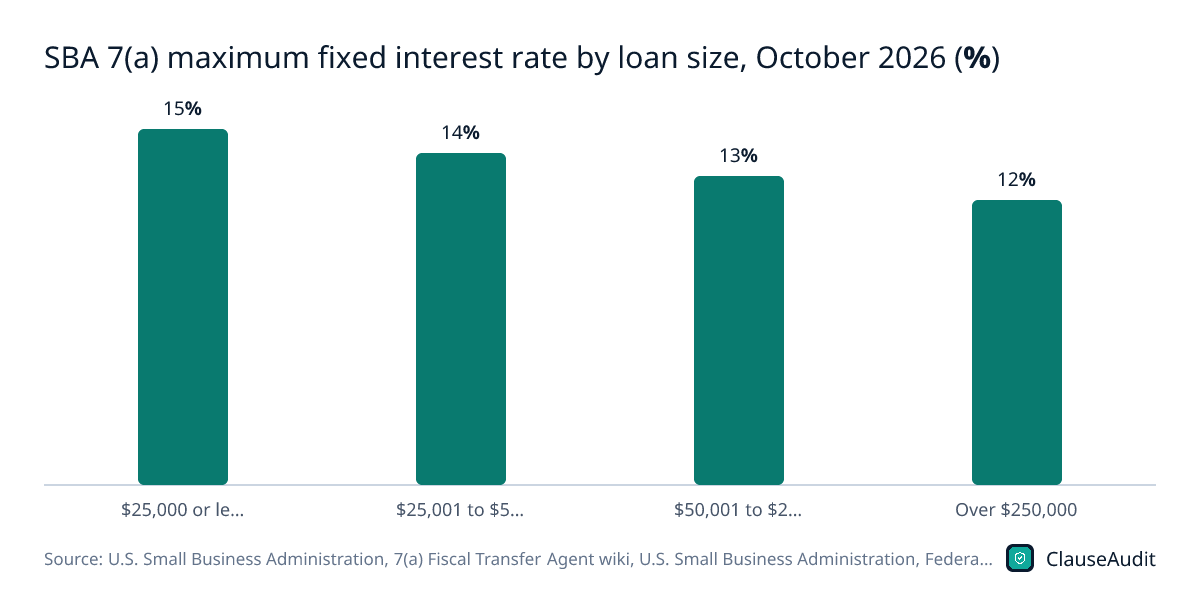
Download this chart (PNG)SBA 7(a) maximum fixed interest rate by loan size, October 2026 (%)
Chart data
| Label | Value (%) |
|---|---|
| $25,000 or less | 15% |
| $25,001 to $50,000 | 14% |
| $50,001 to $250,000 | 13% |
| Over $250,000 | 12% |
Each step down in loan size adds a point to the ceiling. A borrower asking for $25,000 or less can legally be quoted up to 15%, while a borrower over $250,000 tops out at 12%.
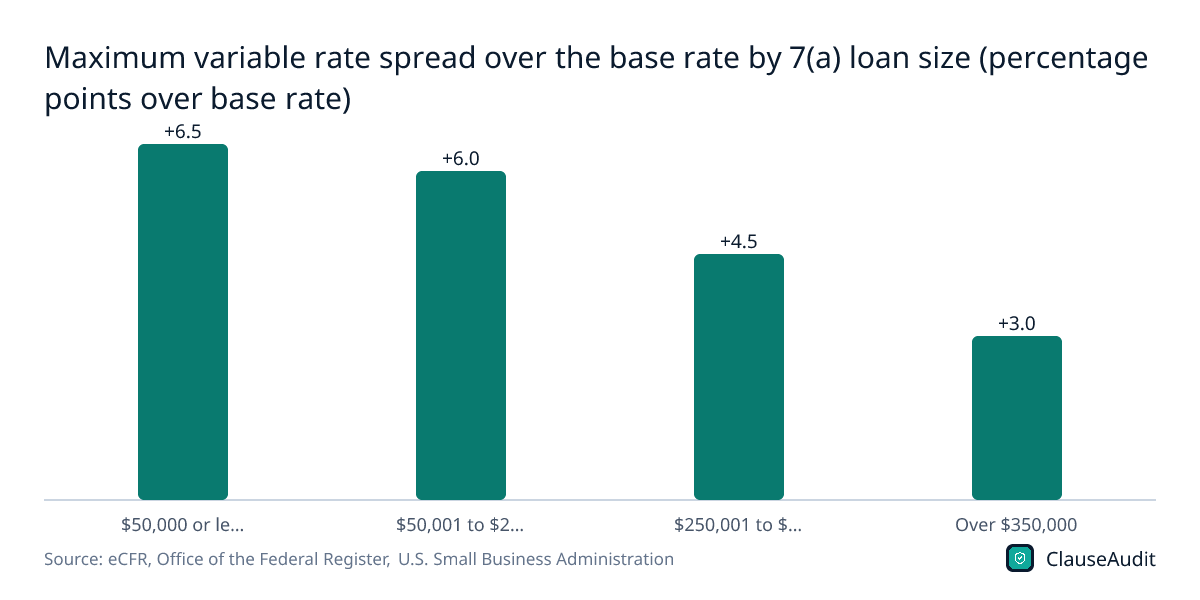
Download this chart (PNG)Maximum variable rate spread over the base rate by 7(a) loan size (percentage points over base rate)
Chart data
| Label | Value (percentage points over base rate) |
|---|---|
| $50,000 or less | +6.5 |
| $50,001 to $250,000 | +6.0 |
| $250,001 to $350,000 | +4.5 |
| Over $350,000 | +3.0 |
Variable caps are a spread, not a fixed number. Your actual ceiling is whatever prime or the SBA peg rate is that day, plus these points, so it will rise if rates rise.
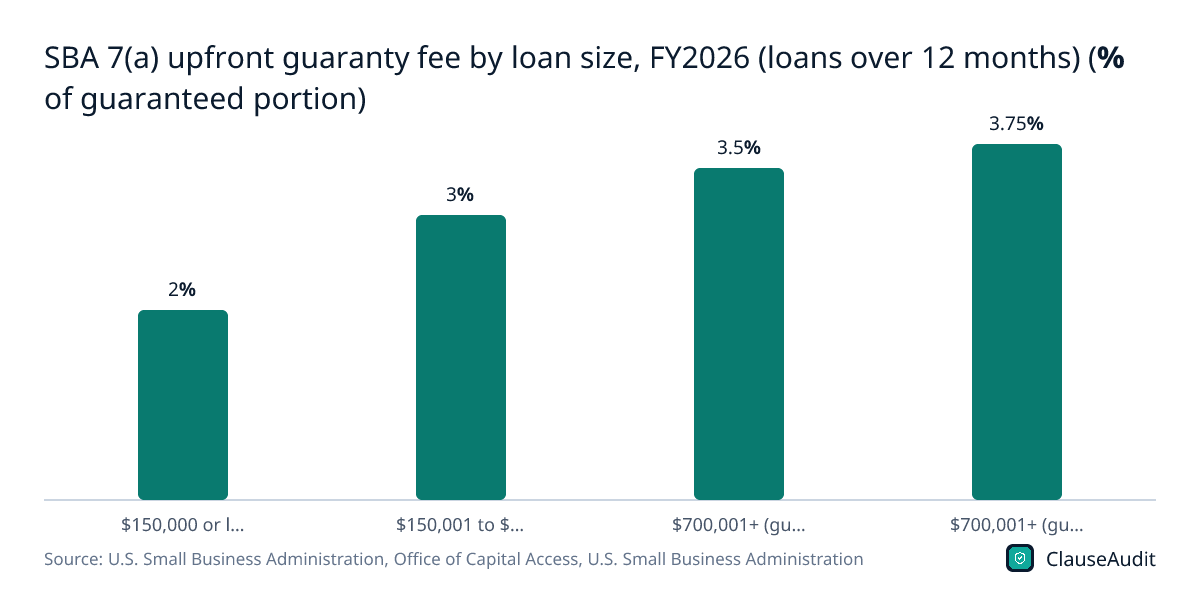
Download this chart (PNG)SBA 7(a) upfront guaranty fee by loan size, FY2026 (loans over 12 months) (% of guaranteed portion)
Chart data
| Label | Value (% of guaranteed portion) |
|---|---|
| $150,000 or less | 2% |
| $150,001 to $700,000 | 3% |
| $700,001+ (guaranteed portion up to $1M) | 3.5% |
| $700,001+ (guaranteed portion over $1M) | 3.75% |
The fee is charged on the guaranteed portion, not the full loan amount. That matters because the SBA guarantees up to 85% of smaller loans and up to 75% of larger ones.
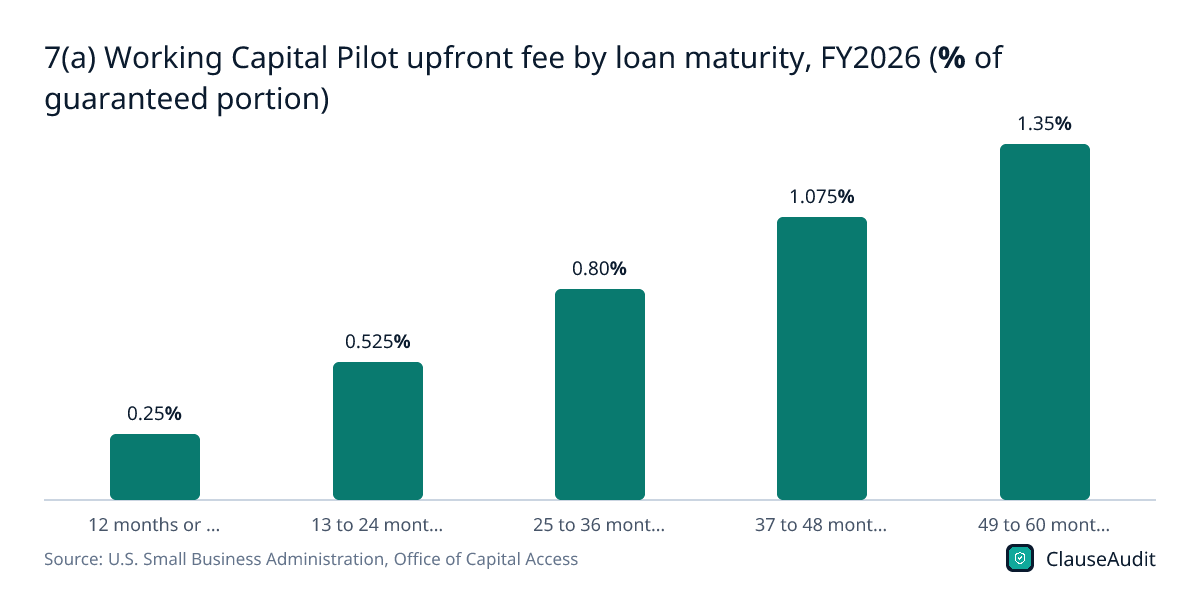
Download this chart (PNG)7(a) Working Capital Pilot upfront fee by loan maturity, FY2026 (% of guaranteed portion)
Chart data
| Label | Value (% of guaranteed portion) |
|---|---|
| 12 months or less | 0.25% |
| 13 to 24 months | 0.525% |
| 25 to 36 months | 0.80% |
| 37 to 48 months | 1.075% |
| 49 to 60 months | 1.35% |
Working Capital Pilot loans price the fee by term instead of size. A loan of 12 months or less pays 0.25%, and the fee climbs to 1.35% at 49 to 60 months.
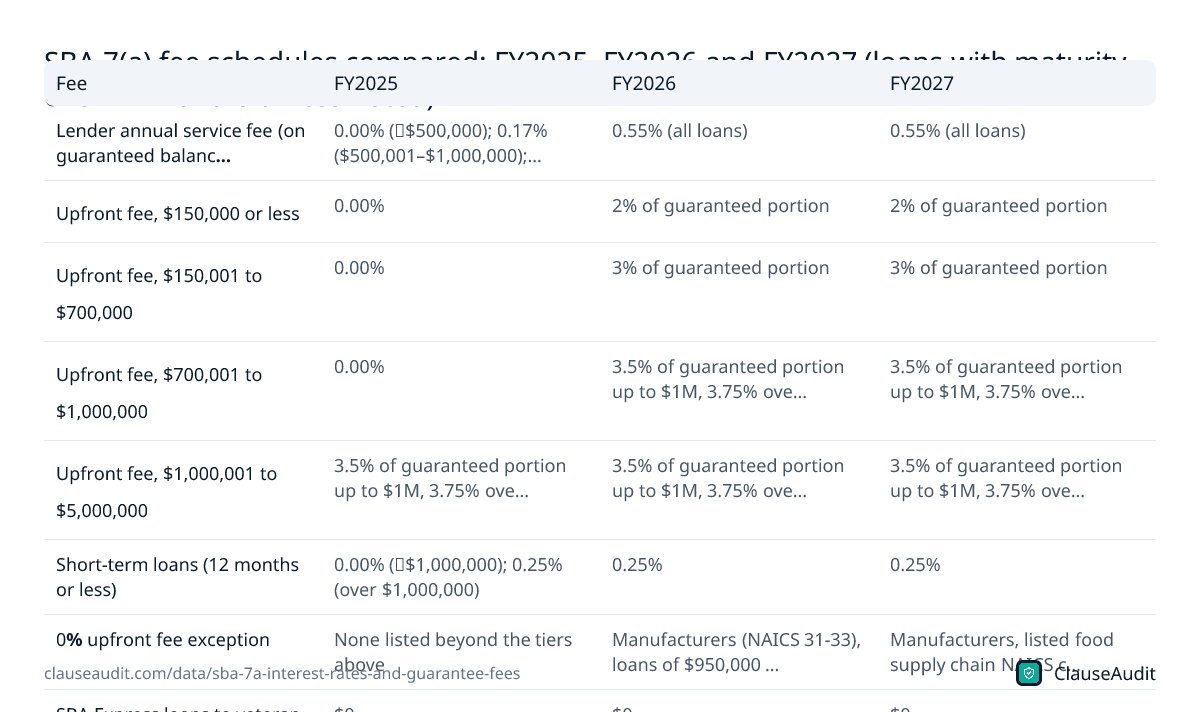
Download this chart (PNG)SBA 7(a) fee schedules compared: FY2025, FY2026 and FY2027 (loans with maturity over 12 months unless noted)
| Fee | FY2025 | FY2026 | FY2027 |
|---|---|---|---|
| Lender annual service fee (on guaranteed balance) | 0.00% (≤$500,000); 0.17% ($500,001–$1,000,000); 0.55% ($1,000,001–$5,000,000) | 0.55% (all loans) | 0.55% (all loans) |
| Upfront fee, $150,000 or less | 0.00% | 2% of guaranteed portion | 2% of guaranteed portion |
| Upfront fee, $150,001 to $700,000 | 0.00% | 3% of guaranteed portion | 3% of guaranteed portion |
| Upfront fee, $700,001 to $1,000,000 | 0.00% | 3.5% of guaranteed portion up to $1M, 3.75% over $1M | 3.5% of guaranteed portion up to $1M, 3.75% over $1M |
| Upfront fee, $1,000,001 to $5,000,000 | 3.5% of guaranteed portion up to $1M, 3.75% over $1M | 3.5% of guaranteed portion up to $1M, 3.75% over $1M | 3.5% of guaranteed portion up to $1M, 3.75% over $1M |
| Short-term loans (12 months or less) | 0.00% (≤$1,000,000); 0.25% (over $1,000,000) | 0.25% | 0.25% |
| 0% upfront fee exception | None listed beyond the tiers above | Manufacturers (NAICS 31-33), loans of $950,000 or less (not MARC) | Manufacturers, listed food supply chain NAICS codes and rural-area businesses, loans of $700,000 or less |
| SBA Express loans to veteran-owned businesses | $0 | $0 | $0 |
| Loans approved | Oct 1, 2024, Sep 30, 2025 | Oct 1, 2025, Sep 30, 2026 | Oct 1, 2026, Sep 30, 2027 |
Source: U.S. Small Business Administration, SBA Information Notice 5000-858936: 7(a) Fees Effective October 1, 2024, for Fiscal Year 2025; U.S. Small Business Administration, Office of Capital Access, SBA Information Notice 5000-872051: 7(a) Fees Effective October 1, 2025 for Fiscal Year 2026 and 90-Day Rule Clarification; U.S. Small Business Administration, SBA Information Notice 5000-881797: 7(a) Fees Effective October 1, 2026 for Fiscal Year 2027 and 90-Day Rule Clarification. Download as image
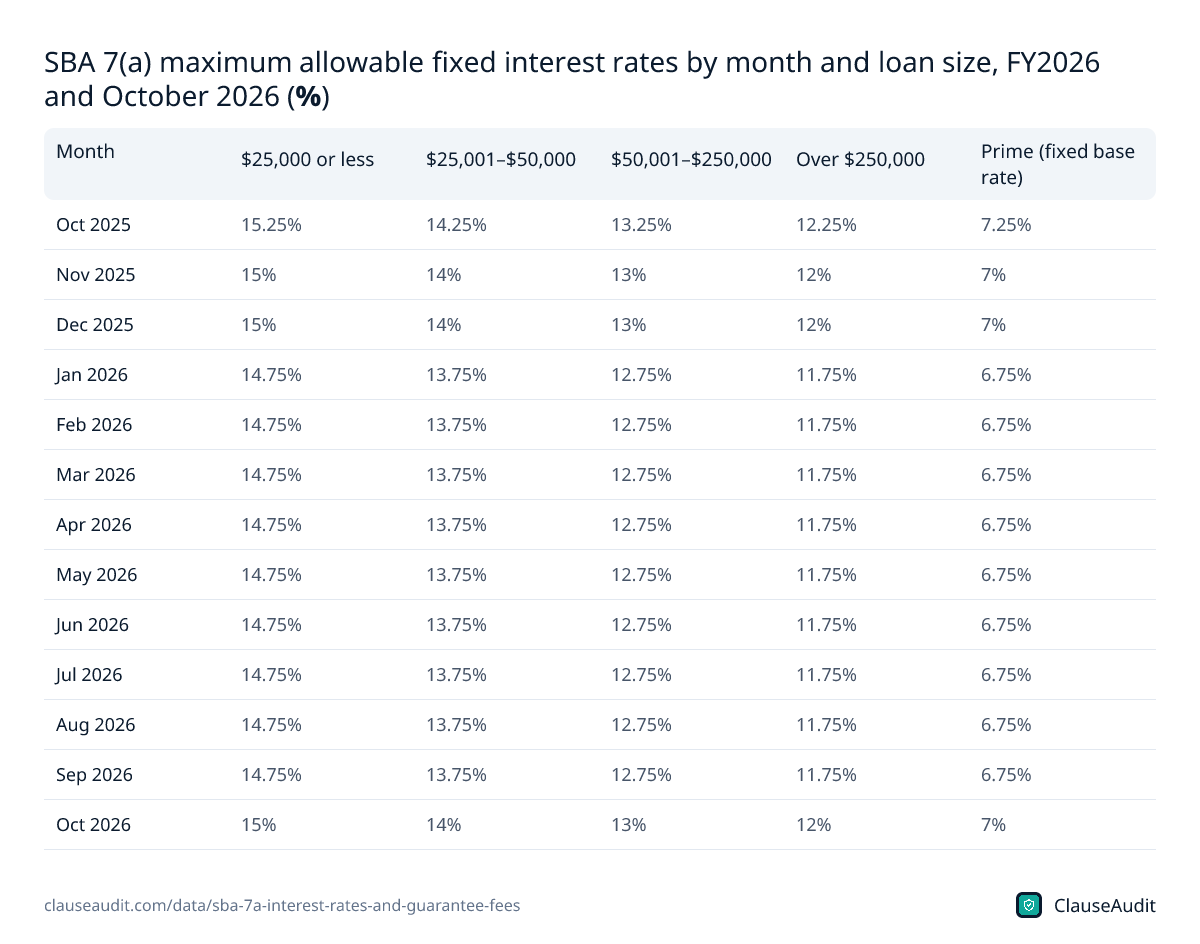
SBA 7(a) maximum allowable fixed interest rates by month and loan size, FY2026 and October 2026 (%)
| Month | $25,000 or less | $25,001–$50,000 | $50,001–$250,000 | Over $250,000 | Prime (fixed base rate) |
|---|---|---|---|---|---|
| Oct 2025 | 15.25% | 14.25% | 13.25% | 12.25% | 7.25% |
| Nov 2025 | 15% | 14% | 13% | 12% | 7% |
| Dec 2025 | 15% | 14% | 13% | 12% | 7% |
| Jan 2026 | 14.75% | 13.75% | 12.75% | 11.75% | 6.75% |
| Feb 2026 | 14.75% | 13.75% | 12.75% | 11.75% | 6.75% |
| Mar 2026 | 14.75% | 13.75% | 12.75% | 11.75% | 6.75% |
| Apr 2026 | 14.75% | 13.75% | 12.75% | 11.75% | 6.75% |
| May 2026 | 14.75% | 13.75% | 12.75% | 11.75% | 6.75% |
| Jun 2026 | 14.75% | 13.75% | 12.75% | 11.75% | 6.75% |
| Jul 2026 | 14.75% | 13.75% | 12.75% | 11.75% | 6.75% |
| Aug 2026 | 14.75% | 13.75% | 12.75% | 11.75% | 6.75% |
| Sep 2026 | 14.75% | 13.75% | 12.75% | 11.75% | 6.75% |
| Oct 2026 | 15% | 14% | 13% | 12% | 7% |
Source: U.S. Small Business Administration, 7(a) Fiscal Transfer Agent wiki, New Maximum Allowable Fixed Rate for 7(a) Loans (SBA_Max_Allowed_Fixed-Rates.xlsx, sheet 'Max Fixed Rates FROM 11-06-2018'). Download as image
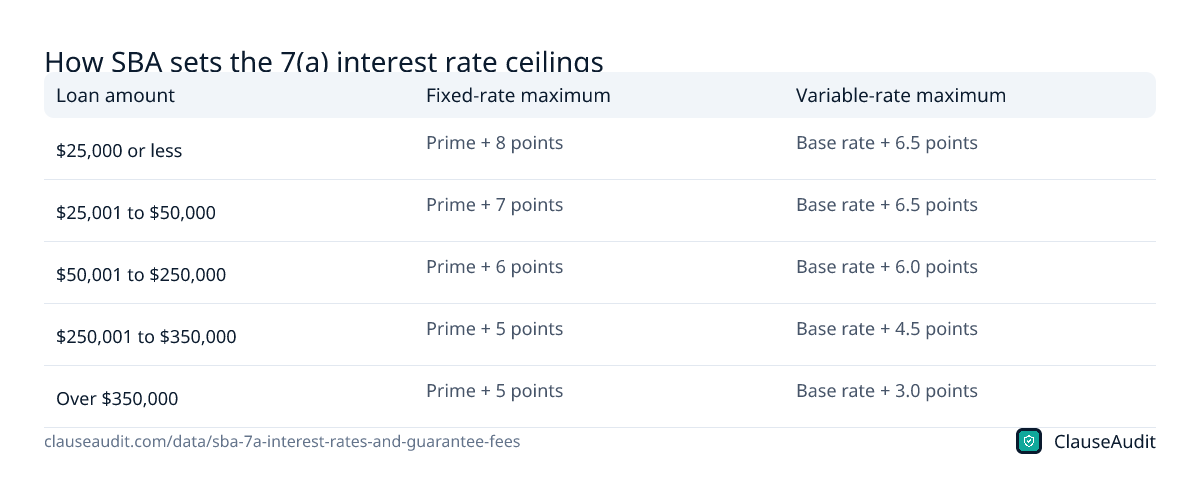
How SBA sets the 7(a) interest rate ceilings
| Loan amount | Fixed-rate maximum | Variable-rate maximum |
|---|---|---|
| $25,000 or less | Prime + 8 points | Base rate + 6.5 points |
| $25,001 to $50,000 | Prime + 7 points | Base rate + 6.5 points |
| $50,001 to $250,000 | Prime + 6 points | Base rate + 6.0 points |
| $250,001 to $350,000 | Prime + 5 points | Base rate + 4.5 points |
| Over $350,000 | Prime + 5 points | Base rate + 3.0 points |
Source: U.S. Small Business Administration, Federal Register, Maximum Allowable 7(a) Fixed Interest Rates, 87 FR 46883 (FR Doc. 2022-16162); eCFR, Office of the Federal Register, 13 CFR 120.214 What conditions apply for variable interest rates?; U.S. Small Business Administration, 7(a) loan program: Terms, conditions and eligibility. Download as image
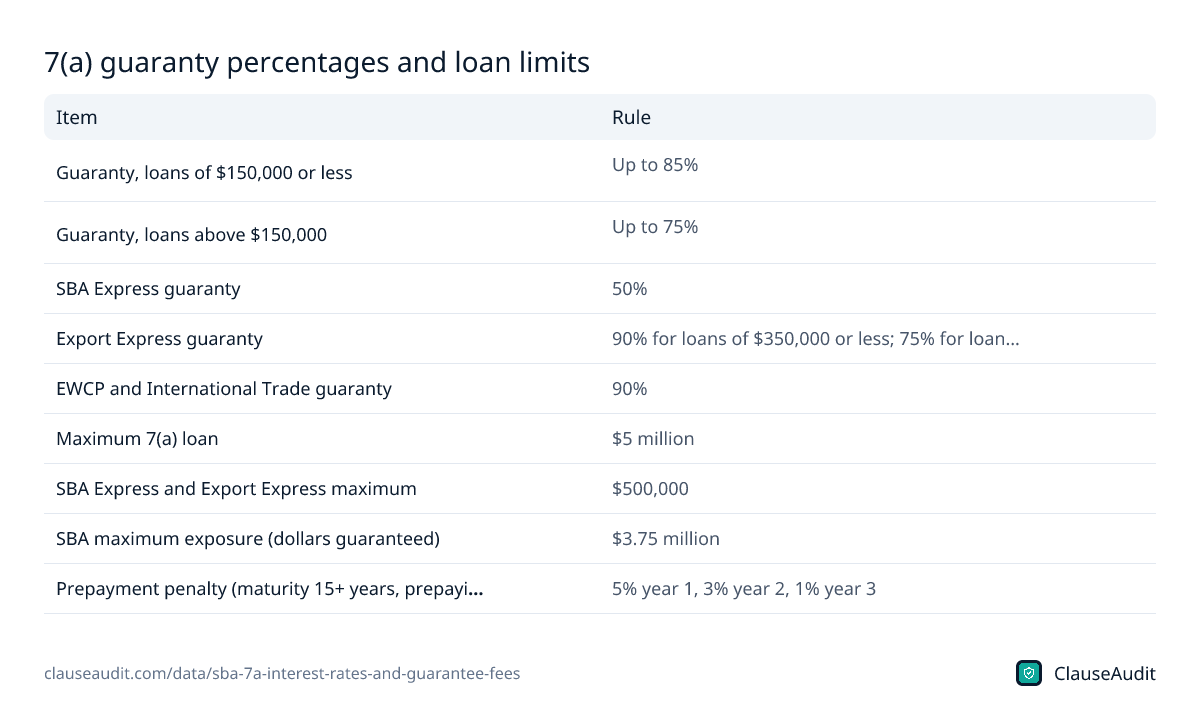
7(a) guaranty percentages and loan limits
| Item | Rule |
|---|---|
| Guaranty, loans of $150,000 or less | Up to 85% |
| Guaranty, loans above $150,000 | Up to 75% |
| SBA Express guaranty | 50% |
| Export Express guaranty | 90% for loans of $350,000 or less; 75% for loans over $350,000 |
| EWCP and International Trade guaranty | 90% |
| Maximum 7(a) loan | $5 million |
| SBA Express and Export Express maximum | $500,000 |
| SBA maximum exposure (dollars guaranteed) | $3.75 million |
| Prepayment penalty (maturity 15+ years, prepaying 25%+ in first 3 years) | 5% year 1, 3% year 2, 1% year 3 |
Source: U.S. Small Business Administration, 7(a) loan program: Terms, conditions and eligibility. Download as image
What are SBA 7(a) interest rates right now?
Start with prime. In October 2026 the fixed base rate was 7%. The SBA then adds a maximum spread based on loan size: 8 points for $25,000 or less, 7 points for $25,001 to $50,000, 6 points for $50,001 to $250,000 and 5 points above that. That gives fixed-rate caps of 15%, 14%, 13% and 12%.
Variable loans work on a different scale. The cap is the base rate plus 6.5 points for loans of $50,000 or less, plus 6.0 for $50,001 to $250,000, plus 4.5 for $250,001 to $350,000 and plus 3.0 for anything over $350,000. The base rate can be prime or the SBA Optional Peg Rate.
Notice that the variable spreads are never wider than the fixed ones. On loans over $350,000 the gap is biggest: base rate plus 3.0 points variable, against prime plus 5 points fixed. A lender can accept a smaller margin when it can pass rate changes on to you. You pay for that with uncertainty. If prime climbs, so does your payment.
Across FY2026 the fixed cap for loans over $250,000 ranged from 12.25% down to 11.75%. The cap that applies to you is the one in effect when the SBA receives your application, so a delay in getting your application to the SBA while prime is rising can cost you.
A rate under the cap is not automatically a good rate. The cap is a legal limit, not a market price. Get quotes from two or three SBA lenders and compare the spread each one adds to prime. A difference of even one point, held over a long term, adds up to real money.
How much is the SBA guarantee fee in FY2026?
For loans with a maturity over 12 months, the upfront guarantee fee is 2% of the guaranteed portion on loans of $150,000 or less, 3% on loans of $150,001 to $700,000, and on loans of $700,001 to $5,000,000 it is 3.5% of the guaranteed portion up to $1M plus 3.75% on anything above that.
Compare that with FY2025. Back then, loans up to $1,000,000 carried a 0.00% upfront fee. A loan approved in September 2025 and the same loan approved in October 2025 could carry very different costs at closing. The FY2027 notice keeps the same fee tiers, so do not wait for the zero-fee year to return.
Short-term loans of 12 months or less pay 0.25%. Working Capital Pilot loans scale by term, from 0.25% up to 1.35%.
There is one large exception. Manufacturers in NAICS codes 31 to 33 pay 0% on 7(a) loans of $950,000 or less in FY2026 (MARC loans excluded). For FY2027 the 0% fee covers loans of $700,000 or less to manufacturers, listed food supply chain businesses and rural-area businesses. If your business might fit, ask the lender to confirm your code before the fee is quoted.
Who pays the SBA guarantee fee, you or the lender?
Technically the lender owes the upfront fee to the SBA. In practice it is passed to you, either paid at closing or added to the loan balance. If it is financed, you pay interest on it for the life of the loan.
The annual service fee is different. It is 0.55% of the outstanding guaranteed balance on every FY2026 7(a) loan, and lenders may not pass it on to the borrower. If your fee sheet shows an ongoing SBA servicing charge, ask what it is for. It may be a lender fee dressed up with an SBA label.
Then look at everything else on the closing statement. Packaging fees, broker fees, appraisal and environmental reports, legal fees and the lender's own origination charge are not part of the SBA guarantee fee. Each one should be listed, and you should know who agreed to it.
Is a smaller SBA loan more expensive?
On rate, often yes. A loan of $25,000 or less can carry a fixed rate up to 15%, against 12% for loans over $250,000. Part of the reason is that the paperwork costs a lender about the same no matter the size.
On fees, smaller loans come out ahead. The upfront fee is 2% of the guaranteed portion on loans of $150,000 or less, against 3% or more on larger loans. SBA Express loans to veteran-owned businesses carry a $0 upfront fee.
Take two owners. One borrows $25,000 to cover a slow season. The other borrows a bit over $250,000 to buy a building. The first can be quoted up to 15% fixed and pays the lowest fee tier. The second faces a 12% ceiling and the 3% fee. Neither one is getting a bad deal by default. They are buying different things.
So the honest answer depends on how long you keep the loan. Fees are paid once. Interest is paid every month. On a long equipment or real estate loan, a lower rate usually matters more than a lower fee. On a short working capital loan you plan to pay off early, the fee takes a bigger share of your total cost.
What to do before you sign
- Ask for the rate in writing as prime plus a stated spread, then check that spread against the SBA maximum for your loan size.
- If the rate is variable, find out which index it follows, how often it adjusts and whether there is any floor that stops it from falling.
- Get an itemized list of every fee and confirm which one is the SBA upfront guarantee fee and how it was calculated.
- Check the prepayment terms. On loans with a maturity of 15+ years, prepaying 25%+ in the first 3 years can trigger a fee of 5% in year 1, 3% in year 2 and 1% in year 3.
- Read the personal guarantee and collateral sections closely. SBA loans typically require owners to guarantee personally, and the lien may cover more than the asset you are buying.
- Look at default triggers beyond missed payments, such as a change in ownership or a drop in financial ratios, and what the lender can do when one happens.
How ClauseAudit helps
The SBA caps tell you the most a lender can charge. Your loan agreement, note and guarantee tell you what you will actually pay and what happens when something goes wrong. An automated review of your financing documents pulls out the terms that change your cost and your risk, so you can raise them before closing.
- Interest rate, index and spread, and how often a variable rate can adjust
- Every fee at closing, including the SBA guarantee fee and any lender or broker charges
- Prepayment penalties and when they stop applying
- Personal guarantee scope, including whether it is unlimited or covers other debts
- Collateral and blanket liens on business or personal assets
- Default triggers, late fees and default interest rates
Frequently asked questions
What is the maximum interest rate on an SBA 7(a) loan?
It depends on loan size and rate type. For October 2026, fixed-rate caps were 15% for $25,000 or less, 14% for $25,001 to $50,000, 13% for $50,001 to $250,000 and 12% over $250,000. Variable loans are capped at the base rate plus 6.5 points for small loans, down to plus 3.0 points for loans over $350,000.
How is the SBA 7(a) rate calculated?
The lender picks a base rate, usually prime, and adds a spread. The SBA limits how big that spread can be. For fixed loans the cap is prime plus 5 to 8 points depending on loan size. Your lender can charge less than the cap, so ask for the spread in writing and compare it with other lenders.
How much is the SBA guarantee fee in 2026?
For FY2026 loans with a maturity over 12 months, the upfront fee is 2% of the guaranteed portion for loans of $150,000 or less and 3% for $150,001 to $700,000. Larger loans pay 3.5% on the guaranteed portion up to $1M and 3.75% above that. Short-term loans of 12 months or less pay 0.25%.
Is the SBA guarantee fee charged on the whole loan?
No. It is charged on the guaranteed portion only. The SBA guarantees up to 85% of loans of $150,000 or less and up to 75% of larger loans. So the fee applies to that share, not the full amount you borrow. Ask the lender to show the guaranteed amount and the fee calculation on your closing statement.
Can the lender pass the annual service fee on to me?
No. The lender's annual service fee is 0.55% of the outstanding guaranteed balance for FY2026 loans, and SBA rules say lenders may not pass it on to the borrower. The upfront guarantee fee is different and is normally paid by the borrower at closing or financed into the loan.
Do manufacturers pay SBA 7(a) fees in FY2026?
Manufacturers in NAICS codes 31 to 33 pay a 0% upfront fee on 7(a) loans of $950,000 or less in FY2026. For FY2027 the waiver covers loans of $700,000 or less and extends to listed food supply chain businesses and rural-area businesses. Confirm your NAICS code with the lender before the fee is set.
Is there a prepayment penalty on SBA 7(a) loans?
Only on some. If the maturity is 15+ years and you prepay 25%+ of the loan in the first 3 years, the SBA fee is 5% in year 1, 3% in year 2 and 1% in year 3. After that it falls away. Check your note for any other prepayment terms before you sign.
Should I choose a fixed or variable SBA loan?
Variable caps are never wider than fixed caps, and on loans over $350,000 they are much tighter, so the starting rate can be lower. The trade-off is risk: if prime rises, your payment rises with it. A fixed rate gives you a payment you can plan around. Pick based on how long you will hold the loan and how tight your cash flow is.
How large can an SBA 7(a) loan be?
The maximum 7(a) loan is $5 million, and the SBA's maximum exposure is $3.75 million in guaranteed dollars. SBA Express and Export Express loans top out at $500,000, with a 50% guarantee on SBA Express. Bigger loans also carry the higher upfront fee tiers, so price the fee in early.
Use this data
Every chart and card below is free to reuse under CC BY 4.0. Download what you need and link back to this page.
 Stat cards
 Key findings card
 Infographic
 SBA 7(a) maximum fixed interest rate, loans over $250,000, by month, FY2026 (%)
 SBA 7(a) maximum fixed interest rate by loan size, October 2026 (%)
 Maximum variable rate spread over the base rate by 7(a) loan size (percentage points over base rate)
 SBA 7(a) upfront guaranty fee by loan size, FY2026 (loans over 12 months) (% of guaranteed portion)
 7(a) Working Capital Pilot upfront fee by loan maturity, FY2026 (% of guaranteed portion)
 SBA 7(a) fee schedules compared: FY2025, FY2026 and FY2027 (loans with maturity over 12 months unless noted)
 SBA 7(a) maximum allowable fixed interest rates by month and loan size, FY2026 and October 2026 (%)
 How SBA sets the 7(a) interest rate ceilings
 7(a) guaranty percentages and loan limits
Embed the infographic
Free to share on your site, blog or slides under CC BY 4.0. Please keep the credit link.
Sources and method
Every number on this page comes from the sources below, each opened and read on or before October 18, 2026. A second, independent review checked every figure against its source and corrected anything that did not match. Figures that could not be confirmed were left out.
- U.S. Small Business Administration, Office of Capital Access, SBA Information Notice 5000-872051: 7(a) Fees Effective October 1, 2025 for Fiscal Year 2026 and 90-Day Rule Clarification (August 28, 2025)
- U.S. Small Business Administration, SBA Information Notice 5000-858936: 7(a) Fees Effective October 1, 2024, for Fiscal Year 2025 (July 23, 2024)
- U.S. Small Business Administration, SBA Information Notice 5000-881797: 7(a) Fees Effective October 1, 2026 for Fiscal Year 2027 and 90-Day Rule Clarification (Published September 3, 2026; effective October 1, 2026)
- U.S. Small Business Administration, 7(a) Fiscal Transfer Agent wiki, New Maximum Allowable Fixed Rate for 7(a) Loans (SBA_Max_Allowed_Fixed-Rates.xlsx, sheet 'Max Fixed Rates FROM 11-06-2018') (October 2026 update (posted October 6, 2026))
- U.S. Small Business Administration, Federal Register, Maximum Allowable 7(a) Fixed Interest Rates, 87 FR 46883 (FR Doc. 2022-16162) (August 1, 2022)
- eCFR, Office of the Federal Register, 13 CFR 120.214 What conditions apply for variable interest rates? (Current text, last amended August 1, 2022 (87 FR 38908))
- U.S. Small Business Administration, 7(a) loan program: Terms, conditions and eligibility (Accessed October 18, 2026 (no date printed))
- U.S. Small Business Administration, News release 25-80: SBA Waives Loan Fees for Small Manufacturers in Fiscal Year 2026 (September 18, 2025)
Cite this page
ClauseAudit, “SBA 7(a) Maximum Interest Rates and Guarantee Fees for FY2026”, updated October 18, 2026, https://clauseaudit.com/data/sba-7a-interest-rates-and-guarantee-fees. Free to reuse with a link back (CC BY 4.0).
This page summarises published data and law as checked on October 18, 2026. Figures are updated as new editions are released, and your own situation may differ. It is general information, not legal, tax or financial advice.